

Options aficionado. Daily content on derivatives, vol, flow, and crypto. If it has optionality, I'm interested. Based in Antwerp.
Antwerpen
Joined October 2008
- Tweets2.2K
- Following319
- Followers680
- Likes237





Koen Hoorelbeke retweeted

After a big move, I want to know whether skew agrees with it.
Say something sells off by more than its expected move on the week, and put skew pops at the same time. Skew's moving in the same direction as spot, so it's backing up the move. When this happens I tend to stay out the way.
Same on the upside. A sharp rally with call skew getting dragged along with it. if anything the breakout is on and you want to buy dips.
If spot and skew are doing opposite things, that's a divergence. Say a really sharp rally and the put skew's held up very well. All that does is say pay attention. Potentially something's not lining up. And hedging some longs might not be a bad idea.
It's by no means a foolproof indicator, so I wouldn't just blindly trade on it, but just another lens to watch the market through.
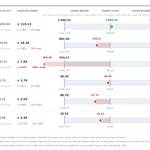
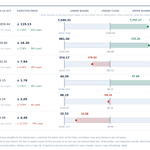
$VIX closed Monday at 18.39 while VIX1D fell to 10.49, the bottom fifth of its range. SKEW held 150.97, above its 145.66 median: far downside costs more though the next session got cheap.
Index puts were also bought outright Monday.
Full brief: link in bio.
Implied correlation fell 7.00% on Monday to 13.95, from 15.00, our store's high. Dispersion rose 2.95% to 38.02.
Single names agree: the Nasdaq 100 fund lost 15.1 IV rank points, T-Mobile US gained 10.7 into Wednesday, so premium sits with company events.
One event or many?
Premium leaves a Fed week - Options Brief - 27 October 2026 social.saxo/zskkkwl via @saxobank
One quiet session took almost a fifth out of the range the option market had priced for this week. The Federal Reserve, the European Central Bank and three of the index’s largest results are all still inside it.

Market Quick Take - Anthropic files IPO paperwork - 27 October 2026 social.saxo/2ilm48n via @saxobank

Amazon earnings between a typical report and Julys 15 jump social.saxo/czzmjk9 via @saxobank
Five of Amazon's last eight reports moved the shares less than the options now price for 29 October 2026; the last one moved them twice as much. An iron condor and a long strangle show what each reading assumes.

UBS reports on Wednesday two ways to name your price while Bern decides social.saxo/ktk2g7p via @saxobank
UBS reports third-quarter results on 28 October 2026 while Swiss lawmakers are still deciding how much capital the bank must hold. One investor wants to buy lower, another already owns the shares. How can each name a price and be paid to wait?

Twenty-one options markets where premium stood out on 23 October social.saxo/7kwhhha via @saxobank
Home Depot and Lowe’s options both became much dearer against their own year last week, while Netflix and Sodexo cooled sharply. Twenty-one readings from the 23 October close, and what a volatility number still cannot tell you.

Paying for the index not the names - Options Brief - 26 October 2026 social.saxo/3jnmz92 via @saxobank
Implied correlation closed at its highest since June while dispersion sat on its median. The option market has decided this week moves as one block, and it has four sessions to be proved right. $SPY

Microsoft earnings: is the options market leaning up or down? social.saxo/jz3kygt via @saxobank
Microsoft shares fell after five of the last eight reports, yet the biggest move went up. Two mirror-image spreads show whether option prices lean either way ahead of the 28 October results. $MSFT

Market Quick Take - Big week ahead as FOMC ECB and BoJ all to meet - 26 October 2026 social.saxo/peggunl via @saxobank

On Thursday SKEW rose 2.03 to 152.39 while $SPX fell 1.21%: the tail was already dear and got dearer on a modest fall. This morning Friday's expiry prices 55.45 points; Thursday's quote was 59.60, and decay alone would leave about 42.1. Full brief: link in bio.
$SPX closed Thursday 3.99 points above the week's start, having used 3% of the 119.13 points, 1.56%, that options priced around last Friday's close. Thursday's 93.74-point fall gave back four sessions, so most of the range is unused.
One session left: does it end where it began?

$SPX fell 1.21% on Thursday while the equal-weighted S&P rose 0.77%, so the loss sat in the largest names. All 14 measures on the vol board rose, VIX1D most: up 33.39% to 15.18, so one session is priced at 0.80 of a month against 0.68 a day earlier. The front took the adjustment.

Somebody already has Claude Duet ? Funny thing, since months I already have a Claude agent who does exactly what Duet does. My agent is called Claudette :) She changed my life! Once you have an agent (actually have an agent team across multiple models, like ChatGPT and Gemini which communicate with each other), you'll never go back!
Do you already use agents?
Yesterday's options flow (22 oct)
markets: unclear
mag7: unclear
crypto: unclear
biotech: unclear
metals: unclear
energy: unclear
rates: hedging
risk-off: unclear
semis: unclear
financials: unclear
Markets
Tape on 22 Oct: USD 6.40bn confirmed-opening premium, 94.8% puts. Yet all 30 biggest lines are deep ITM and nearly all printed mid: ORCL Jan-27 220Ps, LULU Dec 300/350, SNDK, AVGO. Financing and stock replacement, not a bearish bet. Label: unclear. #QQQ
Mag7
Mag7 confirmed-opening flow 22 Oct: USD 512.1m, 81.9% puts. Reads bearish until you look: the seven largest lines are deep ITM META puts expiring 23 Oct, crossed mid on multi-leg floor codes, with sells against buys at one stamp. Mechanics, not conviction. #Mag7
Crypto
Crypto flow 22 Oct: USD 141.5m confirmed opening premium, 83.8% puts. Nearly all of it is deep-ITM intrinsic: an IREN 23-Oct strip across 32-40 and a COIN 300/320/340 put roll. Bought 24.9m vs sold 28.8m. Mechanics, not a bearish signal. #bitcoin #COIN
Biotech
Biotech ETF flow on 22 Oct paid for two different things at once: USD 0.74m of puts, all in XLV, against USD 0.65m of calls, almost all in XBI and IBB. The biggest line was a mid-market Mar-2027 XLV 180 put package. A pair trade, not a view. #XLV #XBI
Metals
METALS flow 22-Oct-26: USD 806.8m confirmed opening, 97.4% put premium. The 30 biggest lines are all deep-ITM GLD and SLV puts, printed at mid under multi-leg floor codes and rolled across five expiries. Financing, not a bearish bet. #gold #silver
Energy
Energy flow 22 Oct: 89 confirmed-opening trades, USD 24.5m, 71% of premium in calls. One XLE Jun-27 66 call block took USD 8.4m on 12,000 lots vs 319 OI, all at mid. The only bid-side prints were call sales in XLE, MPC and SLB. #energy
Rates
Rates ETF tape, 22 Oct: USD 5.6m confirmed opening premium, 65.5% calls. But the near-dated TLT 83 and 82.5 calls printed on the bid while two 50,000-lot HYG 30-Oct put legs opened into FOMC week. Defensive, not bullish. #TLT #HYG #ratesvol
Risk-off
Risk-off ETF tape, 22 Oct: USD 6.8m of confirmed-opening premium, 81% of it in puts. Every large line crossed mid, and the second biggest print was a 25,225-lot XLU 30-Oct 43 call marked ToOpen. Protection or sold premium, the tape will not say which. #XLP
Semis
Semis flow 22 Oct: USD 2.07bn confirmed opening, 95.1% in puts. Nearly all deep ITM, mostly mid-market, much of it 23-Oct expiry. AMD 580 to 620 puts bought and sold on one timestamp. Financing and rolls, not protection. One clean long: MU Jan-27 1030 calls, USD 15.1m. #semiconductors
Financials
Financials 22 Oct: USD 58.0m confirmed opening premium, 82.9% in puts. The top line is a USD 6.5m BAC 20-Nov 60 put, deep ITM at mid, and its neighbours print SellToOpen. Financing, not fear. One clean hedge: a USD 1.0m KRE 65 put. #financials
Three per cent of the range one session left - Options Brief - 23 October 2026 home.saxo/content/articles/o… via @saxobank
Thursday took 93 points out of the S&P 500 and left the index four points higher on the week. The option market spent the session repricing the next few days rather than the market.

Your platform already knows more than it shows you social.saxo/gbgsgmf via @saxobank
AI assistants now let traders who do not write code use the Saxo OpenAPI by asking plain questions. How the route works, where to stay careful, and a live build on 4 November.

Novartis reports Q3 results on 27 Oct. Results days have been calm; its sharpest fall this year, 10.9% on 8 Sep, came from trial news. Two ways to name a price: a cash-secured put and a covered call. Options carry a high risk of rapid loss. $NOVN
Full article: link in bio.

Koen Hoorelbeke retweeted
Say you buy a VIX call a few months out as a crash hedge and the crash comes tomorrow. It might not do that much for you.
The way I'd think about it is that the nature of your exposure changes as you get closer to expiry. Early on, your option's priced off the VIX future, and that's a forward vol contract. It's reflecting what the market expects the VIX to be by the time that future expires.
So in a sell-off, spot VIX can go a long way in very short order while the future moves a lot less, because the market immediately prices things to have calmed down by then.
The closer you get to expiry, the more the future starts behaving like spot VIX. That's when it gets more volatile and gives you the explosiveness you were hoping for.
And those far out of the money VIX calls are probably the most expensive part of the surface, like in the whole of equity derivatives. Depends on the scenario you're going for, but I don't think there are many where that option does well. And even when it does, you get a very narrow window to monetise it.