
We invest in founders and companies who are passionately building towards a blockchain-based economy. Telegram Group: https://xitter.gq/t.co/0hi9uYoz9p
Joined April 2021
- Tweets4.8K
- Following366
- Followers183K
- Likes1.3K




Pinned Tweet
Weekly Crypto Brief is live 📊
Market insights. Key trends. Strong signals.
All in one place — everything that shaped last week in crypto.
Dive into the poster👇

OpenRouter showed the power of making AI models accessible. MEGA is taking it a step further — making AI inference verifiable, competitive, and permissionless. @mega_holdings
From building faster blockchains to building better markets for intelligence.
Bullish on this new chapter of @megaeth!

Today, we commit $30 million to build new products on MegaETH, starting with AI inference.
mega.holdings
11
2,321
As more private credit and managed yield strategies move onchain, the information needed to underwrite them often remains fragmented and delayed. Capital can move around the clock, yet lenders may have limited visibility into where funds are deployed, how leverage changes, or what exposures a borrower has elsewhere.
That uncertainty comes at a cost: higher collateral requirements, tighter credit limits, and less capital available to otherwise viable businesses.
We believe continuous, privacy-preserving verification can help change that equation, giving institutions a better basis for pricing and monitoring risk without requiring them to disclose their entire books.
@AccountableData's Chapter 2 builds on this by connecting verified financial data with fund accounting, administration, and the infrastructure for launching and managing onchain financial products.
Ultimately, the opportunity is to make institutional credit easier to underwrite and more capital-efficient.

OKX Ventures retweeted

Meet the backers helping us build DI.
We’re proud to introduce our investors: OKX Ventures, Lingfeng, DraperDragon, W3 Storage Lab, DepinX, Central Pinnacle Technology Limited, and individual investors.
Our latest funding round closed at a $100M valuation.
We believe everyone should have access to a team of financial AI agents that helps them explore ideas, challenge assumptions, and make sense of the markets.
That’s the future we’re building at DI: a user-owned AI financial agent network for U.S. stocks and crypto.
First up: Event Engine, launching soon.
Bring a market question. Our specialist agents will explore what could happen next, where they agree, where they disagree, and why.
Thank you to our investors and community for building with us.

The AI industry has reached a definitive tipping point in 2026. The focus has shifted from CapEx-driven training to OpEx-driven inference. For the first time, AI IaaS inference spend ($2.33bn) has surpassed training spend ($1.9bn). The commercial era is here.
𝗠𝗮𝗿𝗸𝗲𝘁𝘀:
• Scale: Google APIs now process ~32bn tokens per minute.
• Capital: Mega-rounds are flowing into inference platforms and chips (Fireworks AI: $17.5bn; fal: $16bn; Modal: $15.75bn; Etched: $21bn).
• The ROI Catch: Margins are squeezed by hardware depreciation and energy costs. Can marginal revenue actually cover compute costs?
𝗦𝘁𝗿𝘂𝗰𝘁𝘂𝗿𝗮𝗹 𝗕𝗼𝘁𝘁𝗹𝗲𝗻𝗲𝗰𝗸𝘀:
1️⃣ Physical (Power): Compute is now constrained by power, not silicon. With racks drawing 40–120kW, grids are failing. ~7GW of U.S. data-center capacity was delayed this year alone due to power constraints.
2️⃣ Architectural (Memory Wall): LLM inference is profoundly memory-bandwidth-bound. Despite their reliance on expensive HBM, general-purpose GPUs often run at <30% utilization on specific workloads. This is a massive structural mismatch between cost and effective output.
3️⃣ Algorithmic (Inference Paradox): Serial token generation clashes with parallel GPUs. As agentic AI drives multi-step workflows, a paradox emerges: unit token costs fall (~47% QoQ), yet aggregate enterprise AI bills continue to soar.

𝗧𝗿𝗲𝗻𝗱𝘀: “Intelligence per Watt/Dollar”
To survive, the industry is abandoning raw compute hoarding in favor of surgical efficiency. We are tracking structural breakthroughs across three layers:
• Algorithmic: Bypassing serial bottlenecks—for example, by applying diffusion models to discrete modalities (text/code) to enable parallel token generation and dramatically boost GPU utility.
• Hardware: Moving beyond HBM—for example, through bespoke silicon using stacked DRAM (such as Qualcomm’s HBC) to deliver higher bandwidth at lower power consumption, alongside edge SLM chips.
• System Layer:
-Routing: Middleware dynamically routes queries to low-cost edge SLMs or powerful cloud LLMs based on task complexity.
-Decentralization: Orchestrating global edge nodes and stranded power to bypass centralized grid constraints and enable elastic pricing.
The 2026 AI inference moat is not GPU hoarding; it is granular cost control. Long-term winners will structurally compress the unit cost of output through algorithmic parallelization, memory innovation, or distributed orchestration.
3
575
Moca Network and @OKX_Ventures have formed a strategic partnership to accelerate identity-driven applications, including agentic identity and agentic commerce use cases, across the Moca Network ecosystem.
We will identify and support high-potential projects building practical consumer applications and meaningful use cases for people and AI agents with Moca Network’s digital identity infrastructure, including AIR Kit and Moca Chain. OKX Ventures will allocate a portion of its MOCA Coin (MOCA) reserves for co-investment opportunities identified through the partnership, with potential additional follow-on investment as projects mature.
Selected teams may also gain access to OKX’s global platform and infrastructure—including payment and on-ramp services, OKX Wallet integration, and other ecosystem resources—to help reduce friction for developers and users and support global growth.
Build the next generation of identity-driven and agentic applications with us.
Read the announcement: okxventures.medium.com/moca-…
Learn more about OKX Ventures: okx.com/ventures
#MocaNetwork #OKXVentures #DigitalIdentity #AgenticIdentity #AgenticCommerce #AIRKit #MocaChain

Weekly Crypto Brief is live 📊
Market insights. Key trends. Strong signals.
All in one place — everything that shaped last week in crypto.
Dive into the poster👇

OKX Ventures retweeted
To all European crypto users navigating these changes: OKX Europe is here to serve you. 🇪🇺
We’re committed to providing a regulated platform with deep liquidity, competitive pricing, strong customer protection, and a comprehensive suite of trading and financial products.
OKX Europe offers access to EUR on- and off-ramps, spot trading, crypto and equity X-Perps, tokenized stocks, staking, OKX Pay, OKX Card, and much more under the applicable MiCA, MiFID, and PI regulatory frameworks.
Our Unified Trading Account also brings spot, margin, and derivatives together, improving capital efficiency and enabling more sophisticated trading strategies.
One regulated platform. Global liquidity. More products. Better trading experiences.
We’re here for the long term, and we’re ready to welcome you. 🇪🇺
Risk warning: Crypto is volatile. You can lose everything you invest in. OKX Europe Ltd, authorised by the MFSA.

Binance France to Close Customer Accounts on December 31, Introduce Monthly Fees From November 29
According to Cryptoast, Binance France will close its customer accounts on December 31, 2026, after failing to obtain authorization under the EU's MiCA framework. Deposits have already been suspended. Citing a Binance customer email, Cryptoast reported that accounts still holding assets will incur a monthly management fee of 0.025%, with a minimum charge of 10 USDC, starting November 29. Crypto assets not withdrawn by December 31 may be converted, transferred, or otherwise handled under the Terms of Service. The closures apply to accounts held with the Binance France entity and do not mean Binance's global platform is closing all French users' accounts.


On November 3, the CFTC announced that single-stock perpetual futures, or equity perps, had been deemed approved under the existing security futures framework for trading on eligible U.S. exchanges. Kalshi followed with its first four stock perps. ICE had already announced a partnership with Trade[XYZ] to build a regulated U.S. perpetual futures market on Hyperliquid.
The U.S. has tried single-stock futures before. OneChicago began offering them in 2002 and traded roughly 7.4 million contracts in 2019. In an analysis submitted to the SEC, the exchange reported an average notional trade size of about $780,000 for 2018–2019. Its STARS products were used to replicate securities lending and equity repo transactions. The business largely served institutional financing and balance-sheet needs, but never developed a broad retail market. OneChicago closed in 2020. The 20% minimum margin requirement also constrained its capital efficiency; regulators lowered the floor to 15% only after the exchange had shut down.
More than two decades later, several conditions have changed. Perpetuals remove scheduled contract rolls, trading platforms have stronger retail distribution, and onchain markets have established demand. A November 4 snapshot showed roughly $4.57 billion in HIP-3 open interest on Hyperliquid, including $2.27 billion in stock perps. Trade[XYZ] accounted for about 97% of total HIP-3 open interest. Multiple deployers can use the same infrastructure, yet trading and positions remain highly concentrated. Lower barriers to launching markets have not erased the advantages of established distribution and liquidity.
The U.S. market has also become more competitive. CME launched single-stock futures in July across 55 stocks, with Micro contracts available on 22 of them and trading for nearly 23 hours a day. Kalshi’s first four names, McDonald’s, Costco, Qualcomm and Amgen, were all already available at CME. In CME’s review of Nvidia’s August earnings release, more than half of the September standard contract’s volume that day traded in the hour after the U.S. cash close. Dated futures are already capturing event-driven trading outside regular stock-market hours.
Perpetuals eliminate the need to roll at expiration, but funding payments introduce a variable cost of carrying a position. Short-term traders may care more about execution and leverage than funding. Over longer holding periods, accumulated funding costs can weaken the economics relative to financed stock positions or dated futures. The minimum customer margin for an unhedged security futures position is 15%, while Kalshi’s initial stock perps offer up to about 4.9x leverage. U.S. venues have less room to compete on leverage than many offshore platforms, putting more weight on trading costs and margin efficiency.
U.S. regulated venues and existing offshore onchain markets operate under different access, margin and clearing arrangements. The same stock can trade across separate order books, requiring market makers to post collateral in each venue and arbitrage price differences between them. Hedging becomes harder when the underlying stock market is closed. Longer trading hours create more opportunities to trade, but market makers also need capital to absorb price gaps and liquidation-driven volatility. Those costs show up in spreads and available depth.
We expect early U.S. demand for equity perps to center on short-term directional trades and event-driven strategies, particularly in volatile stocks outside regular market hours. As more exchanges enter, competition will center on returns to market-making capital. Spread capture, net funding payments, and hedging and financing costs determine how much depth market makers are willing to provide. Contracts without sustained demand will struggle to offer competitive execution, even if they qualify for listing.
OneChicago leaves a commercial question that still applies: in a market with mature stock financing and derivatives products, what economic advantage can a new contract offer that keeps traders coming back? Perpetuals improve the trading experience, and onchain markets have shown that people want to trade them. The size of the U.S. market will depend on whether regulated venues can serve that demand at a competitive cost of capital.


At Devcon Mumbai today, @VitalikButerin laid out a broader vision for Ethereum, spanning formally verified operating systems, open silicon, user-controlled health data, private communications, and trustworthy AI. Meanwhile, @drakefjustin outlined an ambitious goal: completing Ethereum’s post-quantum and post-AI transition by the end of 2028.
As AI agents begin managing assets, accessing financial services, and executing transactions on our behalf, how do we independently verify that these systems behave as intended? And can the cryptography securing those actions hold up over time?
Quantum Computing Is Putting Pressure on Today's Cryptography
In March 2026, @GoogleQuantumAI published new estimates suggesting that breaking secp256k1, the elliptic-curve cryptography used by Ethereum accounts, could require as few as 1,200 logical qubits, substantially fewer than previously thought. Fault-tolerant quantum computers are still far from that capability, but Google has already set 2029 as its own deadline for migrating to post-quantum cryptography.
Ethereum has more to deal with than wallet signatures. Its execution layer relies on ECDSA, consensus uses BLS, and data availability involves KZG commitments. All three need to be addressed in a post-quantum transition.
The trade-offs are substantial. BLS signatures are just 96 bytes, while published leanXMSS designs range from roughly 2.4 KB to 3 KB, around 25–31 times larger. They also lack BLS's efficient native aggregation. Ethereum is therefore developing leanVM to aggregate signature verification through cryptographic proofs, keeping network and verification costs manageable.
The challenge comes down to cryptographic agility: replacing the underlying cryptography while keeping the network running and existing assets secure. Native account abstraction is intended to let wallets gradually migrate to new signature schemes, but changes to consensus cryptography still require network-wide coordination and hard forks.
Drake's 2028 target is more aggressive than the Ethereum Foundation's September roadmap, which aimed for full post-quantum protection across all three L1 layers by December 2029. Whether that timeline can be accelerated will depend on the pace of upcoming forks and client testing. Wallets and applications may take longer to migrate.
Why This Matters for Onchain Finance
Ethereum mainnet currently holds around $142–143B in stablecoins and $15.1B in tokenized RWAs, excluding stablecoins, according to @RWA_xyz. As more financial assets move toward onchain settlement, cryptographic migration has to account for live financial systems, custodians, and integrations with other networks.
Even if Ethereum L1 becomes quantum-resistant, wallets, bridges, and custody infrastructure still relying on legacy signatures could remain exposed.
Migration also raises a harder question around property rights. What happens to dormant accounts whose owners can no longer be reached? Should the network stop accepting legacy signatures to prevent future theft, or preserve existing ownership rights even if those keys become vulnerable?
Coinbase's independent Quantum Advisory Council explored this debate in a June 2026 report. Although the report focused on Bitcoin, the tension between cryptographic migration and property rights applies to other public blockchains as well.
AI Extends the Trust Problem Beyond the Blockchain
A blockchain can verify that a transaction was signed by an authorized key and executed according to a smart contract's rules. It cannot determine whether an AI agent misunderstood a user's instructions, was manipulated by malicious web content, or made a financial decision based on unreliable external data.
As agents gain more authority over payments and asset management, the next challenge is establishing verifiable boundaries around what they can do. That includes spending limits, revocable permissions, execution records, and independent verification of external data and computation.
Formally verified software and open hardware could help reduce the trust assumptions in these systems, but much of that work needs to happen outside the blockchain itself.
Ethereum has an advantage in that it already supports a substantial amount of live financial activity while working to bring account abstraction, cryptographic proofs, and post-quantum security into a common protocol framework.
If it can complete this transition without disrupting settlement or weakening decentralization, the ability to upgrade its cryptographic foundations over time could become an important consideration for institutions choosing long-term settlement infrastructure.
Still, security standards are not exclusive to Ethereum. Google, Cloudflare, and other blockchain ecosystems are also pursuing post-quantum migration. Any claim to leadership will ultimately depend on what ships to mainnet, how well it holds up under security audits, and whether wallets and custodians actually adopt it.


Weekly Crypto Brief is live 📊
Market insights. Key trends. Strong signals.
All in one place — everything that shaped last week in crypto.
Dive into the poster👇

On October 27, @Morpho announced plans for its Midnight Adapter, which would let vaults allocate to fixed-rate, fixed-term markets.
Loans repay on a schedule, while investors may want their cash back sooner. Managers have to decide how much investors can withdraw and who will provide the money.
In the second quarter of 2026, @blackstone 's BCRED received roughly $4.5 billion in share repurchase requests, with $2.3 billion left unfulfilled. Quarterly repurchases are generally capped at 5% of outstanding shares, subject to board approval. Requests above the approved amount are filled pro rata.
To give investors cash before the loans mature, a product needs liquid reserves or buyers for its loan positions. A buyer pays now and waits for the borrower to repay. The return they require affects how much of the loan's interest depositors get to keep. @BirchHill_io is developing tokenized securities backed by U.S. loan pools, with plans to place them with longer-term investors.
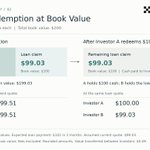
Consider a product that values a loan using its entry yield, with interest accruing over time. A buyer prices the remaining cash flows at the return they require today.
Take a claim expected to pay $102 in three months. Using simple annualized discounting, its book value at an 8% yield is $100. Assume repayment expectations and benchmark rates stay the same, but a buyer wants a 12% annualized return for tying up cash over those three months. They would pay $99.03. The 0.97% discount to book value is nearly half the claim's $2 in remaining interest.
If a vault lets investors redeem for $100 in cash while reserves last, those who withdraw early can avoid that discount. Cash redemption at book value gives depositors an option to sell early at that price. The further the market bid falls below book value, the more valuable that option becomes.
As the vault pays redemptions from cash, loans that have yet to mature make up a larger share of what remains. Once cash runs short, investors who withdraw later have to wait for repayments or find a buyer. When the market bid is below book value, cash withdrawals at book value let early withdrawers pass part of the exit discount to those who stay.

BCRED allocates repurchases pro rata, while withdrawal order determines access to cash in the hypothetical vault above.
In-kind redemption lets investors withdraw the underlying credit positions. Morpho's planned Midnight Adapter includes this option. After leaving the vault, investors can hold to maturity or look for a buyer. Getting cash early depends on executable bids for the amount they want to sell. Investors who want cash handle the sale themselves, reducing the vault's need to fund cash redemptions.
Money set aside for withdrawals can still earn a return. In April, @maplefinance said it would keep some assets in stablecoins and U.S. Treasury bills as a liquidity buffer. On October 29, its transparency page listed about $202 million under the “US Treasuries” category. If those assets earn less than the loans, the allocation affects how much interest depositors receive.
Suppose the loans earn 8% a year and the cash-like assets held for withdrawals earn 4%. Allocating 10% of the portfolio to the latter brings its annualized yield before fees down from 8% to 7.6%. The extra 40 basis points from investing it all in loans come from greater loan exposure, with no change in the loan terms.
The problem is comparing products on APY alone. With the same loan terms, a product that holds lower-yielding liquid assets reports a lower APY. One that leaves investors to sell their own positions can show a higher APY. If deposits follow that ranking, managers have an incentive to hold fewer liquid assets. In that comparison, the higher APY reflects less preparation for cash withdrawals.
With the same underlying loans, managers that fund early exits more cheaply, or attract capital willing to wait for repayment, have more income available to distribute.

OKX Ventures retweeted

Another major milestone for the OKXICE joint venture.
ICE and @tradexyz are advancing a new regulated, 24/7 market model for U.S. retail traders, with access through OKXICE.
One shared vision: financial markets that are more open, efficient, and accessible.

@Ondo launched 15 tokenized equities/ETFs and 11 @Uniswap v4 pools on Robinhood Chain.
This marks a structural shift in RWAs: from passive asset wrapping to active liquidity management and clearing infrastructure.
A quick breakdown:
THE FRICTION: WEEKEND LIQUIDITY VACUUMS
TradFi runs 5 days x 8 hours; crypto trades 24/7.
Robinhood supports 24/7 secondary transfers, but primary minting and redemption shut down over the weekend. Exogenous shocks can create supply-demand imbalances and depegging risks, with no direct TradFi arbitrage available to restore parity.
THE MECHANICS: UNI V4 AND CROSS-CHAIN ARB
Ondo deployed 11 paired pools (e.g., NVDAon <-> NVDArh), creating an arbitrage corridor:
• Dynamic Fee Hooks: Fees scale with price deviations, protecting LPs while preserving profit margins for arbitrageurs.
• Arb Path: Buy discounted RH tokens -> swap via Uni v4 -> bridge cross-chain -> redeem at parity through Ondo's 24/7 facility.
STRATEGIC PLAY: COLLATERAL AND ON-CHAIN PB
Beyond simple price exposure, this targets institutional rails, as Ian De Bode explained in a recent community interview:
• DeFi Collateral: Tokenized, cash-flow-generating equities and Treasuries can replace volatile crypto-native collateral, reducing cascading liquidation risk.
• On-Chain Prime Brokerage: Giving securities stablecoin-like velocity to enable cross-margin accounts, leverage, and automated smart portfolios.
ARCHITECTURE AND TRACTION
• RFQ Model: Orders route directly to traditional broker liquidity, eliminating the capital drag of pre-funded, passive DEX pools.
• Bankruptcy Segregation: Assets are held under security-interest structures with third-party verification.
• Traction: ~$1.3B in TVL for tokenized equities/ETFs (platform TVL: >$4B).
FOLLOW-UPS
• Tail-Risk Liquidity: Still untested during severe, sustained weekend market crashes.
• Bridge Friction: Latency and gas fees can erode arb margins and delay price convergence.
• Settlement Bounds: Secondary trading runs 24/7, but physical clearing remains bound to TradFi hours. The framework is offshore-only and excludes U.S. investors.
Ondo isn't erasing TradFi market hours. It's engineering an on-chain liquidity router around them.
The real moat for tokenized securities isn't asset wrapping. It's becoming the core clearing and collateral layer for decentralized finance.
178
Weekly Crypto Brief is live 📊
Market insights. Key trends. Strong signals.
All in one place — everything that shaped last week in crypto.
Dive into the poster👇

5
5
2,634
According to CoinGecko’s Q3 2026 Crypto Industry Report, total crypto market capitalization rose 39.6% quarter over quarter, increasing by $840.1 billion to approximately $3 trillion. This ended three consecutive quarters of decline and marked the largest quarterly gain since Q4 2024. However, total market capitalization remained down roughly 4% year to date.
Among major assets, ETH gained 71% during the quarter to $2,684, significantly outperforming BTC and other leading crypto assets. Spot ETH ETFs recorded $3.1 billion in net inflows over the quarter. Meanwhile, Hyperliquid (HYPE) reached an all-time high of $98 on September 23, supported by favorable U.S. regulatory developments, gaining 40.5% over four days.
Trading activity, however, did not recover in tandem. Average daily market-wide trading volume declined 8.6% quarter over quarter to $73.3 billion, while spot trading volume across the top 10 CEXs fell 14.2% to $1.65 trillion. At the same time, CEX perpetual futures open interest rose 40.6% quarter over quarter, surpassing $100 billion again by quarter-end.
Source: coingecko.com/research/publi…
View:
This rebound appears more like a valuation re-rating driven by improved expectations for macro liquidity, ETF inflows, and a recovery in risk appetite than a broad-based recovery led by spot demand. While total market capitalization rebounded rapidly, spot volumes continued to weaken, suggesting that capital has not yet been sufficiently distributed across the market and that a gap remains between price performance and broader market participation.
ETH’s relative strength is particularly noteworthy. Continued net inflows into spot ETH ETFs suggest that institutional investors are gradually moving beyond single-asset BTC allocations toward infrastructure assets with broader application-layer utility, asset issuance potential, and on-chain economic value capture. Whether ETH can sustain this strength will depend on the persistence of ETF inflows, a recovery in on-chain activity, and whether sectors such as DeFi, stablecoins, and RWA can translate asset-price gains into genuine usage demand.
Meanwhile, the combination of declining spot volumes and sharply rising perpetual futures open interest indicates that the market’s upside has been driven more by leverage and derivatives positioning. This increases short-term price sensitivity while also amplifying volatility and liquidation risks. Going forward, key indicators to watch include a recovery in spot volumes, the continuation of stablecoin supply growth and ETF net inflows, and whether capital can broaden beyond leading assets into projects with tangible cash flows, user growth, or infrastructure-driven value capture.

5
5
2,185