

Founder @ Vision Capital Fund. Investor, author, angel. Invest in companies that reflect our best vision for our future. Musings on investing, business & life.
Singapore 🇸🇬 | Global 🌏
Joined October 2017
- Tweets26.1K
- Following1.8K
- Followers28.8K
- Likes42.9K
Pinned Tweet
I am thrilled to announce the launch of Vision Capital Fund, which has been in the making for over seven years.
We are focused on growing wealth for generations by delivering outstanding long-term investment returns from investing in exceptional companies that best reflect our vision for our future.
Website: visioncapitalfund.co/
Press Release: tinyurl.com/VCFpressrelease
Day One Investor Letter: tinyurl.com/VCFDayOne


Mastercard $MA 3Q26 Earnings
- Rev $9.8b +14% ↗️🟡
- NG EBIT $5.9b +15% ↗️🟢 margin 60.5% +73 bps ✅
- EBIT $5.9b +16% ↗️🟢 margin 59.8% +94 bps ✅
- NG Net Inc $4.7b +17% ↗️🟢 margin 47.4% +140 bps ✅
- Net Inc $4.6b +18% ↗️🟢 margin 47.2% +154 bps ✅
- OCF $5.1b -10% ↘️🔴 margin 51.9% -1396 bps ↘️🔴
- FCF $4.8b -10% ↘️🔴 margin 48.5% -1313 bps ↘️🔴
GDV by Type and Geography
- GDV $3T +7% ↗️🟡
- GDV (Credit) $1.6T +7% ↗️🟡
- GDV (Debit/Prepaid) $1.4T +7% ↗️🟡
- GDV (US) $867b +6% ↗️🟡
- GDV (US - Credit) $400b +1% ➡️🟠
- GDV (US - Debit/Prepaid) $467b +10% ↗️🟡
- GDV (ROW) $2.1T +8% ↗️🟡
- GDV (ROW - Credit) $1.2T +9% ↗️🟡
- GDV (ROW - Debit/Prepaid) $848b +6% ↗️🟡
Biz Metrics
- Switched Txn $49.3m +9% ↗️🟡
- Total Cards 3.8b +5% ↗️🟡
- MA Cards 3.5b +7% ↗️🟡
- Maestro Cards 269m -17% ↘️🔴
- Pymt Network Rev $5.7b +11% ↗️🟡
- VAS Rev $4.1b +19% ↗️🟢
Assessments by Type
- Domestic 3.2b +14% ↗️🟡
- Cross-Border$3.8b +16% ↗️🟢
- Txn Processing 4.8b +14% ↗️🟡
- Other 285m +12% ↗️🟡
Switched Volume
- US +9% ↗️🟡
- WW ex-US +7% ↗️🟡
- Txn +9% ↗️🟡
- XB +11% ↗️🟡
- XB (Intra-Europe) +10% ↗️🟡
- XB (Other) +12% ↗️🟡
- ХВ CNP ex travel +15% ↗️🟢
- XB Travel (CP + CNP travel) +8% ↗️🟡
1 | Strong quarter despite economic and geopolitical uncertainty.
Three quarters into the year, our performance continues to demonstrate the strength and consistency of our business. Net revenue growth was up 14%, and net income up 18% in the third quarter on a year-over-year non-GAAP currency-neutral basis. While there continues to be economic and geopolitical uncertainty, consumers continue to spend, businesses continue to invest and commerce continues to expand. The economy, our overall business and our network have a resilient backdrop.
2 | VAS continues to grow faster than payment network revenues.
Payment network net revenue increased 11%, primarily driven by domestic and cross-border transaction volume growth as well as pricing. It also includes growth in rebates and incentives. Value-added services and solutions net revenue increased 19%. This includes a minimal impact from acquisitions and dispositions and now reflects the contributions from BVNK.
3 | Switch volume and transaction matrix remain strong. Intra-Europe was down sequentially due to new EU customs fees.
Starting with Q3, switched volume and transaction metrics are generally in line with Q2 and remained strong. Of note, the sequential increase in the U.S. switched volume was primarily due to recent commercial wins.
Looking at cross-border. First, lower-yielding intra-Europe volumes were down sequentially from Q2 to Q3, driven by the impacts related to a new customs fee in the EU, timing of large retail promotional events and lower crypto purchases in the quarter compared to last year.
4 | Mastercard now has over 200 million accepted locations and 300 million more digital access points globally.
At its core, our network helps people and businesses transact and participate in the economy, and our advantage here is clear: a diversified business, a trusted global network and the ability to help our customers grow. We're building on that advantage by expanding the reach and utility of our network. We now have more than 200 million acceptance locations and 300 million more digital access points around the world. That is unmatched.
5 | Affluent spend is growing twice as fast as overall credit.
This year, we have already won 100 new affluent credit and debit programs and launched more than 25 World Legend programs. Mastercard affluent portfolios have higher engagement and higher cross-border spend. In fact, our affluent spend is growing 2x faster than overall credit. This quarter, UBS launched a super-premium invitation-only Mastercard credit product in Switzerland's highly competitive affluent market. It includes our concierge service and frequent traveler benefits.
6 | Partnering with MrBeast on the marketing front for Mastercard.
That focus on meeting new people where they are led to our new partnership and co-brand program with Beast Industries. This program spans consumer and small business creator cards. With more than 1 billion followers across social media, MrBeast is one of the most influential creators in the world. But that work is not just about clicks. It's capturing the cultural power of digital communities and driving economic and social opportunity. Together, we will connect creators and their communities in new ways, bringing Mastercard scale and capabilities to the next generation as their financial lives evolve.
7 | Signed numerous partnerships this quarter.
In the Nordics, we renewed our partnerships with Handelsbanken and Swedbank, following a previously signed exclusive agreement with SEB…At the same time, we renewed DSGV and DZ Bank, 2 of Germany's largest banking organizations.
This includes new programs with China's top 15 issuers. This quarter, we added to that with the new World Hilton co-brand with Bank of Communications and a consumer debit deal with Bank of China, who alone serves hundreds of millions of retail customers.
In the United States, we secured a major win with Pinnacle Financial Partners. The newly combined bank's entire issuing portfolio will move onto our network starting in 2027.
This quarter, we signed an important small business deal with HDFC Bank. It's India's largest private sector bank with nearly 10,000 branches, over 100 million customers. This deal includes value-add services and solutions and is expected to add 3 million cards to the Mastercard network.
8 | Consumers are starting to use agents to discover and purchase products. That trend should continue to build. While growth is rapid off a small base, it is still early days and it is still insignificant for now.
Consumers are already beginning to use agents to discover and purchase products. We expect that trend to build as holiday shopping ramps up and to continue well beyond the season. It is still early days, and the numbers are not yet significant in the grand scheme. But as the AI agentic assistants have emerged, agentic transactions are ramping up at impressive weekly growth rates. We're now seeing the early stages of consumer adoption. For this type of agentic commerce to function at scale, we need 4 things: trust in the payment, the agent, the ecosystem and ubiquitous reach. Mastercard has built capabilities for each of these 4.
9 | Tokenization is embedded in Agent Pay.
For trust in the payment, tokenization is embedded in Agent Pay and backed by the franchise rules everyone expects today. For trust in the agent, Agent Pay ensures agents are verified and authorized by the buyer, that the merchant and issuer are aware. For trust in the ecosystem, we bring transparency and continuity through the payment flow. Verifiable Intent captures the buyer intent, and our recently launched Agentic Trust Intelligence solution helps banks and merchants evaluate transactions initiated by any AI agent. And that allows these transactions to occur wherever Mastercard is accepted.
10 | Shopify’s Shop Pay and OpenAI is partnering with Mastercard Agent Pay..
At the same time, we are helping merchants ready themselves and be more discoverable to agents with our new Agent Connect solution. Many partners are putting all of this into practice. For example, Shopify, through Shop Pay, is using Agent Pay and our network tokens to make agentic payments more secure and seamless by preserving the integrity of the consumer's credential end-to-end. Shop Pay is already available on multiple agentic platforms with more to follow. And with OpenAI this quarter, we signed a broad strategic partnership that includes the use of Agent Pay and goes well beyond.
11 | Mastercard is becoming the payment rails for stablecoins.
Through BVNK, we are expanding the infrastructure that connects stablecoins with traditional payment and money movement experiences. Financial institutions and fintechs today struggle to offer both fiat and stablecoin accounts, creating the risk of customer deposits moving to competing stablecoin accounts.
Our first combined Mastercard BVNK product is the Mastercard Global Money Platform, enables financial institutions and fintechs to offer accounts where customers can hold, convert, send and receive across fiat currencies and stablecoins. Mastercard Move is also integrated, bringing its 17 billion endpoints to the platform. This enables businesses to pay out stablecoin balances directly into recipients' local bank accounts. Nuvei and Marqeta will be among the first customers to integrate the platform, with more partners to be announced soon. And all of this is complementary to our existing stablecoin offerings such as crypto co-brands and stablecoin settlement.
12 | Expecting high-end of low double-digit revenue growth for 4Q26 and FY26.
As it relates to our expectations for the fourth quarter of 2026, YoY net revenue growth is expected to be at the high end of low double digits range on a currency-neutral basis, excluding inorganic activity…From an operating expense standpoint, we expect Q4 growth to be at the high end of low double digits range versus a year ago, again, on a currency-neutral basis, excluding inorganic activity.
For the full year 2026, we expect net revenue growth to remain at the high end of low double digits range on a currency-neutral basis, excluding inorganic activity. We also expect full year operating expenses growth to remain in line with previous expectations at a low double digits range versus a year ago on a currency-neutral basis, excluding inorganic activity.
13 | There is currently a lot of patchwork payment solutions for agentic commerce.
So there's a lot of patchwork going on right now, and I wouldn't call that solutions. It's kind of patching towards what is the golden goal here, and the golden goal I just listed is, you have a protected transaction that works in the same way as consumers are used to and merchants are used to. So one of the things that need to happen before this to really take off is consumers need to feel comfortable. So use of Agent Pay and having registered agent is a key thing. And the other thing is merchants need to be actually discoverable because then the other side of the transaction isn't really working.
14 | Mastercard is not supporting VCN as a solution in between.
What we're not supporting is VCN as a solution in between. That is not the consumer scenario that actually you asked. You said, "If you put your card somewhere into an agent as an agent-first solution or whatever it is," consumers do what they do, and it's their choice, and we try to give them many choices to choose Mastercard.
A VCN is a processor decision that is a bridge to get ready for a fully tokenized transaction all the way through for a period of time. We are cognizant that this ecosystem needs to get there, no question about it, but that's not a long-term solution that we will support.
15 | Mastercard believes that fully tokenized all the way through Agent Pay is the way to tackle digital/agentic commerce, and wants to be the new payment rules for that.
It is in everybody's best interest to use Agent Pay and equivalent. We are not supporting solutions that take a onetime VCNs out there as fronting a transaction. That fundamentally breaks a transaction that is important from a consumer perspective. They made a choice. It's important from a rewards perspective, from a control perspective, and so forth.
So I think we're at this turning point where everybody is pushing in the same direction. We are very clear that fully tokenized all the way through agentic pay or an equivalent is the way to go. If we get this all right, it will truly be the next evolution of digital commerce.
16 | Don't think agentic commerce is going to be the only mode of commerce. Commerce will be multimodal, and Mastercard has to be versatile to maybe be able to support different modes, whether it's in person, online, or agentic.
There's room for new services in cyber, in a new world of agentic or the evolution towards that. And by the way, I don't think agentic is going to be the only mode of commerce. It is going to be multimodal. So therefore, we have to be versatile and cut across all these different modes, whether it's in-person transactions, online and agentic down the road. They can all coexist. And that speaks to the versatility of the network, and our services can apply across the board
17 | Mastercard's flywheel is to get volume, deliver services on the volume, and the services, in turn, become the differentiation that drives even more volume.
we use rebates and incentives to drive volume and transaction onto the network. I'm just going to reiterate my flywheel point. You get the volume, then we deliver services on the volume, and then the services in turn become the differentiation that will drive even more volume. So we'll continue to do that. And we have been winning -- we have been winning deals and -- with new customers and expanding our customers in terms of our deal base.
18 | Mastercard continues to be very disciplined in terms of what, how, and what deals they want to win, and what deals they will walk away from.
And -- but we've been very disciplined. We've been very disciplined and -- in terms of how -- what deals we want to win, what deals we want to walk away. We're not just going to win every deal, and we're not going to do that. We don't want to do that.
We're going to win deals that gives us a higher growth momentum that's accretive to the growth trajectory. We're going to win deals that are additive to the cross-border flows, and we're going to win deals that will allow us to deliver services as well. So the punchline is we'll use R&I as a tool to drive the growth momentum and the growth algorithm.
➡️ Final Thoughts on Mastercard $MA:
Long-term stable compounder of steady growth (>12%+) with VAS driving faster growth than payment network, and growing profitability strong operating leverage via slower expense growth, resulting in even faster earnings growth (~15%+), the toll-booth supporting the long-term secular tailwind of the war on cash, and winning across more verticals and rails supported by strategic accretive acquisitions. VAS remains very strong. Strong push into stablecoins and agentic commerce, wanting to be the new tollbooth of that.


ServiceNow $NOW 3Q26 Earnings
- Rev $4.1b +21% ↗️🟢
- NG GP $3.2b +15% ↗️🟢 margin 77.3% -357 bps ↘️🔴
- GP $2.9b +10% ↗️🟡 margin 70.5% -678 bps ↘️🔴
- NG EBIT $1338m +17% ↗️🟢 margin 32.6% -87 bps ↘️🔴
- EBIT $385m -33% ↘️🔴 margin 9.4% -741 bps ↘️🔴
- NG Net Inc $1.0b +5% ↗️🟡 margin 25.3% -381 bps ↘️🔴
- Net Inc $277m -45% ↘️🔴 margin 6.7% -799 bps ↘️🔴
- OCF $839m +3% ↗️🟡 margin 20.4% -343 bps ↘️🔴
- FCF $748m +29% ↗️🟢 margin 18.2% +125 bps ✅
Biz Metrics
- Sub Rev $4.0b +21% ↗️🟢
- RPO $29.7b +22% ↗️🟢
- cRPO $13.7b +21% ↗️🟢
- ncRPO $16.1b +23% ↗️🟢
- Cust with $5m+ ACV 680 +23% ↗️🟢
- Avg ACV of Customers with $5M+ ACV $15.4m +5% ↗️🟡
- 98% renewal rate ➡️🟢
- Net New ACV: 48% technology, 34% CRM, 18% creator
- Revenues: UCAN 63%. EMEA 25%. APAC 12%
Mgmt Guide 4Q26
- Sub Rev $4.255b +23% ↗️🟢
- cRPO +18.5% ↗️🟢
- NG EBIT Margin 32.0% ↗️🟢
Mgmt Guide FY26
- AI net new ACV $1.7b
- Sub Rev $15.785b +22.5% ↗️🟢 (raised smalls ✅)
- FCF margin 36% (+100bps from 35%) ↗️🟢
1 | Delivered another strong quarter, exceeding the high end of guidance across every top-line and profitability metric
We delivered another strong quarter, exceeding the high end of our guidance across every top line and profitability metric. Q3's results reinforce that ServiceNow is becoming even more strategic as enterprises move from experimenting with AI to deploying it at scale. Customers want the productivity and growth that come with super intelligence, but they also need the visibility and security to do so with confidence. With the ServiceNow AI platform at the operational core of the world's largest enterprises, we are perfectly positioned to help customers put AI to work across their business, govern every agent in action and translate intelligence into secure, measurable outcomes.
2 | Growth in subscription revenues will be slightly depressed as they are recorded in professional services initially before being recorded in subscription revenues later on.
With respect to why we didn't raise by the entire beat, there's a couple of things…. From an accounting perspective only, the value of those deployments are carved out as subscription revenue, and they're included in professional services rather than subscription revenue. Notably, upon renewal of those contracts, the value of those services return to subscription revenue. So it provides a structural acceleration to growth. And it's not huge, about 25 bps in Q3 and expecting it to have approximately 50 bps in Q4, which is the only reason why we didn't pass through the full beat in Q3 into the rest of the year. So subscription revenue, feel really, really strong about that.
3 | Control Tower Alliance and new AI Passport solution announced.
ServiceNow announced the Control Tower Alliance, a new ecosystem of leading companies in AI, cloud infrastructure, security, and governance, which will work with ServiceNow to help customers adopt trusted enterprise AI safely at scale. Founding members of the new program include Anthropic, Amazon Web Services (AWS), Cisco, HiddenLayer, Kong, NVIDIA, Okta, OpenAI, Stripe, WitnessAI, and Zenity.
ServiceNow announced a new AI Passport solution to verify first- and third-party AI agents’ scopes in real-time. New Super Intelligence Control Tower capabilities build on ServiceNow’s autonomous remediation and kill switch capabilities to drive end-to-end AI governance with discovery, visibility, control, measurement, and compliance on one unified platform.
4 | Strong partnerships announced for Super Intelligence Control Tower Is paving the way for ServiceNow's Control Tower to be the dominant one for enterprises to rely on.
Super Intelligence Control Tower is basically redesigning what the enterprise visibility, governance and security posture is of these major corporations. And if you look at the partnerships we announced today across the board and especially OpenAI, it's clear that the best and smartest companies in the world realize that this Control Tower and activating that across rules and rails that are deterministic and companies rely on to run their business is a pretty important thing to do to grow their businesses.
5 | ServiceNow is growing to become the governed execution layer for enterprise AI, raising the $1bn AI target to $1.7b.
Our ambition is to be the governed execution layer for enterprise AI with multiple commercialization paths, all driven by customer choice. Q3 is the banner achievement to date.
The strategy is working. We have tangible AI monetization. AI, net new ACV was 65% YoY growth in Q3. Control Tower, net new ACV grew over 6x YoY. Our agentic front door EmployeeWorks reached $100 million ACV in less than three quarters. The number of $1 million-plus AI deals grew 4.5x YoY. Year-to-date, agentic AI consumption in production is up 13x YoY…As a reminder, we began the year with a $1 billion AI target by year-end. We raised that target to $1.5 billion at Financial Analyst Day in May. Today, we are raising that target again this time to $1.7 billion plus by year-end. And as you've come to know me pretty well by now, I've challenged the team to even surpass that number.
6 | Enterprises are having growing gaps in AI visibility, being able to control AI agents is extremely important.
We're now in the rules and rails phase of enterprise intelligence. 94% of enterprises report gaps in AI visibility. 88% can't even distinguish personal AI accounts from corporate instances. ServiceNow's Control Tower discovers and inventories the entire AI estate. As stories of rogue agents persist, ServiceNow controls what agents can do. That's why we introduced AI Passport to issue every agent an official attested record based on context in our platform. Who owns the agent? What's it allowed to do? What data can it access? How much risk exposure is it allowed to take?
7 | Control Tower wants to become the most capable Q-switch for AI agents
This enables the most capable kill switch available in the enterprise today. When our Control Tower revokes a passport, NVIDIA Sentry stops honoring it and the agent stops at the infrastructure layer. We are scaling that capacity everywhere. Our Control Tower signals Okta, Microsoft Azure AI Foundry and Google Gemini enterprise agent platform, so they can cut off the agent's access wherever it runs.
8 | ServiceNow Control Tower Alliance It's a new alliance between Anthropic, AWS, Cisco, Okta, and OpenAI.
ServiceNow Control Tower Alliance is a new ecosystem of leading companies in AI, cloud infrastructure, security, governance and token management who will help customers adopt trusted enterprise AI safely at scale. Founding partners include Anthropic, AWS, Cisco, HiddenLayer, Kong, Okta, OpenAI, WitnessAI and Zenity.
9 | With Armis and Veza, ServiceNow can pinpoint specific known vulnerabilities, remediating and preventing them right away.
With Armis and Veza, we can now pinpoint specific known vulnerabilities against the cybersecurity landscape that has irreversibly changed. We call this Shift Zero. It moves security from remediation to prevention from human speed to machine speed and from blind to govern. The average enterprise runs more than 70 security tools. ServiceNow offers a single govern system with proof of what acted, why and who is accountable.
10 | ServiceNow wants to be the execution layer for the entire AI economy. Action Fabric is going rapidly, and think that it will be substantially larger.
ServiceNow basically is the execution layer. And I believe we're the execution layer for the entire AI economy. And if you look at what's happening with the partnerships we announced today and many more to come, it's not just where the work gets done, but it's where every human and every agent in the enterprise is coming to get things done. And that's a large market. We're positioned at the center of it.
And if you say, well, how should we know? Just keep in mind that Action Fabric has seen a 500% growth in assists in less than 30 days. So it's multiplying so, so quickly. And I think this represents a business model innovation that will be substantially larger in a very short period of time than the entirety of ServiceNow is today.
11 | Over 100 customers are actively innovating with ServiceNow's AI specialists.
Our Level 1 service desk specialist resolves incidents 85% faster than human agents. This is now in full autonomous production across customers of varying size and sector from a global automotive leader to a leading enterprise technology company. Our AIOps specialist has already reduced median time to resolution by 40% within the first month. We now have over 100 customers actively innovating with our AI specialists, AIOps, HRSD and CRM specialists are expected to become generally available in Q4.
12 | Raising full-year guidance will take the company from a rule of 57 to a rule of 60
We're not compute constrained. We don't have capital constraints. We're activating a hybrid business model. As you'll hear in the raised full year guidance, we're a company going from the Rule of 56 to the Rule of 57 on our way to the Rule of 60. That, of course, is free cash flow plus revenue growth.
13 | The traction in AI is exploding for ServiceNow
In Q3, the number of AI deals over $1 million grew 4.5x YoY. We're also seeing customers embrace AI more broadly across their enterprises with deals spanning five or more AI products increasing over 8.5x year-over-year. AI adoption is pervasive across the platform, evident in every workflow. ITSM AI deal volume increased nearly 80% year-over-year. HRSD AI deal volume nearly doubled.
Newer AI solutions saw deal volume grow even faster with ITOM growing more than 7x and portfolio management more than 6.5x. We also saw strong net new ACV momentum with security and risk AI growing more than 4.5x YoY. App Engine AI more than 4x and Asset Management AI nearly tripling. As Bill mentioned, our year-to-date consumption of agentic AI in production is up more than 13x YoY.
14 | Strong path and trajectory for the AI business to be 30% of ACV.
'll just take you back to Financial Analyst Day, Adam, when we talked about by 2030, our AI business would be 30% of our ACV. And so we're absolutely on path and trajectory to get there, if not actually ahead of schedule, as you can tell by our continued raise of AI, but we are well on our path.
15 | AI has been phenomenal for ServiceNow, allowing them to generate $1 billion in efficiency gains through their own internal use of AI.
so excited to say that we've crossed $1 billion in efficiency gains through our own internal use of AI and the lion's share of that is coming from our own use of our own products Now on Now. So it's just incredible. And yes, that efficiency gains means that we're able to not hire as many people. That being said, we're absolutely hiring folks in the right spots.
And so while you might see total sales and marketing headcount come down, actually quota-bearing heads are up double digits, while sales operations, for example, is down significantly. And very similar in the R&D organization. As you would imagine, real increases in AI engineers in top talent, but there's lots of efficiency gains that we're driving through AI.
16 | ServiceNow has been using AI implementation agents to help customers go live.
We're also building -- using AI implementation agents. So what -- when we help our customers go live, a lot of the heavy lifting is done by AI. This is really identifying the early use cases and make it simple for them to go live with it. And once they get 1 or 2 of these live, then the volume goes up very quickly. So this is not a long-term engagement. It's very short, but we get that value quickly for customers.
17 | Forward-deployed engineers are helping customers realize value faster.
We're passionate about helping customers realize value faster. With the help of our forward deployed engineers, we've seen an accelerated time to value of 80% year-to-date. For example, one European customer went live in just 12 weeks and is on track to consume nearly 1.5 million in annual assists. When we provide deployment expertise as we've seen AI adoption move twice as fast in just the first five weeks of involvement.
18 | It will be a small, modest uphill headwind in cRPO that does not impact revenue in the long term of about 50bps in Q4.
The other thing is those incremental investments in deployment expertise, a small modest RPO headwind also does not impact revenue in the long term. And just more generally, I'd note, and we've talked about this before, right, cRPO is a very nuanced accounting metric, and it doesn't necessarily capture all of the momentum in the business.
A good example for that is there's approximately 50 basis points of year-over-year subscription backlog growth that's excluded from cRPO in Q4 due to T4C provisions, but absolutely will be included in revenue. And so while cRPO is a good indicator of next year's revenue, it's certainly not perfect. And the momentum you're hearing in the business, especially around all of the AI amazing things will absolutely translate to strong revenue growth in 2027 and beyond.
➡️ Final Thoughts on ServiceNow $NOW
The market looks to be overly pessimistic that AI will disrupt it, when the models are actually partnering with it. Its strong revenue growth posits it to be a beneficiary of AI, rather than one who is being disrupted. Solid, stable business, highly recurring revenues with a very long organic growth trajectory (~20%+ FXN) and very profitable (~FCF 30%+ margins) run by very solid management and execution. Continue to be well poised to benefit with secular and continued enterprise transformation and productivity gains with agentic AI workflows with their infrastructure/architecture moat of data connectors, and looks well positioned to dominate in AI control tower, and increasingly in end-to-end security.


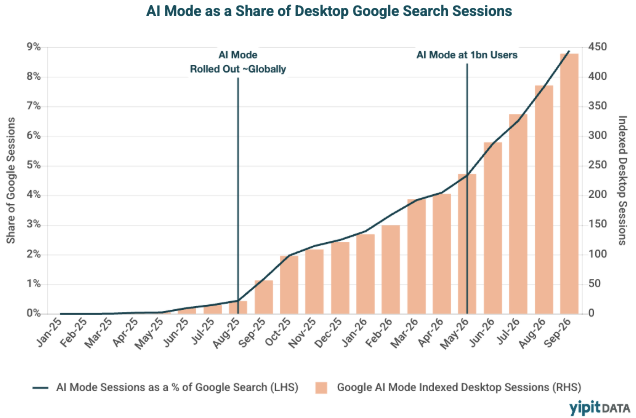
Google AI Mode continues to grow its share of Desktop Google Search sessions, reaching 8.9%.


Alphabet $GOOGL 3Q26 Earnings
- Rev $127.6b +25% ↗️🟢
- GP $76.2b +25% ↗️🟢 margin 59.7% +12 bps ✅
- EBIT $40.6b +30% ↗️🟢 margin 31.8% +129 bps ✅
- Net Inc $26.5b -24% ↘️🔴 margin 20.7% -1343 bps ↘️🔴
- OCF $42.3b -13% ↘️🔴 margin 33.1% -1416 bps ↘️🔴
- Capex $51.4b +114% ↗️🟢
- FCF -$9.1b ↘️🔴 margin -7.1% -3101 bps ↘️🔴
Revenue by Segment
- Google Services $96.3b +11% ↗️🟡
- Google Advertising $82b +11% ↗️🟡
- Google Search $63.4b +12% ↗️🟡
- YouTube Ads $11.2b +9% ↗️🟡
- Google Network $7.5b +1% ➡️🟠
- Google Subscriptions $14.3b +11% ↗️🟡
- Google Cloud $30.7b +103% ⤴️🟢
- Other Bets $0.4b +8% ↗️🟡
Google Services
- Rev $96.3b +11% ↗️🟡
- EBIT $39.2b +16.8% ↗️🟢 margin 40.7% +215 bps ✅
Google Cloud
- Rev $30.7b +103% ⤴️🟢
- EBIT $11.1b +209.4% ⤴️🟢 margin 36.2% +1250 bps ✅
- Backlog $561bn +256% ↗️🚀
Other Bets
- Rev $372m +8% ↗️🟡
- EBIT -$2b ↘️🔴 margin -550.3% -13573 bps ↘️🔴
Revenue by Geography
- US $67.7b +39% ↗️🟢
- EMEA $32.7b +9% ↗️🟡
- APAC $19.9b +12% ↗️🟡
- Other Americas $7.1b +17% ↗️🟢
1 | Revenues grew 25% and are now at a $500 billion ARR. Continues to have strong momentum, and AI investments are increasing usage and overall query growth.
Alphabet revenues grew 25% YoY. We are now at $0.5 trillion annual run rate. That's remarkable growth. Search has strong momentum. Our AI investments are driving increased usage and overall query growth, including commercial queries. In fact, our YoY query growth rate is the highest it's been in the last 5 years.
2 | Core Google revenues continued to grow fairly strongly, across advertising, search, YouTube, and subscriptions.
Google Services revenues increased 11% to $96.3 billion, reflecting strong growth in Search and subscriptions. Total advertising revenues were up 11% with growth across all major verticals….Google Search and other advertising revenues increased by 12% to $63.3 billion, with retail driving the largest contribution followed by finance. YouTube advertising revenues increased 9% to $11.2 billion, with brand driving the largest contribution and notable strength in living room. Network advertising revenues of $7.5 billion were up 1%. Subscription, platforms and devices revenues increased 11% this quarter to $14.3 billion, driven by strong growth in YouTube subscriptions, particularly in YouTube Music and Premium and strong demand for AI plans in Google One.
3 | Noise in slower growth of search/advertising revenues from FX, APAC advertisers Impacted by the EU eliminating its diminutives exemption and ad spend normalizing after a strong Q2 driven by the FIFA World Cup, and lower monetization of AI mode.
Search grew 12% YoY to $63 billion. And when you look at the change in growth rate from Q2 to Q3, there were a few drivers here. So first, there was FX. It was the single largest driver of Search deceleration relative to Q2. Second, there were vertical-specific dynamics.
In retail, some of our APAC advertisers were impacted by the EU eliminating its de minimis exemption. In media and entertainment, spend normalized after an unseasonably strong Q2, driven by the FIFA World Cup, which had more matches and therefore, more advertising budgets allocated in June than actually in July. It's also -- to the next part of your question, it's worth noting that the strong growth in AI Mode queries had an impact because of the lower monetization we were seeing in AI Mode. To be clear, we feel very good about our trajectory here. Our ad experiments have shown promising results, and we're now scaling ads within both AI Overviews and AI Mode to more users and more queries, including, as I mentioned, international markets and multiturn ads in the U.S.
4 | Higher costs due to TPU sales increase in depreciation, content acquisition cost, and technical infrastructure operation cost, and an $8.2bn unrealized loss from SpaceX.
Other cost of revenues was $35.1 billion, up 32%, driven by hardware costs primarily related to the sales of TPU systems, increase in depreciation, content acquisition costs and technical infrastructure operations costs. Total operating expenses were up 20% to $35.6 billion.
Other income and expenses was negative $8.2 billion due primarily to unrealized loss from our investment in SpaceX from a decline in its stock price in the third quarter.
5 | Saw lower OCF due to the buildup of TPU inventory and the $5.2 billion cash fine.
We generated strong operating cash flow of $42.3 billion in the third quarter and $179.6 billion for the trailing 12 months. Operating cash flow was negatively impacted by the buildup of inventory for TPU system sales as well as a $5.2 billion cash payment for a 2018 EC fine following the conclusion of the appeal process.
6 | 2/3 of capex was for servers and networking equipment, and the remaining was for data centers.
CapEx was $51.4 billion in the third quarter with the vast majority of the spend in technical infrastructure to support our investments in AI. Approximately 65% of our investments in technical infrastructure in Q3 was related to servers and networking equipment, which generally have useful lives of 6 years. The remaining 35% was for data centers, which have useful lives of 7 to 40 years. We had negative free cash flow of $9.1 billion in the third quarter, driven by our investments in CapEx. Free cash flow in the third quarter was also affected by the aforementioned inventory build to support TPU system sales and payment of the EC fine.
7 | Google has maximum contractual obligations of $1,076bn, $924bn of future purchase commitments and $152b of other leases and obligations, most of which have some variable pricing and volume flexibility, which could result in a lower spend.
We have also entered into multiyear agreements to secure capacity for technical infrastructure and inventory as well as leases and energy. At the end of the third quarter, we had future purchase commitments of $924 billion and pre-commencement leases and other obligations of $152 billion. These dollar amounts reflect the maximum contractual obligations. However, a number of these agreements have variable pricing and volume flexibility, which could result in lower spend.
8 | GCP revenues grew 103%. Seeing strong customer demand for Google TPUs.
Google Cloud revenues grew 103%. Our AI infrastructure and solutions are the major drivers for Cloud growth and our customers see us as the leading provider here, so there's huge demand. We are working hard to bring more capacity online to meet this long-term demand. At the same time, we are seeing strong demand for our TPU systems across a wide range of customers, and we expect that to continue as we scale
9 | TPU system sales were a meaningful contributor, expected to scale in Q4, followed by a meaningful revenue ramp in 2027.
TPU system sales were also a meaningful contributor. GCP accounted for the vast majority of the revenue generated in Q3. The cloud revenue growth rate, excluding the impact of TPU systems, was again incredibly strong.
In Google Cloud, we expect TPU system sales to continue to scale in Q4, followed by a meaningful revenue ramp in 2027.
10 | Third-party bridging capacity only came online at the end of Q3 and had limited negative impact on margins. Expected negative impact to be larger from Q4 onwards, and more near-term as they pay up to get long-term customers.
The third-party bridging capacity, which we discussed on our prior call, came online only at the very end of Q3 and therefore, had limited negative impact to our margin in the quarter.
With respect to Cloud margins, given the supply constrained environment, we started utilizing third-party compute capacity at the end of Q3 and will ramp usage in Q4. We expect margin headwinds in the near term as we utilize this capacity.
11 | Google Cloud backlog is $561b up from $514b, expecting higher capex to match the growth in backlog.
Google Cloud's backlog was $561 billion in the third quarter, with the majority of the backlog related to typical GCP contracts.
Moving to investments. Our full year 2026 CapEx guidance range of $195 billion to $205 billion remain unchanged. We continue to expect our CapEx to increase significantly in 2027, and we'll provide further details on our Q4 call. In terms of expenses, the significant increase in our investment in technical infrastructure will continue to weigh on the P&L in the form of higher depreciation expenses and related data centers operation costs such as energy.
12 | Google expects to generate an attractive ROIC that is meaningfully higher than the cost of capital, which will result in growing OCF.
let me say a few words on how we think about return on invested capital and free cash flow. We're in a unique position to be able to monetize our AI investments across many products that reach billions of users and enterprises. Our AI investments in Search are driving our highest query growth in half a decade. Google Cloud has generated tens of billions of dollars in AI revenues year-to-date, and Google One is our fastest-growing subscription products, driven by demand for AI plans. Throughout this investment cycle, we expect to generate an attractive ROIC that remains meaningfully above our cost of capital and anticipate generating strong cash flow from operations
13 | Customers are using Google's AI models more than ever. 1P APIs are processing 32B tokens per minute, +40% QoQ. Google is back at the frontier.
On our AI models, customers are using our models more than ever. Our first-party model APIs are now processing nearly 32 billion tokens per minute, 40% more than last quarter and more than 4x what we processed a year ago. And with Gemini 4 Argon and now Carbon, which we announced today, we are excited to be leading at the frontier. The Gemini app is now at 1 billion users and is the fastest-growing product in Google's history.
14 | Saw strong demand for Argon, ramped 3.5x faster than Gemini 3. Using Argon internally and shipping 35% more code with 30% fewer errors.
Starting with AI, highlighted by our Gemini 4 series of frontier models. We are seeing strong demand and usage for Argon, which we launched 2 weeks ago. In fact, on our developer platforms, usage in the first week ramped up 3.5x faster than Gemini 3, even with capacity constraints. Argon is proving to do really well in areas like finance, legal, cybersecurity and science. Developers and cloud customers are already using it for things like untangling legacy code bases, accelerating scientific research, robotics, discovering product improvements and domain-specific tasks requiring in-depth reasoning. And at Google, just in the last few weeks, teams across Chrome, Ads and Search have used Argon to write and optimize code much faster, shipping 35% more code with 30% fewer errors. Argon is just the start of the Gemini 4 series.
15 | Carbon brings Google right back to the frontier for AI models.
Today, we announced Carbon. It's our strongest frontier model with state-of-the-art cybersecurity and long horizon capabilities. It ranks #1 on the recently updated artificial analysis intelligence Index at 59. Carbon outperforms Argon across almost every domain like full stack web development, multimodal understanding, complex knowledge work and scientific reasoning. We are rolling Carbon out first to a subset of trusted cyber defenders before we expand access, and it's being tested by the U.S. government.
16 | Genie 4 which simulates safe, realistic, interactive worlds with native audio in real time will be an important building block for training robots and agents.
Beyond our Gemini 4 series, yesterday, we announced Genie 4, our most advanced world model yet that simulates safe, realistic, interactive worlds with native audio in real time. This is an important building block for training robots and agents.
17 | Recursive self-improvement (RSI) is helping Google to increase their training and launch velocity for AI models.
This rapid progress underscores our incredible model momentum. We are at the point where AI is helping us increase our training and launch velocity. I would expect the next 12 months to see continued acceleration because of RSI. We have more models coming soon, including more efficient versions to help developers optimize for speed and cost and to deploy across our billions of users.
18 | Google Cloud now has 18 product lines with more than $1 billion in annual revenue. TPU sales were a meaningful contributor.
Google Cloud now has 18 product lines with more than $1 billion each in annual revenue. And our growth this quarter was driven by strong growth in Google Cloud Platform with strength in both AI and core GCP. TPU system sales were also a meaningful contributor.
19 | Google worked closely with Meta to deliver TorchTPU, allowing developers to port workloads easily from GPUs to TPUs.
To make it easy for developers to port workloads to TPUs, we recently worked closely with Meta to deliver TorchTPU, which allows users to train, serve and deploy PyTorch models on TPUs, using the tools they're already familiar with and rely on. Nearly 100 customers use TPUs today, and we're seeing strong and growing demand from many others.
20 | Google is seeing new customers, like Apple, capital market companies, universities, and public sector companies use TPUs. GCP recently entered into partnerships to deliver TPUs to Crux AI and Oracle.
In addition to our work with Anthropic, both directly and via Broadcom and public reference customers like Apple, who are scaling pretraining of their foundation models on the latest generation of TPUs, we're also working with new frontier model companies, including Mirendil and Physical Intelligence; capital markets firms, including Citadel Securities and Jump Trading; universities like Caltech; and public sector service providers, including Cassava and Cirrascale. Given continued strong and accelerating demand, we've recently entered into partnerships to deliver TPU systems with both Crux AI and Oracle, with more in the works.
21 | Google now has over 100 significant TPU customers across digital natives, AI labs, traditional enterprises, and financial and capital markets customers.
on the demand in Cloud, we are always managing our portfolio to ensure we have a breadth of customers, and we have different types of customers from digital natives, AI labs, traditional enterprises, financial and capital markets customers. So it's a broad set of customers. Many of them have either started with using TPU systems, for example, in our cloud. We have over 100 significant TPU customers who start in our cloud. They learn to use TPUs.
And remember, a TPU system is a combination of hardware, system software, compilers, the whole thing assembled as a system, including optical networking and other things. We've taken a very deliberate approach on how we're bringing TPUs to customers. The first one is to build the right silicon. So we have 8t for training, 8i for inference. They both offer substantial price performance and performance improvements relative to prior generations.
22 | Google has now optimized the software, PyTorch in TPU, and are broadening distribution for customers to use TPUs, not just in Google Cloud but also in their own data centers and to other providers like Oracle and Crux AI.
Second, we've optimized the software. The optimization in the software is not just to make the systems run better and to give you great performance but also to see -- make portability seamless. Recently, we introduced, for example, PyTorch, which opens up a much larger market for us by optimizing PyTorch in the TPU. Third, we are broadening distribution. So in the past, you could use TPUs in our cloud.
Now we make for customers who want TPU systems in their data centers, we're making TPU systems available in their data centers. We're also broadening availability to other providers. For example, we announced a partnership with Oracle and we've launched along with Blackstone an agreement for Crux AI, a joint venture to offer customers TPU systems.
23 | Currently not breaking out any margins for TPU systems, focused on improving margins as they scale the TPU business.
On TPU systems and margins, we don't break out margins for individual products or infrastructure components. However, we see several benefits from designing and manufacturing TPU systems. So first of all, to remind you, the TPU system is not just a chip, but it's a complete system. Given the price performance benefits of TPU systems relative to competitors, growing demand for accelerated compute and the scarcity of accelerated compute, we're very focused on continuing to improve margins as we scale the business.
24 | TPUs are manufactured only after contracts are signed with customers. All inventory is associated with committed contracts. By selling TPU systems, it offsets the need for Google to pre-build data centers to host these TPU systems and allows them to scale faster.
Two additional points. First of all, when Anat mentioned that we procure components to build inventory, we only do that after we have signed contracts. So all of the inventory that -- for TPU systems are associated with committed contracts. Additionally, by putting TPU systems in third-party facilities and in customer data centers, it allows us, one, to broaden our addressable market. Some -- for some industries, they have data in their premise that they cannot move to a cloud, and it allows us to bring accelerated compute to where the data sits. Additionally, it also offsets the need for us to have to prebuild facilities to host these TPU systems.
25 | Gemini is a powerful accelerator for Google Cloud.
Gemini is also driving acceleration for our database, analytics and cybersecurity products. Gemini can now help users find, analyze and visualize information from structured and unstructured data. Gemini uses our knowledge catalog to find the right sources and definitions of information, improving accuracy, lowering token cost and making responses more reliable. Gemini uses our Lakehouse to access information from multiple systems with 0 copy. To respond to agentic analysis, BigQuery improved query speed over 40% YoY while reducing query processing cost by over 50% YoY.
26 | More than 2,600 customers have used at least $100 billion in tokens, and nearly 90% of Fortune 100 use Gemini Enterprise.
Over the past 12 months, more than 2,600 customers have used at least 100 billion tokens and nearly 75 at least 10 trillion tokens on Gemini Enterprise. Nearly 90% of the Fortune 100 use Gemini Enterprise, and customers who use Gemini Enterprise in Q3 2025 more than quadrupled their spend with us year-over-year. One of the important ways in which customers are using Gemini is for knowledge work. Across all our AI services, we have sold more than 100 million seats for knowledge work. Gemini Enterprise now includes the Gemini agent that is deeply integrated across our entire cloud portfolio.
27 | People using Google's AI features have 3x longer queries than traditional searches, and 1 in 5 use voice, images, or documents.
Let's turn to Search, which is bringing the benefits of AI to more people than any other product in the world. Just like our shift to mobile over a decade ago, we are focused on building the best Search user experience, followed by monetization. We are building one seamless experience across AI Overviews, AI Mode and traditional search. And people are using our AI features more searching in entirely new ways. Their queries are longer, personalized and multimodal. Queries in AI Mode are on average 3x longer than traditional searches, and 1 in 5 AI Mode searches globally use voice, images or documents. We have now crossed over 50 billion visual searches per month. One area I'm excited about is helping people get things done, be it booking reservations, filling in forms, scheduling appointments or making purchases.
28 | Google wants to bring agents as a unifying layer across all their products.
People are already using the Gemini app to do more than ask questions. They're using it to do things, including complex multistep agentic queries. Our Gemini 4 series has been a really big step forward here and has already been handling these complex tasks really well. Agents will operate as a unifying layer across our products, so you will see us extend these agentic experiences beyond Search in the Gemini app to Chrome, Android and our Workspace products as well.
29 | Google first wants to roll out Gemini agents for
enterprise, then later on to consumers.
We have been hard at work, and we decided to roll it out to enterprise first, which we announced with our Gemini agent for enterprise, essentially because they have the highest bar for security, governance and controls. And it's been well received, and we are in the process of expanding that. Later this year, we will bring that same experience to consumers, obviously, starting with the 1 billion users in our Gemini app. We already see people in the app moving beyond chat to what are tasks and agent-like experiences.
30 | YouTube continues to lead as the number one streaming platform in the U.S. in terms of watch time. The living room accounted for one-third of total YouTube ad revenues.
On to YouTube, which continues to lead in the living room as the #1 streaming platform in the U.S. in terms of watch time. It's also seeing good subscriber growth as I mentioned. At Made on YouTube last month, we announced more than 30 products and features for creators and viewers. One great example is custom feeds where you can simply pick a topic you love and get a tailored video home feed based on that topic…The third part is monetization starting with ads. Our focus remains on delivering value across the entire funnel. In Q3, living room accounted for over 1/3 of total YouTube Ads revenues.
31 | Amazon is joining YouTube shopping. Creators can now tag Amazon products directly on YouTube.
More than 1.3 million channels are enrolled in YouTube Shopping globally. Building on this momentum, we recently announced that Amazon is joining YouTube Shopping. U.S. creators can now tag Amazon products directly in their videos, shorts and live streams, driving direct conversions. Importantly, our subscription ecosystem continues to complement our advertising business.
32 | Integration of Gemini models into Google's ad infrastructure is improving how they decode user intent and driving growing ad relevance.
First, ads quality. The integration of Gemini models into our ads infrastructure is improving how we decode user intent and drive ads relevance. For example, in Q3, we made the biggest update to product listing ads in a decade, adding new AI capabilities to help users make more confident purchase decisions. Already, we've seen satisfaction increase by 19% and dissatisfaction dropped more than half. We're also seeing AI models enable better prediction of clicks and conversions, stronger overall performance and deeper personalization of ads. For instance, through several innovations and personalization modeling, we delivered 18% incremental advertiser value and an 8% increase in user sentiment on Discover ads in 2026. Overall, AI is accelerating our ads development and drives the majority of our product launches.
33 | AI is also accelerating advertiser tools, allowing every advertiser, regardless of size, to seamlessly participate in all of Google's AI surfaces.
Second, advertiser tools. We're ensuring every advertiser, from global brands to small businesses, can seamlessly participate in our AI surfaces. AI Max and Performance Max continued to see strong adoption. To give marketers even more control, we're now introducing a way to test different budgets and ROI targets across multiple search campaigns in a single AI Max A/B test. To drive better performance, we integrated our AI creative tools directly into AI Max. In Q3 alone, Gemini models helped advertisers generate over 1.5 billion campaign assets, up over 7x YoY.


34 | Many of the queries on AI mode are upper-funnel queries, allowing Google to capture new, high-value commercial intent. Bringing ads into AI mode.
Third, AI user experiences. Sundar mentioned the distinct behavioral changes we're seeing as users ask entirely new categories of questions. We think of search holistically, a unified product spanning traditional results and AI-powered search. On AI Mode, many of these queries are upper-funnel queries, allowing us to capture new high-value commercial intent. In addition, the majority of AI Mode queries are incremental, creating more monetization opportunities over time. Additionally, our user research shows that people are comfortable with ads on these surfaces and find them highly relevant. Click-through rates are already similar between sponsored and organic product list items within AI Mode. Based on these collective results, we're now scaling high-quality ads within AI Overviews and AI Mode to more users and queries. This includes taking our monetization footprint global for the first time. Today, we're announcing the expansion of ads in AI Mode into international markets alongside multiturn ads and AI Mode in the U.S.
35 | UCP is being rapidly adopted by retailers, enabling direct checkout for hundreds of thousands of brands, and with Agent Payments Protocol, it unlocks agentic capabilities for consumers.
The Universal Commerce Protocol, UCP, is being rapidly adopted by retailers. Today, UCP enables direct checkout for hundreds of thousands of brands across Google, including Chewy, Nike, Tapestry and many more. We're combining this with the Agent Payments Protocol as we build for the future of commerce. Our focus spans 2 fronts: unlocking agentic capabilities that act on behalf of the consumer, and designing practical tools that give shoppers confidence and control. We launched Universal Cart this quarter to support that second track, mirroring how people actually shop today across Google.
36 | Google is operating a scaled consumer business and a hyperscale cloud business. Google's full-stack approach continues to drive a lot of efficiency and gives them a lot of optionality across a wide variety of opportunities.
We are operating a scale consumer business that reaches billions of people, a hyperscale cloud business with a lot of momentum and of course, a range of other highly important areas across Google and Alphabet.
We always take a long-range planning. And so each of our business areas submit long-range plans with a very disciplined ROIC framework. And so I would broadly think of all of this as a long-range planning process, not a short-term allocation exercise. Obviously, our AI models underlie everything we do from Search and YouTube to Cloud to Waymo and so on. So it's the foundation and we view it as a highly leveraged approach, the full stack approach drives a lot of efficiency as well as gives us a lot of optionality across a wide variety of opportunities. So obviously, that is the foundation, and we plan for that for the long term, too.
37 | Google remains disciplined on long-range planning and is seeing very robust demand signals across a wide variety of areas, and is hence investing ahead of that.
And about that, as I said, we really look at our businesses and really take a disciplined long-range planning approach. To us, obviously, we are seeing very, very robust demand signals across a wide variety of areas. And so we view it as an extraordinary set of opportunities, and we are investing for that moment.
➡️ Key Takeaways on Alphabet:
The core Google Search / YouTube advertising business and the consumer surface remains intact with AI overviews. Most of the upper funnel, high-value commercial intent queries still continue to remain on Google. Google’s full stack approach towards AI and their clear dominance with their own custom ASICs chips is why we initiated an investment in Alphabet. Increasingly, more of the AI accelerators will be custom ASICs and increasingly Google TPUs as it expands customer adoption and across in more ways. Google is one of our preferred ways to increase our AI exposure instead of via Broadcom (custom ASICs).

Adyen $ADYEN 563Q26 Earnings
- Processed Vol €451b +30% ↗️🟢
- Digital Processed Vol +28% ↗️🟢
- Unified Commerce Processed Vol +22% ↗️🟢
- Platform Processed Vol +55% ↗️🟢
- Net Rev €738m +23% ↗️🟢
- Digital Net Rev €387m +16% ↗️🟢
- Unified Commerce Net Rev €250m +29% ↗️🟢
- Platforms Net Rev €100m +46% ↗️🟢
*Talon.One and Orb acquisitions added 200bps to growth
- Active Business cust 312K +48% ↗️🟢
- Platform Cust >$1bn processed vol 46 +48% ↗️🟢
FY26 Mgmt Guide
- Net Revenue +23% ↗️🟢
- EBITDA margin 50% (lowering from 55%)
- Capex margin 7%
1 | Solid quarter. Adyen's same engine continues to run.
So the financial results are solid. And what I'm very proud of is the fact that the same engine runs as always. We win share of wallet with our existing customers, and we added new logos to the platform. So this combination has always been the core of our growth and it drives on the operational complexity that we are solving for these customers.
2 | Three core engines drove strong revenue growth, increasing share of wallet with existing customers, adding new customers across priority verticals, and acquisitions adding 200 bps of growth.
Three core engines drove this top-line performance: First, we deepened share of wallet with existing enterprise merchants, as longer standing cohorts consolidated more of their global volume onto our single platform. Winning a greater share of volumes from these merchants is the largest contributor to our growth. Second, we onboarded a healthy, high-quality cohort of new enterprise customers across our priority verticals. This year’s cohort is shaping up to be our largest ever. These customers are larger, and many are Platforms. We expect them to ramp significantly over the next year. And third, we consolidated Talon.One and Orb for the first time, which together added about two percentage points to our constant currency net revenue growth in the quarter. Commercial momentum remained strong and broad-based across all three pillars and every region.
3 | Digital saw the slowest growth, driven by OTAs and ride-hailing platforms, and content subscription customers and the major hyperscalers.
In Q3, Digital net revenue grew to €387 million, up 16% YoY, or 14% on a constant currency basis. Volume was up 28%. We delivered particularly strong growth in travel & mobility, which includes major rideshare platforms and Online Travel Agencies, and also across content & subscriptions merchants. This segment includes the major hyperscalers, where we continue to grow our share of wallet. Our tiered pricing is designed so that as our largest merchants scale, they consolidate more volume onto our platform, driving continuous wallet-share gains.
4 | Continue to target larger and more complex global retailers in Unified Commerce. Acquisitions added revenue without payment volumes.
In Unified Commerce, net revenue reached €250 million, up 29% YoY, or 27% on a constant currency basis. Volume grew 22%. Net revenue outpaced volume in the quarter following the consolidation of Talon.One, which contributes recurring revenue but no processed payment volume. We now support 499 enterprise merchants processing across both in-store and digital channels at scale. We intentionally target growth from larger, more complex global retailers. And these multi-channel implementations represent deep customer relationships, where the value we deliver drives substantial share gains.
5 | Platforms grew strongly, expanding it rapidly across SaaS and in complex verticals like financial services and insurance.
Platforms net revenue hit €100 million, up 46% YoY, or 44% on a constant currency basis. Volume grew 55%. We now have 46 platform customers processing over €1 billion annually — a significant step up from 37 last quarter, and 31 a year ago — with active business customers reaching 312,000, up 48% year-over-year. We are growing rapidly across SaaS, and winning share in complex verticals like financial services and insurance, which will be a driver of future growth.
6 | Adyen is well positioned to do well in facilitating Agentic Commerce because they have their own banking licenses in multiple countries and own acquiring licenses on any single platform globally.
And we are very well positioned here with our own banking licenses in multiple countries, with our own acquiring licenses and a single platform globally. I'm often asked what our position is in Agentic Commerce. And it's important to make a distinction between Agentic Commerce and the AI economy that I just talked about. If you look at global commerce, it runs today on Adyen and so will Agentic Commerce in the future. It's still early days, and we are focused right now on making sure that we build that right foundation.
7 | Adyen has built all the different components needed for Agentic Commerce in the past: authentication layers, fraud systems, and efficient settlements.
The reason why we're so well positioned is because we have built all the different components that are needed for Agentic Commerce in the past. So we've built authentication layers. We have built fraud systems. We've built ways to make the settlements as efficient as possible. And that's exactly the infrastructure that you need to build. And no one has this infrastructure like we do, and that's why we're so well positioned. So in summary, over the years, we have built the right rails for Agentic Commerce.
8 | Orb acquisition provides billing and invoices based on user base billings are what the AI-native economy requires.
Yes. So the other big news of the first half year, of course, were the acquisitions of Orb and Talon.One. And I'm very excited to see how integration is going. It's also one of the reasons why we've decided to double down our investments in this area. So maybe to start with Orb.
Orb is a billing and invoice engine focused on user-based billing, which is exactly very relevant for the AI native economy. And what I've seen in the last quarter is that we are now capable of signing up customers at an earlier stage in their life cycle.
Examples here are Vercel and Greptile. But also what I've seen in the last quarter that we were capable of signing up customers that were already an Orb customer, but are now starting to transfer their payments to Adyen. And examples here are Route and Wasabi Technologies. So a lot of progress with Orb.
9 | Talon.One acquisitions solves the persistent problem of in-store loyalty.
Very similar with Talon.One. The moment we announced the acquisition, the feedback from retailers has been very positive. The unsolved problem of loyalty in store is something that they are looking for. And in the past quarter, we have worked together with a lot of retailers to see how exactly we're going to tackle these problems. In a couple of weeks, we have organized an event with 200 global retailers in London to showcase how the future of loyalty will look like. And of course, I'm very excited to see those customers there and to discuss it with them.
10 | Merchant interest is stronger than initially anticipated. Retailers are keen to unify loyalty across every channel. AI-native companies see the value of a single provider for billing and payments.
Second, merchant interest in Talon.One and Orb has been stronger than we initially anticipated. Retailers we talk to are extremely excited to unify loyalty across every channel. AI native companies see the value in a single provider for billing and payments. Only Adyen can provide all of these solutions on a unified platform and at scale. That's what gives us the confidence to act now. Serving our global enterprise merchants takes more product, engineering and go-to-market capacity, so we are accelerating our investment. These are growth acquisitions, and we are doubling down to rapidly achieve their potential.
11 | See these acquisitions as significant parts of Adyen in the future.
the revenue pools or the expected revenues from both Talon.One and Orb will be significant in the future because it's going to be an important part of our business.
12 | Added headcounts from the acquisitions and continue to 1,100 FTEs in total
On the team, in Q3, we added 177 net new FTEs on an underlying basis, bringing us to 426 year-to-date and 399 colleagues joined us from Talon.One and Orb. We ended the quarter with 5,596 FTEs. For the full year, we continue to expect 550 to 650 net new hires on an underlying basis. Including Talon.One and Orb and the additional hiring we are now doing in those businesses, we expect to add 1,000 to 1,100 FTEs in total.
13 | Higher personnel costs will weigh on EBITDA margins in the short term.
So on the costs, people is the largest component. There are some of the nonrecurring costs related to integration as well, but it's relatively small. The thing that I -- the color that I would add around people is we're also increasing in a very competitive marketplace, equity compensation. And I'll call out that within our EBITDA margin guide, we don't back out stock-based comp.
14 | Adyen pursued acquisitions for the first time, not for growth but for adding capabilities.
So if you look at our M&A strategy, we indeed have added 2 companies this year to our family. And the reason why we've done that is because we saw the complexity from our merchants in billing and loyalty, and we want to solve for that complexity. So it's a capability game. We've not acquired them for their short-term revenues. It's really about a long-term capability, and that's how we will continue to look at M&A.
15 | Adyen will always prioritize organic investment first, and if too slow, then will consider M&A.
So if you think about what is important to our customers, the type of challenges that they face, if there is any capability that we think is missing and the time to market is the highest priority, we would consider M&A again. That's how we currently look at it. Our first approach to investment is always organically. That's how we've built. It's also the strength of our single platform. So that's always the first choice. But if time to market is important and it is a capability that our merchants are looking for, we would consider it as a next step.
16 | Don't see a structural change in the course of growth. Decided to use acquisitions as a deliberate opportunity and decision to accelerate investment to capture the immediate large present opportunity.
So on cost of growth, I don't think that there's been a structural change. As we said, it's a deliberate opportunity and decision to accelerate investment in order to capture the overall opportunity ahead, which is, we think, quite large. Pointing to the business overall, you've seen historically that we've generated leverage -- operating leverage, and we expect that over time, but we do want the flexibility to take actions when we see the opportunity ahead of us. Ingo, I guess, in the second one.
17 | The milestones to judge returns will really be growing the overall product offering and increasing customer adoption and cross-sell.
So the milestones to judge return are really around driving sustainable growth and the overall product offering that we are able to deliver. So it's going to be customer adoption. There will be cross-sell associated with it. And then overall, the way we'll talk about it from a company perspective will be on a consolidated basis, ultimately. We don't plan again on breaking out or loyalty or those things individually. But we will give qualitative markers as you go forward.
18 | 2027 management guide will be shared in February.
we look at this as a long-term opportunity to help build a new offering over and above not just loyalty, not just billing, not just payments, but together. So we'll give you that color on a combined basis in February. With regard to the discontinuing of the medium-term guidance going forward, we are -- we will provide an update in 2027 again for 2027. And we are, as we mentioned, discontinuing the EBITDA, the hard EBITDA target. I think that said, we are still very confident in the long-term durability of growth of this company and in the leverage that the company can provide over time…
we'll provide the update for 2027 in February of 2027. The color I can give you today is like, as we said, historically, we have generated margin expansion. We are intentionally deciding in 2026 to pull forward some of that spend. The other thing that I can say is that in 2026, there are some charges related to the acquisitions and other things that we don't expect to recur in 2027 as well.
19 | Adyen is building a company for the long run. They will invest and are okay with lower near-term profitability while retaining stronger long-term growth.
I think the philosophy that we have is that we built the company for the long run, and we want to take investors on that long-term journey. At the same time, we want to be helpful how we think that the business evolves.
And we are a very entrepreneurial business. So if we see an opportunity, we want to act on it. When we gave the 28% EBITDA guidance, we had not acquired Orb and Talon.One, and we did not have the feedback from our customers to see what kind of opportunity this was. We saw the complexity arising. So it was something in the back of our mind.
And we see that we will potentially be hindering ourselves if we would really get to this 55%. Because if you ask me, could we get there, it would be relatively easy to get to the 55%, but that would be at the risk of longer-term growth. So it's really about that longer-term horizon that also what I talked about that we want to create here. That's still also the guidance framework that I apply. If I look back, I think if you want to build a company for the long run, you should take investors along what it will mean for the short term.
20 | Continues to intend to outgrow the market and increase the scope of what they solve for their customers across the commerce life cycle.
To wrap up, we enter the final stretch of 2026 with strong commercial momentum across all 3 pillars, high conviction in our strategic investments and confidence in our unique ability to capture the massive opportunity ahead. We intend to continue to outgrow our market as the scope of what we solve increases across the commerce life cycle. Our actions this year position us to grow our role within customer operations, extend our market leadership and expand our growth opportunity.
Final Takeaway on Adyen $ADYEY:
➡️ Combination of strong durable net revenue growth 20%+, lowest costs, built from scratch superior single platform with data insights, with scaled economics shared (lower take rates), with strong unit economics of low marginal costs, and rising profit margins, with operating leverage, supported by long-term tailwinds. Excited about strong growth across all three pillars, digital, unified commerce, and platforms, North America, and AI native companies. Two acquisitions remain strategic, and prefer to build themselves organically, rather than being a serial acquirer to grow inorganically instead. Adyen looks increasingly well poised to be a secular beneficiary from AI native customers and agentic commerce.

Anthropic's S-1 disclosed US$807bn in committed compute (US$657bn contractual) over the next 10 years.
52.8% of Anthropic's committed compute will be Google TPUs (US$425.7bn), 31.1% will be NVIDIA GPUs via SpaceXAI, Microsoft, Nscale, and Lambda, 13.6% will be Amazon Trainium (US$110bn), and 2.5% will be AMD GPUs (US$20bn).
66.4% will be custom ASICs (Google TPU and Amazon Trainium), and 33.8% will be GPUs (NVIDIA and AMD).
Source: Anthropic S-1, Vision Capital Fund calculations.

I just set up the “Hey Siri” equivalent on my iPhone for these via Accessibility/Voice Shortcuts and Shortcuts. I'm excited to see which one sticks more.
My initial sense is that Grok Bot and Claude are best for daily tasks and work on mobile, and Gemini for most general, speedy consumer questions.
Muse is relatively slow, and its smaller range of connectors than Grok Bot (with Cursor) is limiting my adoption.
Starting to realize why the Cursor acquisition made sense for Grok.


I have been spending less time on LinkedIn lately.
Guess I am not the only one.
Anyone else spending less time on LinkedIn and why?
Chart from SimilarWeb.

Days to exploit cyber vulnerabilities are rapidly decreasing.
The number of cyberattacks is growing exponentially, while the time between discovering and exploiting vulnerabilities is shrinking from months to hours, and soon to minutes.
AI is a growing tailwind for the best cybersecurity providers with strong, scalable architectures that can leverage growing network effects to discover and patch faster across all their customers.
Chart from JPMorgan.

YouTube has continued to gain share of US TV-viewing time, whereas Netflix has struggled to grow.
Interestingly, Warner Bros. Discovery has struggled, and Amazon is slowly growing its share from a small base.

