





So on $FNMA and $FMCC.
For those folks who took advantage of tax loss harvesting and are stressed out that the stock price went up quite a bit since last week, consider the possibility that Democrats might take either the House or the Senate in next week's election. If that happens, then the stock prices of Fannie Mae and Freddie Mac might dip and may even take a beating. Just something to consider...
Not financial advice. Do your own due diligence.
PS: Of course this is just my hunch. If I could predict how stocks will end up after an event, I would be wealthy.
AP retweeted

Denver Archbishop James Golka this week defended his participation in a prayer event with U.S. President Donald Trump at the Oval Office, citing the gathering as an opportunity to publicly pray and evangelize the faith.
Golka, who was installed in the Denver Archdiocese in March after serving as the bishop of Colorado Springs for several years, led a prayer during an Oct. 22 meeting at the Oval Office between Trump and several U.S. bishops.
During the gathering the archbishop in part prayed for the Holy Spirit to “surround our country, to protect us against any influence of evil.”
The prayer event generated some backlash for what critics have argued was a politically motivated photo opportunity on the part of the White House. Golka this week said he “knew people might be upset” at the event and that it could be "use[d] for political purposes.”
“But as I prayed about it, I thought that this is what Catholics do. We pray for people. No matter whether we agree or disagree on anything, we always pray for our country and leaders,” he said in remarks to the Denver Catholic.
Golka said during the meeting he articulated Church teachings to the president. “As Catholics, we’re called to share our faith in season and out of season and to witness to the dignity of every human person,” he told the Denver Catholic.
He denied that the event, including video of the prayer shared on social media, constituted an “endorsement” of the president. “That was never my intention,” he said.
“The bishops of the United States teach that the Church cannot champion any candidate or party,” he said. “I hold to that. However you vote, you ultimately belong to Jesus who loves you infinitely more than you can imagine.”
The archbishop said he has received criticism from friends about the decision and that he has responded by telling them: “I was being a Catholic priest.”
He described himself as “heartbroken” at the anger over the event. He urged Christians to “look beyond the headlines, which are often crafted to provoke, towards the full truth.”
“I will keep praying for our president, our governor and everyone who serves in public office, regardless of their party or position on divisive topics,” he said.
The Archdiocese of Denver said after the event that praying for public leaders “is a long Catholic practice” that dates back to Apostolic Age.
More: ewtnnews.com/world/us/denver…

I am now absolutely convinced that Trump releasing $FNMA and $FMCC is a foregone conclusion. Our favorite president @realDonaldTrump for several times keep calling out Director @pulte for the great job he did in making Fannie Mae and Freddie Mac much more valuable now (like at least a trillion dollars) than when he took over. Note the focus of the president on the market value of them as companies. Why focus on that?!
In addition, President Trump authorized ads on $FNMA and $FMCC. Most American people haven't heard of Fannie Mae and Freddie Mac so why spend money advertising these twins?? If President Trump does not intend to release the twins and does not want to change the status quo, why create the buzz?!
Do I think Trump releases Fannie Mae and Freddie Mac? Absolutely I do!

My responses to his key points:
1. He argues that the NWS payments are dividend payments and therefore they do not reduce the principal loan that $FNMA and $FMCC owed to the Treasury. However, note that the NWS amounts to a 100% dividend payment which the jury on Fairholme case found to be a breach of the implied good faith covenant and fair dealing. If the jury found the NWS to be illegal, then it cannot possibly be that it remains to be recognized as dividends. If it is not dividends, then the only accounting entry for the NWS is "payments towards principal". As the treatment of liquidation preference is going to be discussed, people in that discussion cannot set aside the findings of the jury in Fairholme case.
2. He also argues that under @BillAckman plan, "taxpayers would remain exposed to catastrophic losses" because of the continuing federal support to $FNMA and $FMCC. Peter seemed to forget that right now, while "taxpayers are exposed to catastrophic losses" because the twins are under conservatorship, taxpayers are not getting paid for taking the risk absorbing any future losses. In addition to the fact that taxpayers were currently not getting paid for taking the risk of absorbing any future losses, the taxpayers are actually on the hook to absorb 100% of any future losses. Under Bill Ackman's proposal, taxpayers will be paid a commitment fee for taking the risk of future losses. In addition, the beauty of Ackman's proposal is that any future losses that the taxpayers might absorb is capped at the agreed letter of credit. So Bill's proposal puts a limit to how much the taxpayers will absorb in terms of potential future losses. It should be obvious that releasing Fannie Mae and Freddie Mac is the better option.
3. Peter made this outlandish claim and I quote "Neither the sale proceeds nor the value of the remaining shares can simply be presented as wealth newly created by privatization." How you can make that statement is beyond me. When the government sells its common stocks, it generated cash that would not have been generated if the government does not release $FNMA and $FMCC. If those hundreds of billions of cash that got generated is not wealth generated by privatization, then I don't know what that is.
Mr President @realDonaldTrump Mr Treasury Secretary @SecScottBessent and Director @pulte We the People trust that the wholesale thievery that Obama did will finally be rectified under the direction of our favorite president, President DJT!

Pershing Square’s @BillAckman presents his proposed Fannie and Freddie privatization as a windfall for taxpayers. But assigning a higher market value to shares the government continues to hold does not, by itself, create new wealth for taxpayers.
Taxpayers already own valuable senior preferred-stock rights and warrants. Ackman wants Treasury’s preferred investment deemed repaid. Yet past payments were dividends; they did not extinguish that investment under the agreements. Giving up those rights without equivalent compensation would surrender taxpayer value, regardless of whether Washington writes another check.
His more recent relisting proposal emphasizes the estimated value of Treasury’s retained common shares. If Treasury sells only a small portion, most of that headline valuation would remain an unsold asset—not cash received. Unsold shares have economic value, but that value must be compared with the rights and future income taxpayers surrender, together with the cost of continuing federal support. Merely replacing a valuable senior claim with an estimated common-stock value does not establish a gain.
Any eventual stock sales must pass the same test. Selling an income-producing asset generates cash while relinquishing future income. Neither the sale proceeds nor the value of the remaining shares can simply be presented as wealth newly created by privatization.
A significant part of the shares’ value would reflect continuing federal support and privileges unavailable on equivalent terms to competing mortgage guarantors (a privilege that may violate the Equal Protection Clause of the U.S. Constitution). To the extent an underpriced government backstop increases share prices, Washington would be helping support that valuation at taxpayers’ expense. That subsidy cannot simply be counted as a taxpayer windfall.
Before conservatorship, Fannie and Freddie’s securities expressly disclaimed a federal guarantee. Investors nevertheless assumed Washington would prevent a default. That was the “implicit guarantee.”
Ackman wants eventual release with explicit contractual Treasury backing. His January 2025 exit plan assumed roughly $445 billion would become available for future support, including about $191 billion already drawn. Trump cannot create authority for those commitments merely by signing an executive order. Anything beyond existing statutory authority requires congressional approval, which a Democratic-controlled Congress will likely refuse to grant.
While private investors would absorb initial losses, taxpayers would remain exposed to catastrophic losses. Meanwhile, surrendering Treasury’s senior rights would allow more earnings to flow to private shareholders. A severe housing crash would destroy the value of Treasury’s retained common shares precisely when its backstop was called upon.
Ackman’s plan entrenches the moral hazard that contributed to the original collapse and bailout. After nearly two decades of conservatorship, we would emerge with the fundamental problem not only intact but worse. Calling the backstop “paid for” does not establish that its price adequately protects taxpayers.
Ackman assures the public that his plan will not lead to higher mortgage rates. But that is only possible if taxpayers absorb risks that private lenders otherwise would have priced in. Advocating for such a government subsidy is a rejection of capitalism, as it substitutes government price fixing for free-market price discovery.
If Trump and Ackman want smaller government and free markets, they should work toward ending mortgage subsidies and allow private investors to price and bear the risks. Government subsidies inflate housing prices, encourage excessive risk-taking, raise default rates, and lead to larger losses.
More importantly, government subsidies encourage people not ready to assume the responsibility or the expense of homeownership to buy instead of rent. A free market in mortgage lending will better ensure that homes are purchased by borrowers who can truly afford to own them.
Ackman has disclosed his funds’ ownership of Fannie and Freddie shares, so he is not hiding that conflict of interest. But when he purports to advocate public policy, he is really just talking his book. If Ackman really believes his proposal is in the best interest of the country, and not just in his personal financial interest, I challenge him to publicly defend that position in a debate with me. I have no position in the GSEs and no personal financial interest in the outcome. My only goal is to move the country closer to free-market capitalism and further away from socialism.
So of that $385Bn, only $191Bn was actually drawn by Fannie Mae and Freddie Mac. The $194Bn that was added is due to Calabria's Letter Agreement last 2021 when he cancelled the NWS only to be replaced by another NWS disguised under a different mechanism with a different name. Given that Fairholme found that the NWS is a breach of implied good covenant and fair dealing, I expect the additional $194Bn to be rendered a violation of implied good faith covenant and therefore has to be cancelled. I also expect the NWS that was remitted to the Treasury (given that Fairholme found them to be a violation of fair dealing) to be recognized as payments towards the $191Bn loan of $FNMA and $FMCC. Therefore the current liquidation preference that stands right now is good as having been fully paid.
In other words, deeming the liquidation preference as FULLY PAID is not a dole out. This is because Fairholme is saying the NWS that the Treasury claims is its dividends on its SPS is a breach of covenant and fair dealing. And if it is a breach of implied good faith covenant, then those NWS cannot be recognized as dividends. And if it cannot be recognized as dividends, then the only valid accounting entry for those NWS are payments towards the principal loan. And if that is the only valid accounting entry for those NWS, then the full loan of $FNMA and $FMCC totaling around $193Bn has indeed been fully repaid. And then some.
@pulte @SecScottBessent @BillAckman @realDonaldTrump

The issue however is if Trump does not release $FNMA and $FMCC, then we are forfeiting hundreds of billions of dollars of windfall for American people as the government will own 79.9% of common stocks. The taxpayers bailed these twins, the taxpayers deserve their hundreds of billions of dollars of windfall.
Second, keeping them under conservatorship denies the American taxpayers any additional benefit (aside from the $300Bn already paid to Treasury) because Fairholme put constraints on what the government can do. In view of Fairholme, the government does not have any incentive to keep Fannie Mae and Freddie Mac under conservatorship.
If Fannie Mae and Freddie Mac are ever privatized, it will be a disaster for taxpayers and new investors who buy in, but a windfall for existing investors like @BillAckman who cash out. However, since any move to privatize will push mortgage rates higher, it's unlikely to happen.
This is an extremely bullish sentiment. Bill Ackman gave us an indication of the Trump administration's thinking. At this price level, these stocks are stupidly cheap quoting Ackman's post a while back.
After watching this interview, I am more convinced of the timeline I was thinking of, although now I find that timeline quite conservative in view of this information from Bill.
Initially I argued that Trump most likely will wait till we are close to the warrant expiration for him to release and relist $FNMA and $FMCC. This will minimize the political firestorm that will follow the release as he can argue he has no choice but to release otherwise the warrants will expire and that will deny American people hundreds of billions of dollars of windfall. I argued we may start to see movement in Q2 next year and full speed ahead in Q3/Q4.
However, I think given that Sep 2028 is so close to the presidential election, releasing the twins so close to that date may not be politically prudent. The ideal timeframe therefore for release is either Q4 2027 or Q1 2028, hence Bessent's statement of next year or the following year. Releasing the twins in Q2 2028 is cutting it too close. Ideally, the release needs to happen Q4 2027 but in case there are still open items, maybe Q1 2028 is still OK. You want to release the twins with reasonable time gap to the presidential election to allow for the political dust surrounding the release to settle while the nation moves on to other REAL pressing issues. (Democrats will try to lie and gaslight about how bad releasing the twins are, but the American people are smart to see through the lies.)
Given this release date timeframe, we should start seeing movement Q1 next year and quite possibly right after midterms as Bill Ackman suggested. You need at least a full year to prepare for releasing and relisting the twins.
Borrowing Bill Ackman's post a while back, at this pricing level, $FNMA and $FMCC are stupidly cheap.
$FNMA $FMCC
🔥🔥🔥
@BillAckman with epically bullish commentary on Fannie Mae & Freddie Mac this A.M.
All the bases were beautifully covered. Thank you once again for your tireless advocacy, Mr. Ackman!
No chance DJT leaves F2 up for grabs at the risk of a democratic administration potentially regaining control.
Shout out to @CaliRefugee1 for continually banging that drum!
Not if...but when.
Tick, tock.
GLTA.
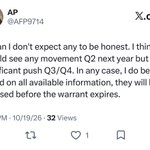
This aligns perfectly with my analysis. I do not expect that release or relist happening anytime soon. I expect it to happen close to warrant expiration on Sep 7, 2028. We may expect to see movement Q2 next year and ramping it up full speed in Q3/Q4. The reason for this is two fold:
1. Delaying it to this time frame will allow Freddie to catch up with Fannie in reaching the capital requirement (which I believe they will reduce). I long argued that they will release both $FNMA and $FMCC at the same time when people thinks they will release Fannie first and then Freddie a year later. I said I do not think they will do that because doing so will distort their stock prices.
2. Delaying it to this time frame close to warrant expiration will minimize any political risks since Trump can argue he doesn't have a choice but to release $FNMA and $FMCC otherwise the warrants will expire and that will deny the American people hundreds of billions of dollars of windfall. He can also argue that he cannot arbitrarily extend the warrant expiration because of Fairholme. Releasing them close to expiration date creates urgency, focus and a sense of inevitability.
So it make sense to delay. Hence Trump's "no rush" and Ackman's "patience" comments.

Administration plans Fannie and Freddie action in 2027–28, Bessent says share.google/qHQf0Wz7vYAPgN7…

I am not sure I am reassured by what Bessent said here. He said he is not sure how releasing $FNMA and $FMCC will benefit homeowners or the mortgage market. This doesn't sound encouraging coming from Treasury secretary considering that release is a politically risky bet. Pocanhantos and Democrats could replay what Bessent said here nonstop to attack Trump and GOP.

Bessent tells @MarkHalperin this AM that the Trump administration "will be tackling the ownership structure" of Fannie and Freddie "the next year [or] the year after."
"It's unclear why homeowners or mortgage holders would benefit for a change in the arrangement of the shareholder structure. So whatever we do is going to be guided by making sure that the spread on mortages ... does not increase; that's our North Star." youtube.com/watch?v=a3tbSNWI…

This aligns perfectly with my analysis. I do not expect that release or relist happening anytime soon. I expect it to happen close to warrant expiration on Sep 7, 2028. We may expect to see movement Q2 next year and ramping it up full speed in Q3/Q4. The reason for this is two fold:
1. Delaying it to this time frame will allow Freddie to catch up with Fannie in reaching the capital requirement (which I believe they will reduce). I long argued that they will release both $FNMA and $FMCC at the same time when people thinks they will release Fannie first and then Freddie a year later. I said I do not think they will do that because doing so will distort their stock prices.
2. Delaying it to this time frame close to warrant expiration will minimize any political risks since Trump can argue he doesn't have a choice but to release otherwise the warrants will expire and that will deny American people hundreds of billions of dollars of windfall. He can also counter argue that he cannot arbitrarily extend the warrant expiration because of Fairholme.
So it make sense to delay. Hence Trump's "no rush" and Ackman's "patience" comments.
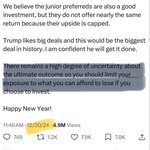
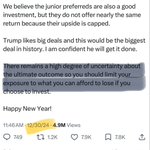
So if you guys want to take advantage of tax loss harvesting or even rotate your investment to Anthropic, go ahead. These Fannie Mae and Freddie Mac stocks aren't going anywhere any time soon!

People are asking why $FNMA and $FMCC are down today despite positive news of Fairholme. My guess is that people realize that the release is not happening soon. Since this is the case, a lot are selling at a loss for tax harvesting purposes and will buy back on 31st day. This being the case, stock will most likely be down in coming days.
Since Fairholme denies any incentive for the government to keep Fannie Mae and Freddie Mac under conservatorship, I am convinced they will be released any time between now and by the time the warrant expires.
The jury and the court in Fairholme case focused on shareholders reasonable expectations as of late 2009 when the relevant contractual framework for $FNMA and $FMCC is in effect. The jury found that the shareholders has the following reasonable expectations:
1. A realistic prospect of dividend payments the moment Fannie Mae and Freddie Mac turned profitable.
2. The conservatorship is temporary and that the GSEs are expected to be released.
3. The Treasury dividend pay is fixed at 10%.
While Fairholme cannot compel the government to do anything, it created constraints that the government must meet in any of their actions. In other words, there is a limit to what they can do subject to shareholders' reasonable expectations. This means:
1. The government cannot convert SPS into commons because the SPSPA in effect as of late 2009 does not allow SPS to be converted to common stocks. So all the talk of extreme dilation is now off the table because doing so will violate implied good faith covenant and fair dealing.
2. The government cannot resume dividend pay to them while denying dividend pay to shareholders. If the GSEs are profitable and they can afford to pay dividends, the government cannot arbitrarily act to collect dividends to their SPS while denying dividends to JPS and common stocks. Doing so will violate implied good faith covenant and fair dealing.
3. The government cannot extend warrant expiration arbitrarily because the SPSPA in effect as of late 2009 states that the warrant will expire by 5PM on Sep 7, 2028. Given that Pulte keep on certifying that $FNMA and $FMCC are safe and sound and that the GSEs keep passing the extreme stress tests, extending the warrant expiration will be an arbitrary act. This will violate the implied good faith covenant and fair dealing.
I expect the twin to be released before Sep 7, 2028z I expect significant actions picking up maybe Q4 2027 or even earlier to Q3 2027.
Bottomline, Fairholme is bullish to our cause.
PS: This is not a financial advice. Do your own due diligence.