

Deep tech | Small caps | Asymmetric opportunities before the market catches on. Institutional-style research by Alpha Metrics.
Joined May 2026
- Tweets382
- Following84
- Followers107
- Likes605



Pinned Tweet
Dear X community,
I run Alpha Metrics, an investment research platform with 500+ subscribers, focused on identifying where market pricing diverges from fundamentals—especially asymmetric opportunities with 2–6x potential.
My research covers the structural trends shaping the next decade:
• AI infrastructure
• Semiconductors and memory
• Photonics and networking
• Data centers and power
• Space and defense
• High-growth small caps
You’ll see analysis on companies such as $AMD, $MU, $SNDK, $RKLB, $NBIS, $SIVE and $AXTI.
I don’t simply share tickers. I break down the fundamentals, catalysts, valuation, risks and market signals behind each thesis through a data-led, investment banking perspective.
Here on X, I’ll share timely insights, market reactions, portfolio updates and high-conviction ideas.
On Substack, I publish the complete research, full investment theses, entry opportunities and transparent portfolio updates.
No empty narratives. No blind hype. Just data, fundamentals and asymmetric opportunities.
Follow Alpha Metrics and find the full research through the link in my bio.

“ I didn’t say short. I just provided the information one would need to sell.”
Translation: I made a bearish observation, kept every possible outcome open, and now I’m claiming victory after the stocks dropped.
I also once said the market looked vulnerable. Technically, I’ve been predicting every crash ever since.
I’m bullish on $CRWV, $NBIS, $NVDA and semis. NFA.

Coreweave, Nebius, NVIDIA, semis, I tried to warn you all. I didn’t say short. But I provided the information one would need to sell.
1
2
185
Huge bullish IMO.
Nebius ran an $11B funding gap in one quarter and the stock is down more than half.
Weak hands see a cash burn. I see a company that can't build fast enough.
When that line turns up, it won't be a bounce. It'll be a once-in-a-cycle move.
$NBIS $IREN NFA.

This is the single metric that's driving the market insane with neoclouds.
Operating cash flow, minus customer prepayments, minus CapEx.
Strip out the prepayments and neither $IREN nor $NBIS funds its own build yet. The gap is widening as CapEx ramps.
The day this line turns up is the day dilution ends and FCF/share starts compounding.
That’s the inflection. Everything else is noise.

2
486
$AAOI "disappointed" because its biggest customer wants the better product too fast.
$400M+ of 1.6T orders waiting.
Only $50-70M can ship in Q4.
Chip supply gets much better in Q1.
A company that misses because nobody wants its product is in trouble.
A company that misses because everybody wants it just needs time.
IMO this is the best kind of miss.
$AAOI NFA.

Going back to $AAOI Q3 2026 earnings. Why did the company disappoint with its Q4 guidance?
$AAOI guided for $385–420M in Q4 revenue, below market expectations.
The reason is quite interesting.
One of AAOI's major hyperscaler customers is transitioning from 800G to 1.6T transceivers faster than management anticipated.
As a result, AAOI expects to sell fewer 800G transceivers than originally planned, but it can't ramp up 1.6T production quickly enough to offset the difference.
Why? They didn't secure enough 1.6T DSPs in advance.
AAOI currently has two qualified DSP suppliers (I assume Marvell and Broadcom) and is working on qualifying a third (my guess is Credo).
These are my assumptions, as management hasn't disclosed the suppliers' names.
According to management, DSP availability should improve significantly in Q1 2027.
If the third supplier turns out to be $CRDO, the timing would be interesting, considering Credo is also expecting a significant ramp in its optical business during FY2027.
However, this is just a hypothesis, not a confirmed relationship between the two companies.
I also think the recently announced ATM could partly be related to securing the supply chain.
AAOI needs significant capital to support its manufacturing expansion. It's not just about building factories and purchasing equipment. They also need to secure DSPs, wafers, substrates and other components months in advance.
And this isn't just an AAOI problem. Other optical transceiver manufacturers have also mentioned supply constraints and indicated they could produce more if certain components were more readily available.
Another thing I'll be watching closely is inventory.
AAOI's inventory increased significantly in Q3, reaching approximately $378M.
I expect another substantial increase in Q4 as the company prepares for higher production volumes.
For me, an increase in raw materials and components would be a positive signal that AAOI is securing its supply chain ahead of the planned ramp.
Of course, inventory growth alone isn't enough. Ultimately, I want to see those components turn into finished products and revenue.
But what does the faster transition from 800G to 1.6T actually mean for AAOI?
This is probably the most important part.
It means the company's product mix is shifting toward higher-priced transceivers faster than originally expected.
And that creates another opportunity for revenue growth.
According to industry pricing estimates, a 1.6T transceiver can cost roughly twice as much as a comparable 800G transceiver, depending on the configuration.
So AAOI has two potential drivers of revenue growth:
Increasing the number of transceivers it can manufacture.
Increasing the average selling price as 1.6T becomes a larger share of total shipments.
In other words, AAOI doesn't necessarily need to double its production volume to double its transceiver revenue, assuming the product mix shifts toward higher-priced products.
And I expect this mix to continue shifting toward 1.6T as hyperscalers upgrade their networks.
What's interesting is that the same transition hurting AAOI's Q4 revenue could become one of its biggest growth drivers in 2027.
Of course, management still needs to secure the components, complete supplier qualifications and deliver the production ramp.
But I see the faster transition to 1.6T as a positive signal for long-term demand, even if AAOI wasn't fully prepared for it in Q4.

3
394
A year ago, selling peptides at scale in the US was a fantasy.
Today $HIMS sells them with a doctor, a prescription and a box at your door.
If this is what "impossible" looks like for this company, I don't want to know what "possible" looks like.
Soft companies wait for permission.
This one built the factory first.
$HIMS NFA.
PS: I'm long $HIMS.

🚨 BREAKING: $HIMS LAUNCHES PEPTIDES+
Available now: Sermorelin, NAD+, Glutathione, Vitamin B12, and L-Carnitine
BPC-157 and TB-500 to be added later
Sermorelin: $149/mo
Glutathione: $99/mo
NAD+: $149/mo
L-carnitine: $129/mo
Vitamin B-12: $99/mo

Google was supposed to be losing the AI race.
So it released four Gemini 4 models and the newest one beats Opus 5.5 on the AI index.
Anthropic IPOs today, and I already told you how Google profits from that.
Losing looks great IMO.
$GOOGL NFA.


4
323
If this works at scale, $NAUT could become one of the biggest companies in the world.
Yes, I mean it.
Tau is a protein inside your brain cells. It works like the screws holding a railway track together. In Alzheimer's, tau gets chemical tags added in a certain order, falls off the track, and the cell starts to die.
Nautilus can read exactly which tags each tau carries, something very hard to do at scale until now. Next they're going after the Parkinson's protein, then a first cancer one, and the company says it wants about 20 tests by mid-2028.
Now picture that for every disease. I think whoever owns that map owns the data AI needs to find cures.
It's early, the human samples were tiny, 7 people. But the first one works.
$NAUT NFA.
I believe $NAUT is worth several billion today because it’s on a path to help us cure diseases like Alzheimer’s with a single prompt by 2027–2028.
The breakthrough isn’t measuring proteins better.
It’s learning to read the state machine of human biology.
Start with tau.
Nautilus’ tau paper found phosphorylation isn’t random.
Tau carrying pT181 was about 8x more likely to also carry pT217.
Why does this matter?
Phosphate groups change tau’s charge, conformation and interaction with microtubules.
Microtubules are the rails neurons use to transport mitochondria, vesicles and proteins.
Tau helps stabilize those rails.
Disrupt tau enough and you can trigger a cascade:
tau detaches → microtubules destabilize → transport breaks down → neurons degenerate.
Alzheimer’s may therefore not simply be a problem of too much phosphorylated tau.
It may be a progression through specific molecular states:
tau A → pT181 → pT217 → additional PTMs → pathological proteoform.
Until now, this combinatorial layer was hard to read.
Mass spectrometry measures mass and charge well.
But two intact tau molecules can have the same mass while carrying phosphate groups at different positions.
Same atoms.
Same mass.
Different potential biological behavior.
Fragmentation helps, but reconstructing the precise PTM configuration of millions of individual intact proteins is extremely challenging.
Nautilus approaches the problem differently.
It repeatedly interrogates the same intact protein using different probes.
Its tau assay reads isoform identity alongside 7 phosphorylation sites, resolving hundreds of potential molecular states.
And it does this with approximately 5.5% end-to-end CV, versus the roughly 25% industry benchmark cited by management.
Now here’s where things get really interesting.
Biology does not appear to occupy every theoretically possible molecular state.
Of the 768 tau proteoforms Nautilus’ assay could resolve, only 130 were observed across all samples.
And individual biological systems occupied far fewer.
Think about what that means.
The theoretical state space is enormous.
But the real biological state space may be constrained.
Which means biology may be far more predictable than we assume.
Now collect longitudinal data:
initial proteomic state + intervention → final proteomic state
Repeat that at scale, across millions of patients, thousands of interventions and billions of molecular measurements.
Eventually, AI stops being merely descriptive.
It becomes predictive.
Given molecular state X, which intervention moves the system toward healthy state Y?
This turns biology into a gigantic key:lock search problem.
For tau alone, it could mean identifying the intervention that prevents a pathological proteoform trajectory from destabilizing neuronal microtubules.
But tau is just one assay.
Add alpha-synuclein.
Amyloid-beta.
Cancer proteins.
Immune proteins.
Metabolic proteins.
And eventually thousands more.
Suddenly, you are no longer measuring isolated proteins.
You are learning the rules governing how entire biological systems transition between states.
genome + proteoform state + treatment history → full-body molecular state transition model
A genuine digital twin of human biology.
The implications are enormous.
Because the endgame is not simply detecting Alzheimer’s, cancer or other diseases earlier.
It’s asking:
Given this person’s current molecular state, what intervention moves them back toward a healthy state?
And having an AI trained on billions of measured biological transitions generate the answer.
Not by guessing.
But by learning how biological systems actually respond to interventions.
That is why I believe $NAUT is building something much larger than a proteomics machine.
It is building the data layer required for AI to learn how to steer human biology.
And if that thesis plays out, several billion dollars may be a very small valuation for what Nautilus is building.

$NAUT: +145% in less than 2 months.
That’s roughly 9 YEARS of S&P 500 returns at a 10% annualized return.
And it did it while the Nasdaq was getting absolutely slaughtered.
Think about that for a second.
The market has been panic-selling, tech has been getting crushed, and $NAUT has nearly tripled investors’ money in the middle of it.
This is insane.
I’m not watching this one from the sidelines. I’m long, I’m holding for the long term, and I’m incredibly bullish on what Nautilus is building.
The market can keep selling. I’m not selling $NAUT.
NFA.

"Never broken below." "Every time, a massive recovery."
Bitcoin is down 49% from the high and this is the most bullish message I've read all week, IMO.
Weak hands watch the price.
Strong hands watch the support.
If it holds, everyone who called it dead gets very quiet.
$BTC NFA.

Bitcoin has NEVER broken below this historical support line.
Every time Bitcoin reached this level, it was followed by a MASSIVE recovery.
And now, in 2026, Bitcoin is testing that exact same support again.
1
127
Huge bullish imo.
Management raises $550M to build more of the thing it can't build fast enough.
Market: sell.
Last raise: revenue +41% in one quarter. Stock: -70% since August.
If factories were free, everyone would own one.
$AAOI NFA.

$AAOI
With $AAOI already crushed 81% from its $233.67 peak to $45.22—and sliding toward $43 after hours—management just filed a new $550 million at-the-market stock offering, its fourth in nine months. Dropping another massive equity tap right into a bruised tape hits shareholders where it hurts most.
The dilution math turns punishing at depressed prices: raising $600 million at $183.06 this summer took 3.28 million shares, whereas $550 million at the $45.16 filing price requires 12.18 million new shares, a 13.4% share-count expansion. Applied Optoelectronics spent $1.19 billion across nine-month operating and investing cash outflows, carried $928.8 million in September 30 CapEx commitments, and just paid $102.25 million cash for three Houston plants to meet hyperscale 1.6T obligations.
Hyperscalers lock in contractually capped optical pricing while public shareholders foot a $2.25 billion 2026 ATM bill.


7
26
5,567
BULLISH $NVDA
The headline was the easy part.
The data center slide is the real story.
Hyperscale: $60.1B, up 71%.
AI clouds, industrial and enterprise: $47.5B, up 195%.
That second bucket was $16.1B a year ago. It nearly tripled.
This is not a one-customer story anymore.
$NVDA NFA.


I TOLD YOU. $NVDA IS AN ABSOLUTE MONSTER.
EPS: $2.68 vs $2.47 expected.
Revenue: $115.84B vs $108.71B expected.
+106% EPS YoY.
+103% Revenue YoY.
And people are still worried about competition?
Nvidia isn’t just selling chips. It’s building the infrastructure for AI, robotics, autonomous driving and the next generation of computing.
If the Jensen headlines turn into reality too, this could get absolutely crazy.
The market may have underestimated this one.
$NVDA back to ATHs. Just watch.
NFA.

1
173
I TOLD YOU. $NVDA IS AN ABSOLUTE MONSTER.
EPS: $2.68 vs $2.47 expected.
Revenue: $115.84B vs $108.71B expected.
+106% EPS YoY.
+103% Revenue YoY.
And people are still worried about competition?
Nvidia isn’t just selling chips. It’s building the infrastructure for AI, robotics, autonomous driving and the next generation of computing.
If the Jensen headlines turn into reality too, this could get absolutely crazy.
The market may have underestimated this one.
$NVDA back to ATHs. Just watch.
NFA.
Alpha Metrics retweeted

Over the past week, I’ve been overwhelmed by the love and support of friends, industry colleagues, and people I've never met. Thank you to everyone who has shown kindness to my family and me. It means the world to me.
I came to the United States 53 years ago, and becoming an American citizen is one of the greatest gifts and proudest moments of my life. NVIDIA has been my life’s work. Building it into the company it is today alongside my colleagues has been a privilege and an honor. Nowhere but in America could a company like NVIDIA be possible. I love our country, and I love NVIDIA.
I did not live up to the standards expected of everyone at NVIDIA, and I have made serious mistakes in my personal life. I created problems for the Board that I deeply regret. I own my mistakes completely, and I am committed to cooperating with the Board’s independent investigation.
Since my departure, I’ve seen an outpouring of calls from NVIDIA’s employees, investors, business partners, and customers for me to return as CEO. Many continue to reach out to me directly as the company navigates complex technology, market, competitive, and geopolitical dynamics. NVIDIA is a once-in-a-generation company. If the Board of Directors decides that my return is in the best interest of our shareholders, our employees, the company, and America, I would be honored to answer these calls and return as CEO.
Thank you again to everyone who has shared their good wishes. I am profoundly humbled by your support. To my family: I love you, and I will spend the rest of my life being worthy of yours.
Jensen
Go read Jensen Huang’s post.
I told you this was coming. 👀
I said I had been hearing things from people with serious inside knowledge. Now Jensen himself is publicly confirming that calls for his return are coming from employees, investors, partners and customers.
The pieces are falling into place.
Strong earnings on top of this? $NVDA could be in for an absolutely historic reversal.
We are so back. 🚀
NFA.
2
168
IREN is down 45% in a month.
Net asset value is about $33. The stock is $16.39.
Funding risk is real. So is paying 50 cents for a dollar of assets.
IMO the market just sold a balance sheet.
$IREN NFA.

$IREN
As I see it, net asset value today is ~$33/share. That's assigning nothing to the operating business.
I've seen estimates from others (who shall remain nameless) ranging from $28 to $40.
Even with a pretty penalizing 25% liquidation haircut, we're trading below liquidation value.
And that's assigning $0 to their 35 GW pipeline.

2
346
Huge bullish IMO.
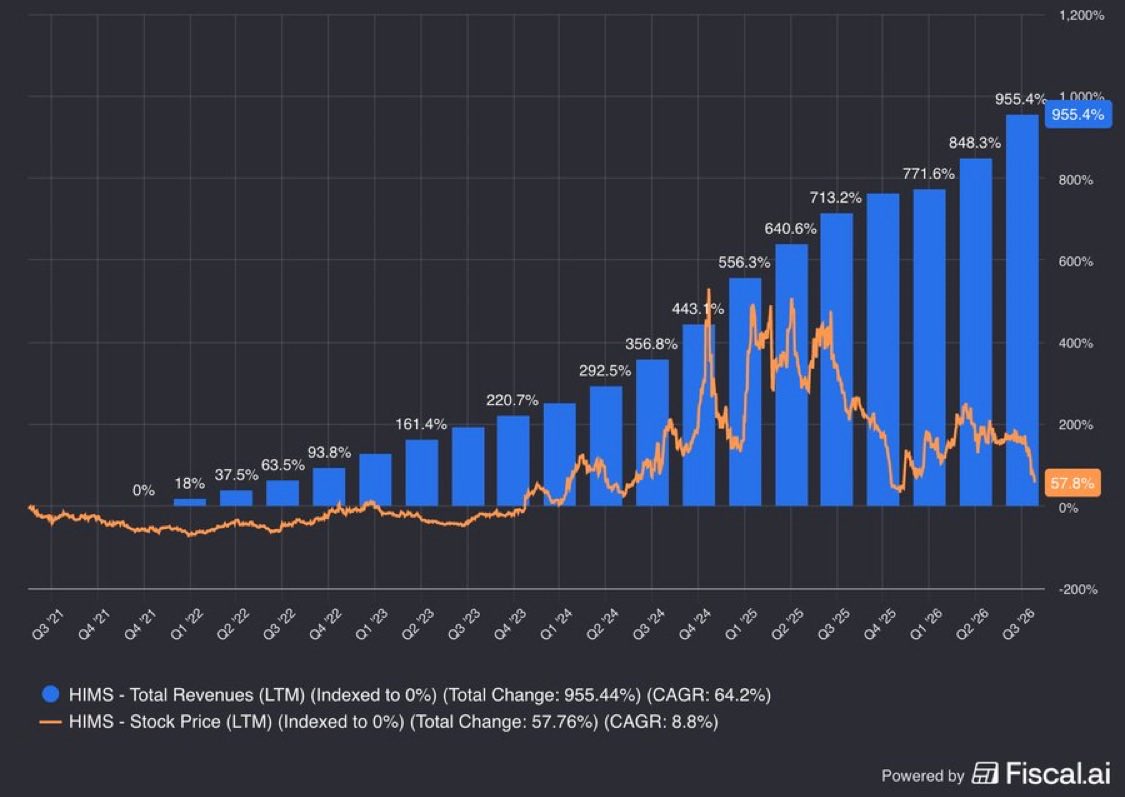
$HIMS websites went from 10.2M visits to 16.4M in one month.
The stock chart is still arguing with itself.
The traffic already made up its mind.
If the front door is this busy, the checkout is next.
$HIMS NFA.

We owe @AndrewDudum an apology.
October web traffic is in. $HIMS is flying again in the US! 🚀
• Hims: +67.9% MoM
• Hers: +54.4% MoM
• Combined: 16.44M visits (+61.7%)
And we're still waiting for the full international data.
$HIMS 🔥

Powell just beat EPS by 43% and the stock is down 53% since May.
IMO the market is testing my patience.
Weak hands fold at half off.
This one is locked in.
Orders are running at 1.8x sales and the backlog is $2.7B. If AI needs power, someone has to build the boxes.
$POWL NFA.


2
256
You know you’ve reached another level when even the President of the United States wants you back.
Imagine being Jensen Huang.
The controversy, the headlines, everything… and the conversation is STILL about bringing you back to lead Nvidia.
That’s what a legendary CEO looks like.
$NVDA could be entering its next chapter.
2
211
Imagine being so important to a company that, even after all the controversy, the tech world is organizing a WAR ROOM just to bring you back.
That’s Jensen Huang.
And I genuinely believe most people still underestimate what he wants to build with $NVDA.
We’re nowhere near the end of this story. 🚀

BREAKING: Jensen Huang is considering returning to Nvidia, $NVDA, as CEO as tech executives pressure the company’s board to reinstate him, per FT.
Huang is reportedly discussing a potential return even as an independent investigation by Nvidia's board is underway.
One "ally" of Jensen Huang is reportedly putting together a "war room" of tech executives to lobby for his return.
It's going to be an interesting week to say the least.