

Sharing daily wisdom about life, science, and much more. Want to learn more about Finance & Investing? Start here: https://xitter.cf/t.co/WYwY2XFlQg
Joined October 2024
- Tweets6K
- Following27
- Followers11K
- Likes366

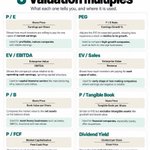


📊 8 Valuation Multiples Every Investor Should Know
Different multiples help answer different questions about a company’s valuation.
P/E: How much investors pay for every rupee of earnings.
PEG: Whether a stock’s valuation looks reasonable relative to earnings growth.
EV/EBITDA: Values a business relative to its operating earnings.
EV/Sales: Compares enterprise value with revenue, useful when profits are low or negative.
P/B: Compares market value with book value, often used for banks and financial companies.
P/Tangible Book: Compares market value with tangible net assets.
P/FCF: Shows how much investors pay for each rupee of free cash flow.
Dividend Yield: Measures annual dividends relative to the share price.
💡 Key takeaway: No single multiple works for every company. The right metric depends on the business model, profitability, growth and industry.
Want to learn more, get this best valuation guide for free
Valuation The Art and Science of Corporate Investment Decisions
lnkd.in/dEtpRNt8


Terminal Value: 2 Methods Every Finance Professional Should Know
Terminal Value (TV) estimates a business’s value beyond the explicit forecast period in a DCF model. It can account for a significant portion of total valuation.
1. Perpetuity Growth Method
Assumes cash flows grow at a constant rate forever.
Formula: TV = FCFₙ₊₁ / (WACC − g)
Best suited for mature businesses with stable, predictable cash flows.
2. Exit Multiple Method
Assumes the business is valued using a market multiple at the end of the forecast period.
Formula: TV = Terminal Metric × Exit Multiple
Common multiples: EV/EBITDA, EV/EBIT and P/E.
What should you remember?
The perpetuity growth rate must be below WACC for this formula to work.
Exit multiples should reflect comparable companies and market conditions.
Always test how changes in WACC, growth rates and multiples affect valuation.
💡 Key takeaway: Terminal Value can drive a large part of a DCF valuation, so choosing reasonable assumptions is critical.
Cash Flow Statement Premium Resource
lnkd.in/dhScq7gM
lnkd.in/d3H2sV_j
lnkd.in/d5CSD2rV


📊 Pricing of Swaps: 8 Key Steps to Understand
An interest rate swap exchanges fixed and floating cash flows. Its value changes as market interest rates change.
Here’s how swap pricing works:
🔄 Understand the Swap: Identify the notional amount, tenor, payment frequency and fixed/floating legs.
📈 Gather Market Data: Use discount curves, forward rates and market swap rates.
💹 Project Floating Cash Flows: Estimate future payments using forward rates.
🧮 Calculate Fixed Cash Flows: Apply the agreed fixed rate to each payment period.
💰 Discount Cash Flows: Convert future payments into present values.
⚖️ Calculate Swap Value: PV of the received leg − PV of the paid leg.
🤝 Settle the Net Amount: Account for netting, collateral and settlement terms.
✅ Validate the Result: Check market rates, curve assumptions and sensitivity to interest rate changes.
Key formula:
Swap Value = PV (Receive Leg) − PV (Pay Leg)
💡 Remember: A swap’s value depends on market rates, the discount curve and whether you receive or pay each leg.
Want to learn more, Get this Master Financial Swaps in Minutes
lnkd.in/d6tgSWyB


Mergers & Acquisitions involve much more than just buying another company.
A proper M&A analysis looks at the full picture:
• Target valuation and Enterprise Value
• Offer price and acquisition premium
• Sources and uses of funds
• Debt, leverage and financing capacity
• EPS accretion or dilution
• Cost and revenue synergies
• IRR, NPV and expected returns
One of the biggest questions in any deal is simple:
Will this acquisition create more value than it costs?
A deal can look attractive based on headline numbers, but the real value depends on the price paid, financing structure, synergies and returns generated after the acquisition.
📌 A useful cheat sheet for anyone learning M&A, valuation and financial modelling.
Want to learn more, Get this M&A Guide for Free Here
lnkd.in/d_nn7fwb


IFRS vs US GAAP — quick cheat sheet:
IFRS:
More principle-based
Flexible interpretation
Used globally
US GAAP:
More rule-based
Detailed accounting guidance
Primarily used in the US
Key differences:
Revenue Recognition:
IFRS → Control-based principles
GAAP → More industry-specific rules
Inventory:
IFRS → No LIFO allowed
GAAP → LIFO permitted
Development Costs:
IFRS → Can capitalize under conditions
GAAP → Mostly expensed immediately
Leases:
Both recognize leases on balance sheet, but GAAP has more exceptions.
Impairment:
IFRS → One-step approach
GAAP → Two-step approach
In one line:
IFRS focuses more on principles.
US GAAP focuses more on detailed rules.
Want to learn more?
Grab this IFRS Vs US GAAP PDF here: lnkd.in/ewEHJM2M

