

My portfolio, my thoughts. Sharing analysis on stocks I own or am actively interested in, Macro and Bitcoin. Not financial advice.
Joined September 2025
- Tweets2.2K
- Following607
- Followers1.2K
- Likes26.9K




$SPCX is now below IPO price again and I’m loading up here.
The bull case in 3 lines:
→ Q3 revenue of $14.6B vs. $12.7B expected
→ $2.8B operating income vs. a loss a year ago
→ Street avg. target ~$244, about 2x today’s price
Market is trading the headlines. I’m trading the numbers.
Riders don’t care who or what is driving. They want the fastest, easiest ride, and $UBER owns that front door.
Why this matters for $UBER:
→ AV owners need utilization, and Uber already has the riders. Idle robotaxis lose money.
→ Uber isn’t betting on one supplier. It has 30+ AV partners and plans to spend $10B+ building out its autonomous network.
→ If the AV makers are interchangeable, the demand aggregator keeps the pricing power.
The bear case: Waymo’s exclusivity with Uber in Austin and Atlanta ends in 2028, and Waymo is already working with Lyft in Nashville. If AV owners go direct, Uber’s moat gets thinner.
My take: Uber is the toll booth in the AV era, but only if it keeps winning on demand. Not financial advice.
$CRCL earnings this week. The bull case in 3 lines:
→ Record $76.5B avg USDC circulation, up ~25% YoY
→ 50% adj. EBITDA margin, with FY26 RLDC margin guided up to 41.7-43.7%
→ Other revenue guided to $310-330M as Arc and CPN scale
Stablecoin growth, expanding margins, and a new platform layer with the stock well off its highs. I’m adding into this print.
Markets hate uncertainty, and the midterms are the last big dose on the calendar.
Since 1950, the S&P 500 has been higher 12 months after every midterm. 19 for 19.
Whoever wins, I expect the path of least resistance to be up until we see real cracks in the AI trade.

I will be adding to $PLTR before the close today. Earnings tonight.
Revenue has beaten by 4-8% four quarters straight. Q3 guide: $2.16B. FY guide: $8.15B+, with US commercial guided to 134%+ growth.
Palantir guides low and delivers high. I’m betting that continues.
$AAPL reports today, John Ternus’ first print as CEO.
Guide: revenue +9-11% ($111.7-113.7B) despite a ~2.5pt FX headwind and supply constraints.
Apple has been beating its own guide. Setup favors another clean one, I will always be an owner of Apple.
The S&P 500 has been higher 12 months after the midterms in every midterm cycle since 1950.
Red wave, blue wave, split Congress, the market has historically cared less about who wins than about the uncertainty clearing.
I’m bullish into the other side of this one.

$UBER earnings this week. The bull case in 3 lines:
→ Gross bookings guided at $58-60B, up ~20% YoY
→ Adj. EBITDA guided near $2.9B
→ $2.3B ezCater deal pushes further into delivery
Growth, profits, and buybacks at a mid teens multiple.
I’m not selling into this print I'm buying more.
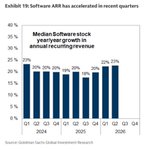
I am adding a lot of money to my Snowflake $SNOW position right here. Retail sees short-term volatility and hesitates. Businesses absolutely demand to know their data is perfectly safe when using AI models, and Snowflake is positioned to dominate that future. 🧵
The fundamental math is undeniable. While analysts panic over consumption trends, Snowflake just printed a massive 37% year over year jump in product revenue, hitting nearly $1.49 billion for the quarter. Even more impressively, they are accelerating that top line growth while simultaneously expanding their operating margins by over 400 basis points.
I honestly feel like Uber $UBER is the single best valued company on the market right now. Retail asks how they will survive Waymo or Tesla's Cybercabs taking full market share. People just want the cheapest, fastest, and easiest ride. They do not care what physical car actually picks them up. 🧵
The fundamental math is undeniable. Their valuation is an absolute steal right now, trading at a ridiculously low forward P/E ratio of just 14.3. You are buying the undisputed sovereign of global mobility, with 183 million monthly active users already opening the app every single day, at a massive discount compared to heavily inflated mega cap tech multiples.
The takeaway: You do not fade a global logistics monopoly when $UBER has the capital discipline to avoid the hardware wars and instead force every AV manufacturer to eventually plug into their marketplace.
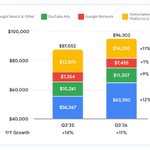
Reddit $RDDT is still exactly what I thought it was. Retail is absolutely panicking over the headlines that they are locking out logged-out users because Google AI is choking their search traffic. Who honestly cares? 🧵
The fundamental math is undeniable. Even though passive search traffic took a hit, the actual demand for $RDDT underlying data has never been higher. Forcing users to log in directly increases average revenue per user (ARPU) while simultaneously forcing hyperscalers to negotiate massive licensing deals if they want access to the agentic AI training pipeline.