

Founder & engineer, Lifted Holdings. Guides on payments, merchant fees & building fintech with AI. DM "STATEMENT" for a free statement markup.
Belvidere, TN
Joined November 2021
- Tweets966
- Following386
- Followers4.8K
- Likes807






Pinned Tweet
Most business owners have never had someone walk them through their card processing statement line by line.
I'll do it free. DM me the word STATEMENT, send a photo of your latest one, and I'll mark up every fee: what it is, whether it's normal, and what's padding.
No call. No obligation. Just a clear read on what you're paying.
Builders: what's one task you stopped giving your AI coding agent after it went wrong once?
Not the stuff it's bad at in general. The one time it cost you enough that you took that job back for good.
The one number worth pulling off your processing statement: your effective rate.
Total fees for the month ÷ total card sales for the month.
Example: $1,180 in fees on $40,000 in sales is 2.95%.
It's the only fair way to compare quotes that are priced differently. A flat rate, an "interchange plus" quote and a tiered one all collapse into one number.
What it hides:
• Your card mix. More rewards and business cards push it up even if nothing about your pricing changed.
• Your average ticket. The per-sale part of the fee (the 10¢ or 30¢) hits a $6 sale far harder than a $600 one.
• How you take cards. Keyed-in and online sales usually cost more than tapped or dipped ones.
• Slow months. Monthly fees stay the same when sales drop, so the rate jumps.
So track it for 3 months, not 1. A single month can mislead you in either direction.
And when someone quotes you a lower rate, ask them to show it against your actual statement, not a sample one.

Every "simple" payments feature request ends with the word "except."
Refund it, except it already settled.
Bill them monthly, except the card expired.
Split it evenly, except one of them paid cash.
Codex CLI 0.164 added credential masking for some remote shell commands.
Good. But hiding a secret in what the agent prints isn't the same as the agent not having it.
If it can read the key, it can use the key. Scope the key, not just the log.
Owners: what's the one report you actually open every day?
Sales by hour, the deposit, voids and refunds, tips, something else?
And which report came with your POS that you've never once opened?
Meta on Muse: about a quarter of users have it shop, and the average order is over $200.
Best detail from the call: in week one, Meta had to get Stripe to raise credit limits.
Agent shopping didn't hit a model problem first, or a checkout problem. It hit a limit.
An appeals court just threw out the Fed's cap on big-bank debit swipe fees: 21¢ + 0.05% per sale.
The ruling: only costs tied to a single transaction count, not a bank's fixed overhead.
Merchants won the argument. What it does to your statement depends on the Fed's next move.

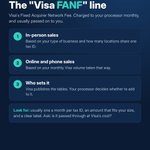
Payments teardown #3: the "Visa FANF" line on your statement.
What it is: Visa's Fixed Acquirer Network Fee. Visa charges it to your processor every month, and most processors pass it on to you.
How it's figured:
• In-person sales: by your type of business and how many locations you have under one tax ID.
• Online and phone sales: by how much Visa volume you run that way each month.
• Do both and you can owe both parts.
Who sets it: Visa publishes the fee tables. Your processor decides whether to pass it through at cost or add to it.
What to look for:
1. Usually one FANF a month per tax ID, not one per terminal.
2. An amount that fits your size. A one-location shop shouldn't be paying like a chain.
3. A clear label. A vague "network fee" with no breakdown is worth a question.
The question to ask: is my FANF passed through at Visa's cost?

Every AI agent shopping demo ends at "order placed."
Real commerce starts at "this isn't what I ordered."
Returns, partial refunds, the wrong size. That's the part nobody's demoing yet.
Owners: what's a payments lesson you only learned after it cost you money?
A chargeback, a held deposit, a fee nobody mentioned, a contract you couldn't get out of.
The expensive lessons are the ones most worth passing on.
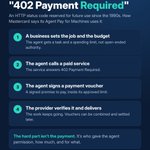
Builders: your agent hits a permission check and gets told no. What should it do next?
A) Stop and ask a human
B) Try another way
C) Log it and move on
B is how you end up with an agent calling the bank's support line.
In payments, an unexpected success deserves the same investigation as an unexpected failure.
Failures tell you something broke. Successes just let it keep happening.
Same-Day ACH has existed since 2016, and a single payment can be up to $1 million.
Plenty of providers still settle bank payments next-day or slower by default.
If you take ACH, ask which one you're getting and what same-day costs.
GitHub CLI can now sign you in with tokens that expire within hours and refresh themselves.
Scripts that saved a token once will break.
Good. A credential that never expires is a leak that hasn't been found yet.
Owners: your card reader dies at your busiest hour today. What's the backup plan?
Be honest. "Panic" counts as an answer.
Sezzle applied to the OCC for a national bank charter this week.
Most fintechs learn it eventually: the partner bank makes the hardest calls. Freezes, limits, what you're allowed to launch.
A charter is how you stop asking.
Anthropic just handed Agent Skills to the Linux Foundation's Agentic AI Foundation. A million skills published, nearly 280 million installs.
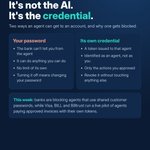
A skill is a file your agent follows with your permissions.
Read one before you install it, the same way you'd read a script.
Switching card processors? Moving the money is the easy part. These are the parts that bite.
1. Stored cards. If you bill customers on file, ask whether the old processor will transfer your saved cards to the new one. Some will, some won't, and re-collecting cards from every customer is painful.
2. Recurring billing. Subscriptions and payment plans live in the old system. List every one before you move.
3. The overlap. Keep the old account open until the last deposit lands and the refunds and chargebacks you expect have cleared.
4. Terminals. Some won't work with a new processor. Check before you sign, not after.
5. The old contract. Find the term, the early termination fee and the cancellation steps first. Cancel in writing.
6. Your statement name. Set it up on the new account so customers still recognize you.
Go slow and boring. Boring switches are the good ones.
Look up how your business shows on a customer's card statement.
If they see something like "PAY*JMS HLDGS 8885551212" instead of the name on your sign, some will dispute a charge they really made.
Your processor can usually change that name. Ask.
