

25-year US Treasury Manager & Strategist | ex-President of Kessler | 83% accuracy last 3-years, 93% over the last year (8/2026) | Founder, Lantern Capital
Denver, CO
Joined September 2010
- Tweets1.9K
- Following189
- Followers1.4K
- Likes3.9K


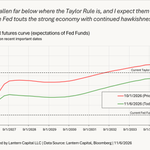
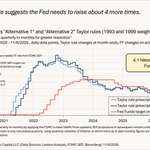


Wow! I thought Waller’s idea of 50bps in December wasn’t reasonable, but Alberto Musalem effectively just said he wants four hikes over the next three meetings (“before spring 2027”). Taylor rule is asking for four (~5 at the end of the month) and Musalem is the first to fill it.

Two misunderstandings today. First, 330.750 is a good interpolation for October 2025 core CPI, 53% of the way between Sep and Nov. like core PCE. This brings yoy% up to 2.77% from 2.57% and a big Taylor rule shift, but well known ahead of time.
Second, the Fed isn't raising 50bps in December. Waller is swerving all over the road from being too dovish to too hawkish. Last week the FOMC narrative was gradual raising and still is. If anything changed, it would be to raise every meeting, not 50bps.
1
6
404
The tertiary trend of lower rates happened like I thought, but it is getting stretched now. Data is still strong, the Fed is still hawkish and I think tomorrow’s labor report will result in a lower unemployment rate, implying a wider Taylor gap. I think today is probably the tertiary trend yield low, with rates about to head back up. xitter.gq/EricWHickman/status/21…

For tomorrow, I think it will be a unanimous hold. September’s hot CPI was only evidence of a $13 rise in the average price of oil, biggest since March. All FOMC members want cover from “the Fed tried to influence the election”. From Williams’ comments (1 more raise) and higher credit spreads, I think some are beginning to sniff the economic turn.
Not unreasonable to let higher rates cook to hopefully prevent having to raise only to soon lower (behind doves’ reticence to hike in my view). 8 months and 150bps of higher rates is a cocktail for a soon break in the economy, like the four trends before it in the last three years. I doubt the proverbial “brake” needs to be pressed any harder at this point for that to come. The Fed is smart if they play the repeating cycle this way.
1
8
700
There isn't any reason for the Fed to be more hawkish this week. September was clearly a supply shock month, but underlying inflation is still 2.5%-3.0% from demand.

The broad stock market isn't really doing much. AI is thought to be everything because it is shiny and new. Tech came down without the market earlier this year. It will do it again. The economy is too strong now for a broad sustained business cycle decline.

Today's Beige Book marks three in a row (4.5 months) with no districts contracting. One district, Chicago (about 10% of the country's GDP) was downgraded from up to flat but the rest were the same. The economy remains STRONG.

6
571
If there were a month of inflation to look through from a supply shock, it is this report because average oil prices rose $7.5, the most since March. Core services isn't oil-free. That's why the 2-year has fallen 10+ bps from the initial knee-jerk.

1
5
435
The steepening over the last two weeks has worked out a tension in the curve, it isn't because anyone is abandoning Treasuries or the Fed isn't hawkish enough.

The Fed's hawkishness won't change from today's report. The unemployment rate rose from 4.14% to 4.18% and lowered the amount the Fed is behind the curve from 3.4 hikes to 3.2. 3mo. avg. payrolls is 51k, steady and above most estimates of breakeven (mine: 34k). That's the extent of it. Jobs day<PCE day.


Rate expectations have fallen down to the new PCE methodology Taylor rule today (3.4 hikes behind, not 5.4). I think rates will fall for a few weeks (tertiary trend) before rising to new secondary trend highs and then yields will fall into the next recession scare (and maybe even a mild recession).

2
10
1,253
Higher rates are showing up a little in G-7 credit now. For the US it's about 5bps since mid-September. The US, Japan, and Germany are mostly moving in sympathy to Europe because US swap spreads show no concern.

1
6
630

