

Husband, dad, investor, sports fanatic!!
Joined February 2021
- Tweets3.3K
- Following171
- Followers3.6K
- Likes19.9K




I think this is WAY underestimating it. What way way underestimating

Gartner predicts the average Fortune 500 enterprise will have more than 150,000 agents by 2028, up from fewer than 15 in 2025. Jacob Leverich on what that does to observability, at #SnowflakeExpedition.
"How will you make sure you can understand what's happening, and whether it's delivering value?" Telemetry belongs with the data the business owns.
Check out the key takeaways👇🧵

FinallyFoolin retweeted

The market is treating a Dem sweep as an existential threat to AI infrastructure. It’s not.
Data centres can (and already are) being built outside the US. Hyperscalers have major footprints and active expansions across Europe, Asia, the Middle East, Canada and LatAm. Power, speed of permitting and cost drive site selection more than pure US policy.
If domestic buildouts slow, capital will simply reallocate. Global AI compute demand doesn’t disappear because Northern Virginia or Texas gets harder to permit. Latency-sensitive training prefers concentrated clusters, but inference, regional capacity and a large share of workloads work fine abroad.
The nutty part is the indiscriminate selling of the whole growth stock complex. High-quality, FCF-positive AI names and infrastructure software companies with multi-year visibility are getting lumped in with pure high-beta, negative-FCF builders that actually do have financing and execution risk.
Policy friction in one country ≠ the end of the AI buildout.
International optionality is real.
FinallyFoolin retweeted

$ALAB
With Hulk smash numbers. Yes narrative winds are swirling but hard numbers don’t lie (at least for the next few Qs)
Again, no slow down in AI. We are still early

Very strong Q3 results and Q4 guidance from $ALAB ...
Q3 revs of $584.9M vs $548.5M est
Q3 revs up +49% QoQ
Q3 revs up +154% YoY
Q3 eps of $1.32 vs $1.19 est
Q3 eps up +65% QoQ
Q3 eps up +169% YoY
Q3 net income margin of 41.6% vs 38.3% in 2025 Q3
Guidance:
Q4 revs of $730-750M vs $655.7M est
Q4 revs guidance (midpoint) implies +27% QoQ
Q4 revs guidance (midpoint) implies +174% YoY (revenue growth is accelerating)
Q4 eps guidance of $1.62-1.66 vs $1.42 est
Q4 eps guidance (midpoint) implies +183% YoY growth (eps growth is accelerating)
Holy shit that Q4 guidance is strong!!!!
No idea how $ALAB is red/flat AH on this report, the stock should be up double digits.
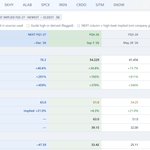
Coming into this Q3 report... the sell side was looking for $6.15 of EPS over the next 12 months... I think $ALAB does at least $7.00 and perhaps $7.30 or better if we see more margin expansion
$ALAB got down to $215 AH, now trading at $232... if we use those lows... there's a chance the stock was trading at ~30x NTM EPS for one of the best growth stories in the entire market... literally trading at a NTM PEG ratio of 0.25x
FinallyFoolin retweeted

$ALAB delivered 😏
• Revenue $585M vs Est. $551M (+154% YoY)
• EPS $1.32 vs Est. $1.19
• Operating Income $262M vs Est. $238M
• Gross Margin 72% vs. Est. 60%
Q4 Guidance
• Revenue $740M vs Est. $656M (+174% YoY)
• EPS $1.64 vs Est. $1.42
• Operating Income $336M vs Est. $287M
• Gross Margin 72% vs. Est. 71%

FinallyFoolin retweeted

$ALAB reports after the close today... the implied move is 12-18% but given the current market environment, anything is possible.
$ALAB used to be one of the more expensive ai/semi stocks... less than 6 months ago it was trading at ~100x NTM EPS (with insane growth & margins)... after they report earnings today the stock will likely be trading at less than 35x NTM EPS with EPS growing at 120-160% YoY for the next 12 months.
$ALAB is firing on all cylinders right now which is why revenues are not only growing triple digits YoY but their growth is accelerating... not to mention they're going to report at least 40% QoQ growth in Q3 and then another 25-35% QoQ in Q4.
Good luck to the bulls.