

AI summaries of companies' earnings. Not advice. AI can make mistakes Articles with charts: https://xitter.gq/t.co/XPvKIyrLjC
Joined May 2023
- Tweets17.6K
- Following0
- Followers11.6K
- Likes1.7K


$PLOW Q3 2026 earnings: Douglas Dynamics snowplow profit doubles, but upfitting earnings fall
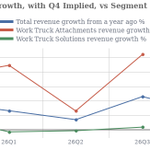
Douglas Dynamics, a maker of commercial snowplows and truck equipment, delivered record third-quarter profit in its snowplow business while earnings fell at its truck upfitting division. Total revenue rose 34% from a year ago to $218 million, and profit per share excluding one-offs more than doubled to $0.98 as factories shipped the second half of pre-season orders. Finance chief Sarah Lauber lifted the bottom of the full-year outlook, which by our math leaves fourth-quarter profit per share nearly flat against last year's early winter storms.
• Pre-season Attachments sales (Q2+Q3): $𝟐𝟓𝟎.𝟖𝐌 (+42% from a year ago by our math)
• Third-quarter revenue: $𝟐𝟏𝟖.𝟎𝐌 (+34.5% from a year ago)
• Profit per share, excluding one-offs: $𝟎.𝟗𝟖 ($0.40 a year ago)
• Full-year revenue outlook: 𝐑𝐚𝐢𝐬𝐞𝐝 𝐥𝐨𝐰 𝐞𝐧𝐝 $𝟓𝐌 (middle of the range: 20% growth)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🟢 Bullish
The story got better because snowplow and parts demand across the full pre-season grew 42% by our math, proving the third-quarter jump was more than a shipping calendar shift. High factory volume lifted the snowplow profit margin to 25%, well above management's 20% target. The bad news: profit in the Work Truck Solutions division fell 19% even as city orders pushed its sales up 3%, and seasonal borrowing on the credit line reached $96 million.
The question now is whether dealers will keep ordering snowplows and parts once the company laps last winter's heavy snowfall. Either last winter started a multi-year equipment replacement cycle, or a return to normal weather will pull demand back down in 2027. Fourth-quarter snowplow reorders and dealers' winter inventory levels will tell.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐒𝐧𝐨𝐰𝐩𝐥𝐨𝐰 𝐒𝐡𝐢𝐩𝐦𝐞𝐧𝐭 𝐓𝐢𝐦𝐢𝐧𝐠 𝐚𝐧𝐝 𝐏𝐚𝐫𝐭𝐬 𝐋𝐢𝐟𝐭𝐞𝐝 𝐒𝐚𝐥𝐞𝐬
Work Truck Attachments makes commercial snowplows, sand and salt spreaders, and truck-mounted cranes. Sales in the division rose 78.4% from a year ago to $121.5 million. Because Douglas Dynamics shipped its pre-season snowplow orders in a "close to a 50% to 50% split between the second and third quarters" rather than last year's 60-to-40 split, combining the two quarters gives the clean comparison.
• Combined Q2 and Q3 Attachments sales: $250.8 million, up 42.3% from a year ago by our math
• Q3 share of pre-season Attachments sales: 48.4% by our math, against 38.6% last year
• Year-to-date parts and accessories shipments: already "exceeded the previous annual record set in 2025"
The combined 42.3% jump shows that dealer demand after last winter's heavy snow did not just shift between quarters. Adding Venco Venturo, the crane maker bought last November, and record orders for high-margin replacement parts pushed underlying demand well above last year.
What to watch: fourth-quarter Attachments sales against last year's $83.1 million. That reading will show whether dealers keep ordering whole plows and parts when they lap last year's early winter storms.
🟢🟢 𝐅𝐚𝐜𝐭𝐨𝐫𝐲 𝐕𝐨𝐥𝐮𝐦𝐞 𝐋𝐢𝐟𝐭𝐞𝐝 𝐭𝐡𝐞 𝐆𝐫𝐨𝐬𝐬 𝐌𝐚𝐫𝐠𝐢𝐧
Chief executive Mark Van Genderen said the nine-month results show "the earnings power of our business" when factories run full. In the third quarter, gross margin rose 3.9 percentage points from a year ago to 27.4%, and operating margin climbed 5.7 percentage points to 14.3%.
Two expense lines drove the gain. Cost of sales — the cost of steel, parts and factory labor — fell 3.9 percentage points of revenue to 72.6%, because higher snowplow production spread fixed plant costs over more units and shifted the mix toward profitable replacement parts. Selling, general and administrative expense — overhead and office pay — dropped 1.5 percentage points of revenue to 12.4%.
Inside the Attachments division, Adjusted EBITDA margin (profit before interest, taxes, depreciation, amortization and one-offs) jumped 9.5 percentage points to 24.8%. That beat the 20% threshold management previously targeted for the quarter.
What to watch: consolidated Adjusted EBITDA margin in the fourth quarter, which the full-year outlook puts at 13.7% by our math. A higher reading would show that factory efficiency can offset a slower parts mix.
🟢 𝐓𝐡𝐢𝐫𝐝 𝐎𝐮𝐭𝐥𝐨𝐨𝐤 𝐑𝐚𝐢𝐬𝐞 𝐋𝐞𝐚𝐯𝐞𝐬 𝐑𝐨𝐨𝐦 𝐟𝐨𝐫 𝐖𝐢𝐧𝐭𝐞𝐫
Finance chief Sarah Lauber raised the bottom of the full-year outlook for a third straight quarter while keeping the top end unchanged. The truck equipment maker lifted the floor on revenue by $5 million, on Adjusted EBITDA by $3 million, and on profit per share excluding one-offs by $0.10.
Through nine months, Douglas Dynamics has already earned $2.56 per share excluding one-offs, passing its previous full-year record from 2019. By our math, the middle of the new $3.00 to $3.40 outlook leaves $0.64 per share for the fourth quarter, up 3.2% from a year ago on implied fourth-quarter sales growth of 17.6%.
What to watch: fourth-quarter profit per share excluding one-offs against the implied $0.64. Because management sets fourth-quarter plans assuming average snowfall, normal winter weather should test whether the new range is still cautious.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐂𝐨𝐦𝐦𝐞𝐫𝐜𝐢𝐚𝐥 𝐖𝐞𝐚𝐤𝐧𝐞𝐬𝐬 𝐒𝐭𝐢𝐥𝐥 𝐇𝐮𝐫𝐭𝐬 𝐓𝐫𝐮𝐜𝐤 𝐔𝐩𝐟𝐢𝐭𝐭𝐢𝐧𝐠 𝐏𝐫𝐨𝐟𝐢𝐭
Work Truck Solutions attaches plows, dump bodies and storage gear onto trucks for cities and commercial fleets. "Although inconsistent commercial demand has impacted profitability, the segment continues to perform well overall, supported by sustained municipal demand and a positive outlook," Van Genderen said.
The profit numbers cut against his reassurance. While division sales edged up 2.7% from a year ago to $96.5 million on city orders, its Adjusted EBITDA fell 19.0% to $7.8 million. The division's Adjusted EBITDA margin dropped 2.1 percentage points from a year ago to 8.1%, the lowest reading in five quarters.
That drop follows a 20.5% profit decline in the second quarter. City orders are keeping the shops busy, but they carry lower margins or cannot cover the fixed costs left behind when commercial fleet customers pause orders. Nine-month division sales of $258.7 million sit slightly below last year.
What to watch: fourth-quarter Solutions sales and profit margin. To hit management's goal of full-year sales growth and low-double-digit margins, the division must beat last year's $101.5 million fourth quarter and lift its margin above 10%.
🔴 𝐔𝐧𝐩𝐚𝐢𝐝 𝐁𝐢𝐥𝐥𝐬 𝐚𝐧𝐝 𝐈𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 𝐏𝐮𝐬𝐡𝐞𝐝 𝐃𝐞𝐛𝐭 𝐔𝐩
Douglas Dynamics builds snowplows in the summer and collects cash from dealers in the winter, so it always uses cash through September. This year, the seasonal cash drain is much larger because the company built "increased working capital to support demand across both segments".
• Nine-month operating cash outflow: $47.5 million, compared with $21.2 million a year ago
• Third-quarter free cash outflow: $26.2 million, more than double last year's $11.4 million outflow
• Short-term credit line borrowings: $96.0 million, up from $5.0 million at year-end and $65.0 million a year ago
Total debt excluding truck floorplan loans rose 58.1% since December to $233.3 million by our math, while cash sits at $5.5 million. The company relies on fourth-quarter collections to pay down its credit line.
What to watch: fourth-quarter operating cash flow and year-end short-term borrowings. A slow collection quarter would leave debt elevated heading into 2027.
🔴 𝐖𝐞𝐚𝐭𝐡𝐞𝐫 𝐚𝐧𝐝 𝐂𝐨𝐬𝐭 𝐑𝐢𝐬𝐤𝐬 𝐂𝐚𝐫𝐫𝐲 𝐈𝐧𝐭𝐨 𝐖𝐢𝐧𝐭𝐞𝐫
Four standing risks from prior quarters remain open or received no new numbers in the earnings release.
• Winter weather dependency: Lauber noted fourth-quarter Attachments results are "influenced by the timing and severity of winter weather, which can create meaningful variability in year-end results", and 2027 will lap a winter that was 26% above average.
• Raw material and freight inflation: the release cites tariff-driven steel costs and fuel prices tied to the conflict in Iran, which will be readable in the quarterly filing's margin bridge.
• Paused commercial fleet orders: the release gave no dollar size for the commercial slowdown inside Solutions; the conference call is the next check.
• Municipal backlog dollars: management did not disclose the dollar backlog or lead times in the release; the call and filing will show if city orders stayed near record levels.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐎𝐡𝐢𝐨 𝐅𝐚𝐜𝐢𝐥𝐢𝐭𝐲 𝐎𝐩𝐞𝐧𝐬 𝐒𝐨𝐨𝐧 𝐭𝐨 𝐒𝐞𝐫𝐯𝐞 𝐂𝐢𝐭𝐢𝐞𝐬
Douglas Dynamics is expanding its truck upfitting footprint to handle city contracts. Following the opening of its Missouri facility last quarter, Van Genderen said the company expects to "begin operations at our new Ohio facility in the coming weeks". Nine-month capital spending rose $3.1 million to $11.2 million, or 2.0% of sales by our math, matching the full-year plan of 2% to 3% of sales.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐬 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞, 𝐧𝐞𝐭 (𝟐𝟔𝐐𝟑): $𝟐𝟏𝟕.𝟖 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Uncollected customer bills rose 25.6% from a year ago by our math andmore than doubled from $97.6 million at year-end. Accounts receivable — money dealers owe for shipped equipment — climbed alongside the 78.4% jump in third-quarter snowplow sales. Collecting these bills in the fourth quarter is what turns seasonal paper profits into cash.
𝐂𝐨𝐦𝐦𝐨𝐧 𝐬𝐭𝐨𝐜𝐤 𝐫𝐞𝐩𝐮𝐫𝐜𝐡𝐚𝐬𝐞𝐬 (𝟐𝟔𝐐𝟑): $𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
By our math, the snowplow maker bought back no shares in the third quarter, as nine-month repurchases stayed at $6.0 million, unchanged from the first half. After spending $3.0 million in each of the first two quarters, management paused buybacks during its peak seasonal borrowing quarter while paying $6.9 million in dividends.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟔 𝐍𝐞𝐭 𝐒𝐚𝐥𝐞𝐬: $𝟕𝟕𝟎–𝟖𝟎𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠅 raised from $765–805 million
Raised. Management lifted the bottom of the range by $5 million, putting the middle of the range at $787.5 million, or 20.0% growth for the year by our math. That leaves $217.0 million for the fourth quarter, up 17.6% from a year ago vs 34.5% in the third quarter. It is the third raise this year, and each is smaller than the last: +$37.5M, +$12.5M, +$2.5M at the middle.
𝐅𝐘𝟐𝟔 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀: $𝟏𝟐𝟑–𝟏𝟑𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠅 raised from $120–135 million
Raised. The company increased the floor by $3 million, moving the middle of the range up $1.5 million to $129.0 million, or 31.8% full-year growth by our math. That implies $29.7 million in the fourth quarter, up 15.1% from a year ago at a 13.7% margin, down from 17.4% in the third quarter. The three raises this year moved the middle by +$7.5M, +$10.0M, and +$1.5M.
𝐅𝐘𝟐𝟔 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐃𝐢𝐥𝐮𝐭𝐞𝐝 𝐄𝐏𝐒: $𝟑.𝟎𝟎–𝟑.𝟒𝟎 ⇘ decelerating
🠅 raised from $2.90–3.40
Raised. The low end rose by $0.10, taking the middle of the plan to $3.20 per share, up 42.9% for the year by our math. With $2.56 already earned through September, the middle of the range leaves $0.64 for the fourth quarter, up 3.2% against last year's $0.62. Across three raises this year, the middle moved up by $0.25, $0.35, and $0.05.
𝐅𝐘𝟐𝟔 𝐄𝐟𝐟𝐞𝐜𝐭𝐢𝐯𝐞 𝐓𝐚𝐱 𝐑𝐚𝐭𝐞: 𝟐𝟒%–𝟐𝟓% ⇒ stable
🠆 unchanged from 24%–25%
Unchanged. The full-year tax rate plan stays at 24% to 25% for a fourth straight quarter. The effective tax rate was 25.4% in the third quarter and 24.4% through the first nine months by our math, sitting right inside the targeted range.
𝐅𝐘𝟐𝟔 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐄𝐱𝐩𝐞𝐧𝐝𝐢𝐭𝐮𝐫𝐞𝐬: 𝟐%–𝟑% 𝐨𝐟 𝐍𝐞𝐭 𝐒𝐚𝐥𝐞𝐬 ⇗ accelerating
🠆 unchanged from Towards the higher end of 2% to 3% of Net Sales
Unchanged. Capital spending is still planned at 2% to 3% of revenue, though the release dropped last quarter's note that spending would sit near the top of that band. Through nine months, capital spending of $11.2 million was 2.0% of sales by our math, leaving room for fourth-quarter spending as the new Ohio upfit facility opens.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐚𝐭 𝐰𝐚𝐬 𝐬𝐧𝐨𝐰𝐩𝐥𝐨𝐰 𝐬𝐚𝐥𝐞𝐬 𝐠𝐫𝐨𝐰𝐭𝐡 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐕𝐞𝐧𝐜𝐨 𝐕𝐞𝐧𝐭𝐮𝐫𝐨?
Work Truck Attachments sales rose 78.4% in the third quarter and 42.3% across the pre-season, but both figures include Venco Venturo, acquired in November 2025. Without Venco's standalone revenue, investors cannot separate underlying snowplow growth from the acquisition.
𝐖𝐡𝐲 𝐝𝐢𝐝 𝐒𝐨𝐥𝐮𝐭𝐢𝐨𝐧𝐬 𝐩𝐫𝐨𝐟𝐢𝐭 𝐟𝐚𝐥𝐥 𝟏𝟗% 𝐨𝐧 𝐡𝐢𝐠𝐡𝐞𝐫 𝐬𝐚𝐥𝐞𝐬?
Work Truck Solutions grew revenue 2.7% to a third-quarter record of $96.5 million, yet Adjusted EBITDA fell 19.0% and margin dropped 2.1 percentage points to 8.1%. Management blamed inconsistent commercial demand, but did not quantify the commercial drop or why municipal volume failed to protect margins.
𝐖𝐡𝐚𝐭 𝐢𝐬 𝐭𝐡𝐞 𝐝𝐨𝐥𝐥𝐚𝐫 𝐛𝐚𝐜𝐤𝐥𝐨𝐠 𝐢𝐧 𝐖𝐨𝐫𝐤 𝐓𝐫𝐮𝐜𝐤 𝐒𝐨𝐥𝐮𝐭𝐢𝐨𝐧𝐬?
Management has described municipal backlog as near the 2022 record with production dates into 2027, but has not given a dollar figure since the $348 million reported at the start of 2025. A dollar number and municipal share would show how well city orders cover commercial weakness.
𝐃𝐢𝐝 𝐃𝐨𝐮𝐠𝐥𝐚𝐬 𝐃𝐲𝐧𝐚𝐦𝐢𝐜𝐬 𝐩𝐚𝐮𝐬𝐞 𝐬𝐡𝐚𝐫𝐞 𝐛𝐮𝐲𝐛𝐚𝐜𝐤𝐬 𝐭𝐨 𝐜𝐨𝐧𝐬𝐞𝐫𝐯𝐞 𝐜𝐚𝐬𝐡?
After repurchasing $3.0 million of stock in both the first and second quarters, nine-month cash flows show zero buybacks in the third quarter while short-term debt reached $96.0 million. Management has not said whether the pause is seasonal or a shift in capital plans.

$IAUX Q3 2026 earnings: i-80 Gold hits plant milestones, but stockpiling delays cash sales
i-80 Gold, a Nevada gold miner rebuilding its underground mines and processing plant, is producing more gold than it can turn into cash. Third-quarter revenue edged up 2% to $33 million only because higher gold prices offset a 17% drop in ounces sold. Chief executive Richard Young published the first formal gold reserves at Granite Creek and kept the Lone Tree plant rebuild on track for late 2027, while heavy drilling widened the net loss excluding one-offs to $48 million.
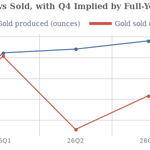
• Gold produced: 𝟏𝟏,𝟔𝟖𝟓 𝐨𝐳 (-6.0% from a year ago (+5.3% from Q2))
• Gold sold: 𝟕,𝟕𝟒𝟒 𝐨𝐳 (10,300 oz held in inventory and processing)
• Net loss, excluding one-offs: $𝟒𝟖.𝟐𝐌 ($34.3M loss a year ago)
• 2026 production outlook: 𝐋𝐨𝐰𝐞𝐫𝐞𝐝 (steered to lower half of 40,000–50,000 oz)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because construction milestones at Lone Tree and Granite Creek balanced out ongoing processing bottlenecks and labour pressures. The good news: declaring 556,500 ounces of reserves at Granite Creek validates the mine plan and lets the company capitalize future tunnel costs. One caution: the miner steered 2026 gold production to the lower half of its plan and will stockpile sulfide ore throughout 2027 rather than pay an outside processor, delaying cash inflows until Lone Tree opens.
The question now is whether the $411 million cash balance can cover both the Lone Tree rebuild and a year of stockpiling unpaid ore in 2027. Either existing cash and current credit lines bridge the gap to 2028, or the miner must draw uncommitted debt and new stockpile loans. The 2027 capital budget and financing terms in the full-year report will settle it.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐆𝐫𝐚𝐧𝐢𝐭𝐞 𝐂𝐫𝐞𝐞𝐤 𝐒𝐭𝐮𝐝𝐲 𝐃𝐞𝐜𝐥𝐚𝐫𝐞𝐬 𝐑𝐞𝐬𝐞𝐫𝐯𝐞𝐬 𝐚𝐧𝐝 𝐂𝐮𝐭𝐬 𝐄𝐱𝐩𝐞𝐧𝐬𝐞𝐬
i-80 Gold is a Nevada gold miner rebuilding its underground mines. In September chief executive Richard Young said that "Granite Creek underground announced maiden mineral reserves", which means engineers confirmed how much gold the company can profitably extract. The engineering report, called a feasibility study, established 556,500 ounces of gold reserves grading 7.87 grams per tonne and an 8.5-year mine life.
The reserve grade is lower than earlier preliminary estimates, but infill drilling closed gaps in the rock and increased the total gold resource by 229% to 859,500 ounces. Because the mine now has formal reserves, the miner will record future qualifying tunnel building costs as long-term assets on its balance sheet rather than immediate expenses, which will narrow reported losses.
What to watch: Granite Creek pre-development expense in the fourth quarter. A sharp drop from this quarter's $5.5 million will show how much spending moves off the income statement.
🟢 𝐋𝐨𝐧𝐞 𝐓𝐫𝐞𝐞 𝐏𝐥𝐚𝐧𝐭 𝐚𝐧𝐝 𝐀𝐫𝐜𝐡𝐢𝐦𝐞𝐝𝐞𝐬 𝐒𝐭𝐚𝐲 𝐨𝐧 𝐒𝐜𝐡𝐞𝐝𝐮𝐥𝐞
The company's plan to produce 150,000 to 200,000 ounces of gold a year in 2028 depends on building its Archimedes underground mine and rebuilding its Lone Tree processing plant. Both projects hit their third-quarter targets. Workers finished bulk demolition at Lone Tree and awarded 74% of equipment and service packages by value, keeping the plant on track to pour its first gold in late 2027.
At Archimedes, crews dug 760 meters of underground tunnels during the quarter and finished the first ventilation shaft. The Nevada miner remains on schedule to mine its first gold there before the end of 2026. Labour costs at Lone Tree are running 5% to 10% above initial estimates, but the $430 million budget has absorbed the increase using 20% of its contingency fund.
What to watch: the general contractor award at Lone Tree and first gold mined at Archimedes in the fourth quarter. Hitting both keeps the late-2027 plant startup on track.
🟢 𝐇𝐢𝐠𝐡𝐞𝐫 𝐆𝐨𝐥𝐝 𝐏𝐫𝐢𝐜𝐞𝐬 𝐋𝐢𝐟𝐭𝐞𝐝 𝐆𝐫𝐨𝐬𝐬 𝐏𝐫𝐨𝐟𝐢𝐭
Rising market prices for gold carried the income statement while mine shipments lagged. The miner sold 7,744 ounces of gold in the third quarter, down 17.3% from 9,368 ounces a year earlier. However, its average realized gold price — the price it received per ounce sold — jumped 23.4% to $4,211 per ounce.
Because the higher selling price outweighed the drop in volume, total revenue rose 2.2% to $32.7 million. Gross profit climbed from $3.1 million to $5.0 million, lifting gross margin by 5.4 percentage points to 15.1%. That price cushion helps fund surface work, though royalty and gold prepayment deals from earlier this year will cap some price gains starting in 2028.
What to watch: average realized gold price and gross profit in the fourth quarter. If gold prices hold above $4,200 per ounce, gross profit will rise as stockpiled ore clears.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐎𝐮𝐭𝐬𝐢𝐝𝐞 𝐏𝐫𝐨𝐜𝐞𝐬𝐬𝐢𝐧𝐠 𝐃𝐞𝐥𝐚𝐲𝐬 𝐇𝐨𝐥𝐝 𝐁𝐚𝐜𝐤 𝐆𝐨𝐥𝐝 𝐒𝐚𝐥𝐞𝐬
Until the Lone Tree plant opens at the end of 2027, i-80 Gold must send its refractory sulfide ore — rock that requires high heat and pressure to release gold — to an outside processor. That arrangement is holding back sales. The company produced 11,685 ounces of gold this quarter but sold only 7,744 ounces because settlements lagged.
• Gold held at the outside processor: over 6,200 recoverable ounces, up from 5,300 ounces in Q2
• Additional gold held in inventory: about 4,100 ounces, up from 1,800 ounces in Q2
• Total unsold gold stock: about 10,300 ounces, a build of 3,200 ounces this quarter by our math
The company also said "Gold production is expected to be in the lower half of the guidance range" for 2026. It chose to leach new Archimedes oxide ore — rock that yields gold using a simpler chemical wash on outdoor pads — on its own pad rather than selling it, which will "delay recording production from the fourth quarter of 2026 to the first quarter of 2027". In 2027 it plans to stockpile sulfide ore for Lone Tree instead of paying the outside processor, which will hold back revenue next year before improving margins in 2028.
What to watch: how much of the 6,200 ounces at the outside facility turns into sales in the fourth quarter. The company expects over half to clear by year-end.
🔴 𝐖𝐨𝐫𝐤𝐞𝐫 𝐓𝐮𝐫𝐧𝐨𝐯𝐞𝐫 𝐚𝐧𝐝 𝐒𝐭𝐮𝐝𝐲 𝐃𝐞𝐥𝐚𝐲𝐬 𝐇𝐢𝐭 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐨𝐧𝐬
Competition for underground miners in Nevada hurt the flagship Granite Creek mine this quarter. Operations chief Paul Chawrun said high contractor turnover "resulted in reduced material movement and delayed access to high-grade headings". Total rock mined at Granite Creek fell 13.3% from a year ago to 84,474 tonnes, and the gold grade of mined sulfide rock dropped from 10.65 to 9.09 grams per tonne.
The miner restored staffing "following an adjustment to contractor compensation structure", which pushed Granite Creek's mining cost up 40.3% from a year ago to $188 per tonne. Separately, technical study schedules slipped again: the Cove feasibility study moved from the third quarter to the fourth quarter, its fourth delay, and the Archimedes and Mineral Point studies shifted from mid-2027 to the second half of 2027.
What to watch: Granite Creek mining cost per tonne and total tonnes mined in the fourth quarter. Higher tonnage and stable unit costs would prove the new pay structure worked.
🔴 𝐇𝐞𝐚𝐯𝐲 𝐃𝐫𝐢𝐥𝐥𝐢𝐧𝐠 𝐒𝐩𝐞𝐧𝐝 𝐖𝐢𝐝𝐞𝐧𝐞𝐝 𝐭𝐡𝐞 𝐋𝐨𝐬𝐬 𝐚𝐧𝐝 𝐂𝐚𝐬𝐡 𝐁𝐮𝐫𝐧
Advancing five projects at once is draining cash before the Lone Tree plant build reaches peak spending. Pre-development, evaluation and exploration expenses — the cost of drilling and digging early tunnels before reserves are proven — rose 66.3% from a year ago to $33.4 million. That expense line equalled 101.9% of revenue, up 39.3 percentage points from 62.7% a year ago by our math.
Because of that Ruby Hill drilling and tunnel work, the net loss excluding one-offs widened from $34.3 million to $48.2 million, and operating cash burn more than doubled from $15.2 million to $32.5 million. The company has $411.4 million in cash and plans to stockpile ore in 2027. Covering that cash gap requires up to $350 million of extra financing, most of which still needs lender approval or warrant exercises.
What to watch: progress on the proposed ore stockpile financing facility and corporate credit line in early 2027. Securing those lines will fund the 2027 stockpiling plan without running cash low.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐌𝐢𝐧𝐞𝐫𝐚𝐥 𝐏𝐨𝐢𝐧𝐭 𝐌𝐨𝐯𝐞𝐬 𝐀𝐡𝐞𝐚𝐝 𝐨𝐟 𝐂𝐨𝐯𝐞 𝐢𝐧 𝐭𝐡𝐞 𝐏𝐥𝐚𝐧
On October 14 the gold developer reordered its long-term project pipeline "to better align plant feed and processing capacity, and optimize capital allocation". It made the Mineral Point open-pit mine its next major build after the initial hub-and-spoke platform, pushing the Cove underground mine and Granite Creek open pit later. Because Granite Creek and Archimedes show potential to expand, Cove is not needed until their output declines.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐂𝐚𝐬𝐡 𝐚𝐧𝐝 𝐜𝐚𝐬𝐡 𝐞𝐪𝐮𝐢𝐯𝐚𝐥𝐞𝐧𝐭𝐬 (𝟐𝟔𝐐𝟑): $𝟒𝟏𝟏.𝟒 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Cash on hand fell by $53.2 million from the second quarter's $464.6 million, after peaking at $513.5 million in the first quarter following the company's refinancing. Operating cash outflows of $32.5 million and capital expenditures of $15.0 million for the Lone Tree plant rebuild drove the decrease.
𝐃𝐫𝐢𝐥𝐥𝐢𝐧𝐠 𝐜𝐨𝐦𝐩𝐥𝐞𝐭𝐞𝐝 (𝟐𝟔𝐐𝟑): 𝟑𝟔,𝟎𝟎𝟎 𝐦𝐞𝐭𝐞𝐫𝐬 ⇗ accelerating
Surface and underground drilling accelerated in the third quarter, bringing the nine-month total to 62,000 meters after only 6,937 meters in the first quarter. Seven drill rigs operated at the Mineral Point open pit to complete 25,865 meters, after new rigs arrived to fix earlier contractor shortages.
𝐖𝐞𝐢𝐠𝐡𝐭𝐞𝐝 𝐚𝐯𝐞𝐫𝐚𝐠𝐞 𝐬𝐡𝐚𝐫𝐞𝐬 (𝟐𝟔𝐐𝟑): 𝟖𝟔𝟔.𝟒 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇒ stable
The basic share count rose 6.2% from 815.6 million a year ago and edged up from 861.1 million in the second quarter. The year-over-year increase reflects shares issued during the refinancing and equity raises over the past year.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝟐𝟎𝟐𝟔 𝐂𝐨𝐧𝐬𝐨𝐥𝐢𝐝𝐚𝐭𝐞𝐝 𝐆𝐨𝐥𝐝 𝐏𝐫𝐨𝐝𝐮𝐜𝐭𝐢𝐨𝐧: 𝐋𝐨𝐰𝐞𝐫 𝐡𝐚𝐥𝐟 𝐨𝐟 𝟒𝟎,𝟎𝟎𝟎–𝟓𝟎,𝟎𝟎𝟎 𝐨𝐳 ⇘ decelerating
🠇 cut from 40,000–50,000 oz
Cut. The company steered full-year gold output to the lower half of its 40,000 to 50,000 ounce target, while Granite Creek stays within its 30,000 to 40,000 ounce range. By our math, the 42,500 ounce middle of that lower half leaves about 8,850 ounces for the fourth quarter, down from 11,685 ounces in the third quarter. Leaching Archimedes oxide ore on-site delays fourth-quarter ounces into early 2027.
𝟐𝟎𝟐𝟔 𝐋𝐨𝐧𝐞 𝐓𝐫𝐞𝐞 𝐏𝐥𝐚𝐧𝐭 𝐆𝐫𝐨𝐰𝐭𝐡 𝐂𝐚𝐩𝐢𝐭𝐚𝐥: 𝐁𝐞𝐥𝐨𝐰 $𝟏𝟒𝟎–𝟏𝟔𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠇 cut from $140–160 million
Cut. Cash spending on the Lone Tree plant rebuild will finish 2026 below the original range. The miner still expects to commit nearly all refurbishment capital by year-end, but invoices are taking "between four to five months" to arrive and get paid rather than the 30 days originally assumed. That timing gap shifts the cash outflow into 2027 without changing the construction schedule.
𝟐𝟎𝟐𝟔 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐂𝐨𝐬𝐭𝐬: 𝐋𝐨𝐰 𝐞𝐧𝐝 𝐨𝐟 $𝟏𝟑𝟓–𝟏𝟓𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠇 cut from $135–150 million ($110–120M Granite Creek, $25–30M Archimedes)
Cut. The Nevada producer now expects operating costs at the low end of its full-year range. Lower total gold production and a higher share of oxide ore at Granite Creek, which costs less to process than sulfide rock, reduced expected spending. By our math, hitting the $110 million low end at Granite Creek after $60.7 million in the first nine months leaves up to $49.3 million for the fourth quarter.
𝟐𝟎𝟐𝟔 𝐄𝐱𝐩𝐥𝐨𝐫𝐚𝐭𝐢𝐨𝐧, 𝐏𝐫𝐞-𝐃𝐞𝐯𝐞𝐥𝐨𝐩𝐦𝐞𝐧𝐭 𝐚𝐧𝐝 𝐎𝐭𝐡𝐞𝐫 𝐂𝐚𝐩𝐢𝐭𝐚𝐥: 𝐄𝐱𝐩𝐥𝐨𝐫𝐚𝐭𝐢𝐨𝐧 𝐛𝐞𝐥𝐨𝐰 𝐩𝐥𝐚𝐧; 𝐬𝐮𝐬𝐭𝐚𝐢𝐧𝐢𝐧𝐠, 𝐠𝐫𝐨𝐰𝐭𝐡 𝐚𝐧𝐝 𝐩𝐫𝐞-𝐝𝐞𝐯𝐞𝐥𝐨𝐩𝐦𝐞𝐧𝐭 𝐚𝐭 𝐥𝐨𝐰 𝐞𝐧𝐝 ⇘ decelerating
🠆 unchanged from Exploration ~$10M below $90–110M; sustaining $6–8M; pre-development $50–60M
Unchanged. i-80 Gold kept exploration spending below its initial 2026 plan because drill rig and crew shortages slowed work earlier in the year, though rigs arrived in the third quarter. Sustaining capital, total growth capital and pre-development expense are all tracking to the low end of their ranges, helped by capitalizing Granite Creek tunnel costs after the September reserve report.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐜𝐚𝐬𝐡 𝐰𝐢𝐥𝐥 𝐬𝐭𝐨𝐜𝐤𝐩𝐢𝐥𝐢𝐧𝐠 𝐨𝐫𝐞 𝐭𝐢𝐞 𝐮𝐩 𝐢𝐧 𝟐𝟎𝟐𝟕?
The company plans to stockpile high-grade sulfide ore from Granite Creek and Archimedes throughout 2027 rather than using the outside processor. Management did not disclose how many ounces it will hold back or how much working capital that inventory build will consume.
𝐖𝐡𝐚𝐭 𝐚𝐫𝐞 𝐭𝐡𝐞 𝐭𝐞𝐫𝐦𝐬 𝐨𝐟 𝐭𝐡𝐞 𝐩𝐫𝐨𝐩𝐨𝐬𝐞𝐝 𝐬𝐭𝐨𝐜𝐤𝐩𝐢𝐥𝐞 𝐟𝐢𝐧𝐚𝐧𝐜𝐢𝐧𝐠 𝐟𝐚𝐜𝐢𝐥𝐢𝐭𝐲?
Lenders under the 2026 gold prepayment deal approved a new ore stockpile financing facility, and the company is discussing a corporate credit line. Investors need to know the size, interest cost and conditions of both facilities before 2027 stockpiling begins.
𝐖𝐡𝐲 𝐝𝐢𝐝 𝐭𝐡𝐞 𝐂𝐨𝐯𝐞 𝐟𝐞𝐚𝐬𝐢𝐛𝐢𝐥𝐢𝐭𝐲 𝐬𝐭𝐮𝐝𝐲 𝐬𝐥𝐢𝐩 𝐚 𝐟𝐨𝐮𝐫𝐭𝐡 𝐭𝐢𝐦𝐞?
The Cove underground study moved from the third quarter to the fourth quarter of 2026, following three earlier delays. While Cove now sits later in the construction sequence, the release gave no technical reason why the engineering report was not finished on time.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐋𝐨𝐧𝐞 𝐓𝐫𝐞𝐞 𝐜𝐚𝐬𝐡 𝐬𝐩𝐞𝐧𝐝𝐢𝐧𝐠 𝐬𝐡𝐢𝐟𝐭𝐬 𝐢𝐧𝐭𝐨 𝟐𝟎𝟐𝟕?
A four-to-five-month lag between committing capital and paying invoices pushed 2026 Lone Tree capital expenditures below the $140 million to $160 million plan. Management has not stated the exact 2026 cash figure or the updated quarterly cash bill for 2027.

$ESRT Q3 2026 earnings: Empire State Realty fills offices, but tourist visits fall
Empire State Realty Trust, the owner of the Empire State Building and Manhattan offices, filled more space while its tourist deck slumped. Commercial occupancy jumped to 92%, and the landlord sold 1359 Broadway to buy back $86 million of stock. However, Observation Deck visits fell 26% in the peak summer quarter, pulling operating cash profit per share down to $0.20.
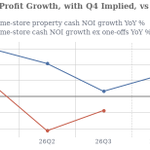
• Same-store property cash profit, excluding one-offs: -𝟏.𝟑% (reported +0.5% from a year ago)
• Core FFO per share (operating cash profit): $𝟎.𝟐𝟎 ($0.23 a year ago (-13%))
• Commercial portfolio occupancy: 𝟗𝟐.𝟑% (89.4% last quarter)
• Full-year Core FFO outlook: 𝐑𝐚𝐢𝐬𝐞𝐝 $𝟎.𝟎𝟏𝟓 (middle of the range: $0.785 per share)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🟢 Bullish
The story got better because signed office leases finally turned into occupied space and management used property sale proceeds to retire nearly 7% of its shares. The company also raised its full-year cash profit outlook. One caution: the higher property cash profit outlook rests on one-time refunds rather than underlying rent growth, and debt leverage edged up to 6.7 times cash flow.
The question now is whether rising office occupancy and lower share counts can outweigh the Observation Deck slump in 2027. Either international tourists return and new office tenants start paying cash rent after free-rent periods, or deck profit keeps shrinking while property taxes and interest costs eat up the rent gains. Fourth-quarter deck profit and year-end debt levels will tell.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐌𝐚𝐧𝐡𝐚𝐭𝐭𝐚𝐧 𝐎𝐟𝐟𝐢𝐜𝐞 𝐎𝐜𝐜𝐮𝐩𝐚𝐧𝐜𝐲 𝐉𝐮𝐦𝐩𝐞𝐝 𝐚𝐬 𝐒𝐢𝐠𝐧𝐞𝐝 𝐋𝐞𝐚𝐬𝐞𝐬 𝐂𝐨𝐦𝐦𝐞𝐧𝐜𝐞𝐝
Empire State Realty Trust's commercial buildings are filling up, and signed contracts are now turning into occupied floors. The landlord signed 189,477 square feet of commercial leases this quarter, including 170,608 square feet of Manhattan office space. That lifted the commercial leased rate (occupied space plus signed leases not yet started) to 95.6%, while occupancy jumped 2.9 percentage points from last quarter to 92.3%.
• New Manhattan office leases: 125,239 square feet at cash rents 16.2% above prior escalated rents
• Blended office leasing spread: +9.9%, the 21st straight quarter of higher rents on newly signed office space
• Office leasing commissions and tenant build-out costs: $80.41 per square foot, down from $119.05 last quarter
• Free rent on signed commercial leases: 5.7 months on average, down from 9.5 months last quarter
This matters because the gap between leased and occupied space narrowed from 5.5 percentage points to 3.3 percentage points as tenants moved in. Spending per square foot to outfit spaces and pay brokers also dropped, which addresses a standing concern over rising leasing costs.
What to watch: fourth-quarter commercial occupancy against the 90% to 92% year-end plan. Maintaining occupancy above 92% despite planned tenant move-outs would set up stronger cash rent collection in 2027.
🟢 𝐏𝐫𝐨𝐩𝐞𝐫𝐭𝐲 𝐒𝐚𝐥𝐞 𝐅𝐮𝐧𝐝𝐞𝐝 $𝟖𝟔 𝐌𝐢𝐥𝐥𝐢𝐨𝐧 𝐨𝐟 𝐒𝐡𝐚𝐫𝐞 𝐁𝐮𝐲𝐛𝐚𝐜𝐤𝐬
Management had not bought back a single share in the first half of 2026, leaving a $500 million buyback authorization untouched. After the third quarter ended, the real estate trust closed the sale of its 1359 Broadway office building for $217.5 million and used last quarter's $110 million land purchase under 111 West 33rd Street and 1400 Broadway to defer taxes on the sale.
Starting in late July through November 2, the company used the sale proceeds to repurchase $85.8 million of common stock at an average price of $4.56 per share. By our math, that retired about 18.8 million shares, or nearly 7% of all common shares and partnership units. Because most purchases happened late in the quarter or in October, the third-quarter average diluted share count barely moved, so the per-share earnings lift arrives in the fourth quarter.
What to watch: how much of the remaining $132 million from 1359 Broadway goes to debt repayment in the fourth quarter. Retiring debt alongside the share count reduction would lift per-share cash flow without pushing debt ratios higher.
🟢 𝐂𝐨𝐬𝐭 𝐂𝐮𝐭𝐬 𝐋𝐨𝐰𝐞𝐫𝐞𝐝 𝐎𝐯𝐞𝐫𝐡𝐞𝐚𝐝 𝐚𝐧𝐝 𝐆𝐫𝐨𝐮𝐧𝐝 𝐑𝐞𝐧𝐭
Operating margin fell 1.3 percentage points from a year ago to 18.5% because tourist ticket sales dropped and real estate taxes rose 1.5 percentage points of revenue. However, the expenses management directly controls moved down.
General and administrative overhead fell to $17.2 million, or $16.5 million excluding $0.6 million of severance, by our math. That is down 11.8% from a year ago and beats the $17 million quarterly target set for the second half of 2026. Ground rent also dropped 1.0 percentage point of revenue to $0.4 million after the group bought the land under two Broadway buildings in the second quarter.
What to watch: fourth-quarter general and administrative expenses excluding severance. Another reading below $17 million would confirm that the 5% to 10% overhead reduction plan is permanent.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐎𝐛𝐬𝐞𝐫𝐯𝐚𝐭𝐢𝐨𝐧 𝐃𝐞𝐜𝐤 𝐓𝐫𝐚𝐟𝐟𝐢𝐜 𝐊𝐞𝐩𝐭 𝐅𝐚𝐥𝐥𝐢𝐧𝐠 𝐢𝐧 𝐏𝐞𝐚𝐤 𝐒𝐮𝐦𝐦𝐞𝐫
The Empire State Building Observation Deck brings in high-margin tourist ticket revenue, and the third quarter is historically its busiest summer season. Instead of recovering against an easier comparison from last year, "Visitation continued to be weak", Empire State Realty Trust said. Turnstile visits dropped 25.8% from a year ago to 481,000, while revenue per visitor was flat (+0.2% by our math), showing that ticket pricing is no longer offsetting lost foot traffic.
• Observatory revenue: $26.8 million, down 25.6% from $36.0 million a year ago
• Observatory operating expenses: $11.2 million, up 17.8% from a year ago (+1.0 percentage point of total company revenue)
• Observatory net operating income (NOI): $15.6 million, down 41.2% from $26.5 million a year ago
Because deck operating costs rose while ticket sales fell, deck profit dropped much faster than visitor counts. The release also gave no update on domestic visitor share or tour-pass channel volumes. The landlord kept its full-year deck profit target at $55 million, which by our math leaves $16.3 million for the fourth quarter, down 33.2% from a year ago.
What to watch: fourth-quarter Observation Deck NOI against the $16.3 million implied target. A miss would threaten the remaining goodwill on the balance sheet and lower the starting base for 2027 profit.
🔴🔴 𝐎𝐧𝐞-𝐎𝐟𝐟 𝐑𝐞𝐟𝐮𝐧𝐝𝐬 𝐃𝐫𝐨𝐯𝐞 𝐭𝐡𝐞 𝐏𝐫𝐨𝐩𝐞𝐫𝐭𝐲 𝐂𝐚𝐬𝐡 𝐏𝐫𝐨𝐟𝐢𝐭 𝐑𝐚𝐢𝐬𝐞
Empire State Realty Trust raised its full-year outlook for same-store property cash net operating income (cash profit from buildings owned in both periods, excluding lease termination fees) to +1.75% to +2.25%, up from -1.5% to +2.0%. However, the company noted in the outlook table that the higher range is "driven primarily by non-recurring items" recorded earlier this year.
In the third quarter, reported same-store property cash profit rose 0.5% from a year ago to $66.7 million, helped by tenant expense reimbursements and insurance recoveries. Stripping out $1.2 million of third-quarter non-recurring items leaves underlying cash profit down 1.3% from a year ago, by our math. The landlord highlighted +1.9% growth when also adding back roughly $2 million of lost revenue from the expired Federal Deposit Insurance Corporation (FDIC) lease, which was pre-leased to LinkedIn. Even on the reported basis, the full-year midpoint of +2.0% leaves fourth-quarter same-store cash profit flat (-0.02% by our math).
What to watch: when LinkedIn and other signed tenants finish their free-rent periods and begin paying cash rent in early 2027. Until cash rent starts, same-store cash profit relies on one-time refunds to stay positive.
🔴 𝐃𝐞𝐛𝐭 𝐋𝐞𝐯𝐞𝐫𝐚𝐠𝐞 𝐂𝐥𝐢𝐦𝐛𝐞𝐝 𝐅𝐮𝐫𝐭𝐡𝐞𝐫 𝐀𝐛𝐨𝐯𝐞 𝐭𝐡𝐞 𝐓𝐚𝐫𝐠𝐞𝐭
Empire State Realty Trust has historically aimed to keep net debt below roughly 6 times adjusted EBITDA (earnings before interest, taxes, depreciation and amortization). In the third quarter, net debt to adjusted EBITDA rose to 6.7x, up from 6.6x last quarter and 5.6x a year ago, because Observation Deck earnings shrank while total debt stood at $2.2 billion.
Higher debt costs and New York City property taxes also weighed on earnings: net interest expense rose 10.7% from a year ago to $27.9 million (+1.7 percentage points of revenue), and real estate taxes rose 6.1% to $35.3 million. The company plans "to redeploy the proceeds towards share repurchases and will also use proceeds to paydown debt" from the $217.5 million sale of 1359 Broadway, which closed after quarter-end. Meanwhile, dual-class voting shares and concentration in New York City remain unchanged standing risks.
What to watch: net debt to adjusted EBITDA at year-end after the 1359 Broadway cash is applied. A ratio still above 6.5x would show that falling deck profit is offsetting debt paydowns.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐂𝐨𝐫𝐞 𝐅𝐮𝐧𝐝𝐬 𝐀𝐯𝐚𝐢𝐥𝐚𝐛𝐥𝐞 𝐟𝐨𝐫 𝐃𝐢𝐬𝐭𝐫𝐢𝐛𝐮𝐭𝐢𝐨𝐧 (𝟐𝟔𝐐𝟑): $𝟒𝟏.𝟐 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Cash available for distribution after capital spending rose 2.0% from a year ago and more than doubled from $16.2 million last quarter. Second-generation tenant improvement payments dropped to $1.4 million from $24.7 million in the second quarter, lowering the dividend payout ratio on this cash measure from 60% to 24%.
𝐑𝐞𝐧𝐭𝐚𝐥 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 (𝟐𝟔𝐐𝟑): $𝟏𝟔𝟐.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Rental income from office, retail and apartment tenants grew 2.2% from a year ago, slowing from 7.6% growth in the second quarter after the June sale of 250 West 57th Street. Base rent increased 1.5% to $138.4 million, while tenant expense reimbursements rose 6.7% to $23.5 million.
𝐌𝐮𝐥𝐭𝐢𝐟𝐚𝐦𝐢𝐥𝐲 𝐨𝐜𝐜𝐮𝐩𝐚𝐧𝐜𝐲 (𝟐𝟔𝐐𝟑): 𝟗𝟕.𝟏% ⇘ decelerating
Occupancy across the real estate trust's 743 residential apartment units dipped 0.6 percentage points from last quarter and 1.5 percentage points from a year ago. Despite slightly lower occupancy, same-store cash profit from the apartment buildings rose 1.8% from a year ago to $5.4 million on higher rents.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟔 𝐂𝐨𝐫𝐞 𝐅𝐅𝐎 𝐩𝐞𝐫 𝐝𝐢𝐥𝐮𝐭𝐞𝐝 𝐬𝐡𝐚𝐫𝐞: $𝟎.𝟕𝟕–$𝟎.𝟖𝟎 ⇘ decelerating
🠅 raised from $0.75–$0.79
Raised. The middle of the range moved up 1.5 cents to $0.785 per share, which is still down 9.8% from $0.87 in 2025, by our math. The new plan reflects share buybacks and the sale of 1359 Broadway after a 10-cent cut last quarter. By our math, the full-year midpoint leaves 17.5 cents for Q4, down 23.9% from 23 cents a year ago.
𝐅𝐘𝟐𝟔 𝐒𝐚𝐦𝐞-𝐒𝐭𝐨𝐫𝐞 𝐏𝐫𝐨𝐩𝐞𝐫𝐭𝐲 𝐂𝐚𝐬𝐡 𝐍𝐎𝐈 𝐠𝐫𝐨𝐰𝐭𝐡: +𝟏.𝟕𝟓% 𝐭𝐨 +𝟐.𝟐𝟓% ⇘ decelerating
🠅 raised from -1.5% to +2.0%
Raised. The middle of the range rose from +0.25% to +2.0% after holding steady for two quarters. The landlord attributed the raise to one-time items earlier in the year and lowered its full-year property operating expense and tax growth assumption to 4.0%–6.0% from 5.0%–7.0%. By our math, the +2.0% midpoint leaves Q4 flat (-0.02%) against a year ago.
𝐅𝐘𝟐𝟔 𝐘𝐞𝐚𝐫-𝐄𝐧𝐝 𝐂𝐨𝐦𝐦𝐞𝐫𝐜𝐢𝐚𝐥 𝐎𝐜𝐜𝐮𝐩𝐚𝐧𝐜𝐲: 𝟗𝟎% 𝐭𝐨 𝟗𝟐% ⇘ decelerating
🠆 unchanged from 90% to 92%
Unchanged. Management kept the year-end target at 90% to 92% for a third straight quarter. Because third-quarter occupancy reached 92.3% after removing the sold 1359 Broadway building, the 91.0% midpoint points to a 1.3 percentage point dip in the fourth quarter due to "temporary downtime for pre-leased space".
𝐅𝐘𝟐𝟔 𝐎𝐛𝐬𝐞𝐫𝐯𝐚𝐭𝐢𝐨𝐧 𝐃𝐞𝐜𝐤 𝐍𝐎𝐈 𝐔𝐭𝐢𝐥𝐢𝐳𝐞𝐝: $𝟓𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇒ stable
🠆 unchanged from $55 million
Unchanged. The full-year deck profit figure remains at $55 million, where it was reset last quarter after starting the year at $87 million to $92 million. With $38.7 million earned in the first nine months, the target leaves $16.3 million for Q4, by our math, down 33.2% from $24.4 million in Q4 2025.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐚𝐭 𝐝𝐫𝐨𝐯𝐞 𝐭𝐡𝐞 𝟏𝟖% 𝐣𝐮𝐦𝐩 𝐢𝐧 𝐎𝐛𝐬𝐞𝐫𝐯𝐚𝐭𝐢𝐨𝐧 𝐃𝐞𝐜𝐤 𝐞𝐱𝐩𝐞𝐧𝐬𝐞𝐬?
Observatory operating expenses rose to $11.2 million from $9.5 million a year ago even though visitor counts fell 25.8%. Management has not explained whether the higher spend comes from marketing, staffing or the business model review.
𝐇𝐨𝐰 𝐚𝐫𝐞 𝐎𝐛𝐬𝐞𝐫𝐯𝐚𝐭𝐢𝐨𝐧 𝐃𝐞𝐜𝐤 𝐭𝐨𝐮𝐫-𝐩𝐚𝐬𝐬 𝐚𝐧𝐝 𝐝𝐨𝐦𝐞𝐬𝐭𝐢𝐜 𝐜𝐡𝐚𝐧𝐧𝐞𝐥𝐬 𝐩𝐞𝐫𝐟𝐨𝐫𝐦𝐢𝐧𝐠?
The earnings release noted that visitation remained weak but gave no breakdown of international tourists, domestic visitors or pass-program ticket volumes. Investors need the channel numbers to judge whether traffic is stabilizing.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐨𝐟 𝐭𝐡𝐞 𝟏𝟑𝟓𝟗 𝐁𝐫𝐨𝐚𝐝𝐰𝐚𝐲 𝐜𝐚𝐬𝐡 𝐰𝐢𝐥𝐥 𝐫𝐞𝐩𝐚𝐲 𝐝𝐞𝐛𝐭?
Empire State Realty Trust raised $217.5 million from selling 1359 Broadway and spent $85.8 million on share buybacks through November 2. With net debt to adjusted EBITDA at 6.7x, the split of the remaining $132 million matters for leverage.
𝐖𝐡𝐚𝐭 𝐝𝐞𝐜𝐥𝐢𝐧𝐞 𝐢𝐧 𝐝𝐞𝐜𝐤 𝐩𝐫𝐨𝐟𝐢𝐭 𝐰𝐨𝐮𝐥𝐝 𝐢𝐦𝐩𝐚𝐢𝐫 𝐭𝐡𝐞 𝐫𝐞𝐦𝐚𝐢𝐧𝐢𝐧𝐠 𝐠𝐨𝐨𝐝𝐰𝐢𝐥𝐥?
After writing off $166.1 million of Observatory goodwill in the second quarter, the company still carries $325.4 million of goodwill on its balance sheet. Another traffic drop below the $55 million profit framework could trigger a further write-down.

$CALX Q3 2026 earnings: Calix software growth speeds up, but memory costs squeeze profit
Calix, which sells network hardware and cloud software to internet providers, saw software growth speed up while memory chip costs squeezed hardware profits. Total revenue rose 14% to $302 million, landing near the bottom of the company's plan, while software and service sales jumped 19% and hit a record gross margin. Chief executive Michael Weening kept the full-year revenue outlook near 19% growth, and by our math the fourth-quarter plan leaves gross margin flat at 53.5%.
• Revenue: $𝟑𝟎𝟏.𝟕𝐌 (+14% from a year ago)
• Software and service revenue: $𝟓𝟏.𝟗𝐌 (+19% from a year ago)
• Gross margin, excluding one-offs: 𝟓𝟑.𝟓% (-4.2 percentage points from a year ago)
• Full-year revenue outlook: 𝐔𝐧𝐜𝐡𝐚𝐧𝐠𝐞𝐝 (~19% growth (upper end of 15–20%))
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because the rebound in software offset ongoing hardware cost pressure without breaking the backlog logjam. Software revenue and margins improved after all customers moved onto the Calix One AI platform, and internal AI tools let management plan for flat engineering spend next year. The bad news: multi-year contracted backlog grew only 13% before an accounting change despite signed AI contracts doubling, and buybacks plus inventory builds have drained 60% of the cash pile this year.
The question now is whether the new AI platform will drive faster multi-year contract growth or mainly help existing customers add subscribers at the current pace. If the new contracts carry real spending, contracted backlog growth will climb toward the 19% software pace; if they are mostly bundled upgrades, backlog growth will stay in the low teens. Fourth-quarter backlog and software revenue will test both sides.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐒𝐨𝐟𝐭𝐰𝐚𝐫𝐞 𝐆𝐫𝐨𝐰𝐭𝐡 𝐚𝐧𝐝 𝐌𝐚𝐫𝐠𝐢𝐧𝐬 𝐑𝐞𝐛𝐨𝐮𝐧𝐝𝐞𝐝 𝐨𝐧 𝐂𝐚𝐥𝐢𝐱 𝐎𝐧𝐞
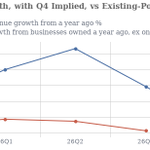
"The third quarter marked our shift from AI enablement to AI execution," chief executive Michael Weening wrote. Calix sells network boxes and cloud software to internet providers, and it moved all of its cloud customers onto its new AI platform, Calix One, in March. After slowing for three straight quarters, software and service revenue grew 19.5% from a year ago to $51.9 million.
The division's gross margin, excluding one-offs, reached a record 67.2%, up 2.0 percentage points from a year ago and 3.4 points from last quarter. That beat the prior 66.5% record because the broadband supplier finished moving customers off its old cloud system and added more subscribers. Customers also published concrete savings from the tools, with rural provider Chariton Valley cutting operating costs by nearly $500,000 this year.
What to watch: software and service revenue growth in the fourth quarter. A second quarter near 20% growth would show that the new platform is driving lasting software demand rather than a one-quarter bounce.
🟢 𝐀𝐈 𝐓𝐨𝐨𝐥𝐬 𝐋𝐞𝐭 𝐂𝐚𝐥𝐢𝐱 𝐇𝐨𝐥𝐝 𝐄𝐧𝐠𝐢𝐧𝐞𝐞𝐫𝐢𝐧𝐠 𝐒𝐩𝐞𝐧𝐝 𝐅𝐥𝐚𝐭
Calix is using AI tools from its partners inside its own business to keep overhead down while revenue grows. Operating expenses, excluding one-offs, fell to 41.1% of revenue from 43.2% a year ago, a drop of 2.1 percentage points. Sales and marketing costs shrank by 1.6 points of revenue, and general and administrative overhead fell by 1.1 points, while research and development rose 0.6 points.
Weening wrote that an engineering team finished a 15-month project in three months using the new tools. Because of those gains, the company plans to "deliver more capabilities to customers in 2027 than in 2025 and 2026 combined, with R&D investment flat to down from 2026". Holding engineering spend flat while revenue grows would move the business closer to its 20% operating margin goal.
What to watch: first-quarter 2027 operating expense outlook when fourth-quarter results arrive. It will show whether research and development spending actually stops growing after the fourth-quarter customer conference costs pass.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐌𝐞𝐦𝐨𝐫𝐲 𝐂𝐨𝐬𝐭𝐬 𝐊𝐞𝐞𝐩 𝐒𝐪𝐮𝐞𝐞𝐳𝐢𝐧𝐠 𝐇𝐚𝐫𝐝𝐰𝐚𝐫𝐞 𝐌𝐚𝐫𝐠𝐢𝐧𝐬
Calix gets 83% of its revenue from network hardware appliances, and those boxes need memory chips. The company said "a rapid, industry-wide rise in memory costs due to the demand from the building of AI data centers" pushed appliance gross margin down 5.5 percentage points from a year ago to 50.7%. Cost of goods for appliances jumped 4.2 percentage points of total revenue.
• Total gross margin, excluding one-offs: 53.5%, down 4.2 percentage points from a year ago
• Fourth-quarter gross margin outlook: 52.25% to 54.75%, flat at the 53.5% middle of the range
• Full-year gross margin, by our math: down 2.6 percentage points from 2025, missing the Q1 plan for a 0.5 to 1.5 point drop
The San Jose group adds surcharges "intended to offset incremental memory costs over time" without adding a profit markup. Because those fees pass costs through at zero margin, they dilute the gross margin percentage even when they recover the dollars. The fourth-quarter outlook shows no margin recovery yet, confirming that higher chip prices outweigh the software margin gains.
What to watch: appliance gross margin in the fourth quarter. A drop below 50.7% would mean chip inflation is still outrunning the monthly surcharge resets.
🔴🔴 𝐂𝐨𝐧𝐭𝐫𝐚𝐜𝐭𝐞𝐝 𝐁𝐚𝐜𝐤𝐥𝐨𝐠 𝐒𝐭𝐢𝐥𝐥 𝐋𝐚𝐠𝐬 𝐁𝐞𝐡𝐢𝐧𝐝 𝐀𝐈 𝐂𝐥𝐚𝐢𝐦𝐬
Weening wrote that "Calix One contracts signed in the third quarter of 2026 more than doubled from the previous quarter". Management also predicted that remaining performance obligations (RPO) — the total value of signed multi-year software and service contracts not yet recognized as revenue — would grow faster as customers adopt AI workflows. Yet total RPO rose only 11.6% from a year ago to $395.7 million.
This quarter Calix began adding non-cancellable hardware orders to RPO, so it elected "to eliminate the value of RPOs for contracts with a duration of one year or less". That rule change removed $6.0 million of short software deals. Even adding that $6.0 million back, RPO grew 13.3% from a year ago by our math, adding $15.3 million in the quarter, which is barely above the 11.5% pace in the second quarter.
What to watch: fourth-quarter RPO growth on a comparable basis. Without a jump above 15%, doubling the number of AI contracts is not moving the total value of multi-year commitments.
🔴 𝐁𝐮𝐲𝐛𝐚𝐜𝐤𝐬 𝐚𝐧𝐝 𝐈𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 𝐃𝐫𝐚𝐢𝐧𝐞𝐝 𝐎𝐯𝐞𝐫 𝐇𝐚𝐥𝐟 𝐭𝐡𝐞 𝐂𝐚𝐬𝐡
Calix has prioritized buying stock and stockpiling hardware parts over holding cash on its balance sheet. Cash and marketable securities fell to $154.8 million from $388.1 million at the end of December, a 60% drop in nine months. The company spent $50.0 million buying back 1.4 million shares this quarter, bringing nine-month buybacks to $290.2 million, and the board added $100 million to the buyback plan in October.
At the same time, the hardware maker added $14.6 million of inventory in the quarter to guard against supply shortages, lifting total inventory 74% from a year ago to $187.9 million. That inventory build held third-quarter free cash flow to $3.4 million, down 87% from $26.7 million a year ago. With only $37.4 million of operating cash flow in nine months, selling investments funded the buybacks.
What to watch: inventory levels and free cash flow in the fourth quarter. Another inventory build alongside heavy buybacks would pull cash and investments closer to $100 million.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
Several standing risks and growth drivers received no quantitative update or only a brief mention in the stockholder letter.
• Customer concentration and international sales: one unnamed customer accounted for 11% of revenue (after 12% last quarter), while international revenue fell 14% from a year ago to 5% of the total.
• Federal broadband funding (BEAD): listed only as a forward-looking factor, with no order or shipment figures to show when government-funded builds will lift revenue.
• Large service provider wins: mentioned as a target market for software on open gateways, with no named Tier-1 contracts disclosed.
• Satellite competition and May 2026 memory-supply lawsuit: neither appeared in the stockholder letter; the quarterly filing will carry the legal update.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐀𝐩𝐩𝐥𝐢𝐚𝐧𝐜𝐞 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 (𝟐𝟔𝐐𝟑): $𝟐𝟒𝟗.𝟖 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Appliance revenue — sales of network boxes and optical gear — reached a record $249.8 million, up 12.5% from a year ago and 2.9% from last quarter. Growth slowed from 22.5% in the second quarter and 29.5% in the first quarter as the company lapped last year's 32% revenue jump.
𝐃𝐢𝐥𝐮𝐭𝐞𝐝 𝐬𝐡𝐚𝐫𝐞 𝐜𝐨𝐮𝐧𝐭 (𝟐𝟔𝐐𝟑): 𝟔𝟒.𝟒 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
The diluted share count fell 7.7% from 69.8 million a year ago after the company bought back 6.3 million shares in the first nine months of 2026. The lower share count kept profit per share excluding one-offs flat at $0.44 even though net income excluding one-offs fell 6.8% to $28.5 million.
𝐃𝐚𝐲𝐬 𝐩𝐚𝐲𝐚𝐛𝐥𝐞 𝐨𝐮𝐭𝐬𝐭𝐚𝐧𝐝𝐢𝐧𝐠 (𝟐𝟔𝐐𝟑): 𝟒𝟒 𝐝𝐚𝐲𝐬 ⇘ decelerating
Days payable outstanding — the average time Calix takes to pay its suppliers — fell to 44 days from 54 last quarter, but remains well above 18 days a year ago and its 25-to-35-day target. Paying bills more slowly helped keep operating cash flow positive while inventory turns sat at 2.8, below the 3-to-4 target.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐐𝟒 𝐑𝐞𝐯𝐞𝐧𝐮𝐞: $𝟑𝟏𝟏.𝟎–𝟑𝟏𝟕.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
New. The plan calls for revenue to rise 4.1% from this quarter and 15.3% from a year ago at the $314 million middle of the range. That sits inside the $313 million to $323 million range implied by last quarter's full-year target, and includes zero-margin surcharges for memory costs.
𝐅𝐘𝟐𝟔 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐠𝐫𝐨𝐰𝐭𝐡: ~𝟏𝟗% ⇘ decelerating
🠆 unchanged from higher end of 15%–20%
Unchanged. Management now pegs full-year growth at about 19%, matching the 18.9% growth implied by the fourth-quarter outlook by our math. That confirms the prior target of the upper end of 15% to 20% after a 20% year in 2025.
𝐐𝟒 𝐆𝐫𝐨𝐬𝐬 𝐦𝐚𝐫𝐠𝐢𝐧, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: 𝟓𝟐.𝟐𝟓–𝟓𝟒.𝟕𝟓% ⇒ stable
New. The 53.5% middle of the range matches the third quarter and sits 4.5 percentage points below a year ago. Management expects memory costs to keep rising, with customer surcharges offsetting a larger share of the cost increase than in the third quarter.
𝐐𝟒 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐞𝐱𝐩𝐞𝐧𝐬𝐞𝐬, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: $𝟏𝟐𝟗.𝟓–𝟏𝟑𝟏.𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
New. Planned spending rises 5.3% from this quarter and 2.9% from a year ago at the $130.5 million middle of the range. The step-up pays for the annual ConneXions customer conference and five extra calendar days in the fourth quarter.
𝐐𝟒 𝐏𝐫𝐨𝐟𝐢𝐭 𝐩𝐞𝐫 𝐬𝐡𝐚𝐫𝐞, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: $𝟎.𝟒𝟏–𝟎.𝟒𝟗 ⇗ accelerating
New. At the $0.45 middle of the range, profit per share rises 2.3% from this quarter and 15.4% from $0.39 a year ago. The plan assumes 63.4 million diluted shares, down another 1.0 million from the third quarter on continued buybacks.
𝐅𝐘𝟐𝟔 𝐓𝐚𝐱 𝐫𝐚𝐭𝐞, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: 𝟐𝟑–𝟐𝟓% ⇒ stable
🠆 unchanged from 23–25%
Unchanged. The full-year tax rate plan stays at 23% to 25% for a fifth straight quarter.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐝𝐢𝐝 𝐦𝐞𝐦𝐨𝐫𝐲 𝐬𝐮𝐫𝐜𝐡𝐚𝐫𝐠𝐞𝐬 𝐚𝐝𝐝 𝐭𝐨 𝐭𝐡𝐢𝐫𝐝-𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐫𝐞𝐯𝐞𝐧𝐮𝐞?
Calix charges fees to recover memory costs at zero profit margin. Without the dollar amount, investors cannot tell how much of the 14% revenue growth came from shipping more gear versus passing through higher chip costs.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐨𝐟 𝐭𝐡𝐞 𝐜𝐨𝐧𝐭𝐫𝐚𝐜𝐭𝐞𝐝 𝐛𝐚𝐜𝐤𝐥𝐨𝐠 𝐢𝐬 𝐧𝐨𝐰 𝐡𝐚𝐫𝐝𝐰𝐚𝐫𝐞?
Non-cancellable hardware orders over one year entered RPO this quarter under the supply assurance program, while $6 million of short software deals left. Management did not disclose the dollar amount of hardware added to the $395.7 million total.
𝐇𝐨𝐰 𝐦𝐚𝐧𝐲 𝐜𝐮𝐬𝐭𝐨𝐦𝐞𝐫𝐬 𝐬𝐢𝐠𝐧𝐞𝐝 𝐂𝐚𝐥𝐢𝐱 𝐎𝐧𝐞 𝐜𝐨𝐧𝐭𝐫𝐚𝐜𝐭𝐬 𝐢𝐧 𝐐𝟑?
Management said signed Calix One contracts more than doubled from the second quarter, after tripling the quarter before, but gave no base number or dollar value to explain why total RPO growth stayed near 13%.
𝐖𝐢𝐥𝐥 𝐂𝐚𝐥𝐢𝐱 𝐛𝐨𝐫𝐫𝐨𝐰 𝐦𝐨𝐧𝐞𝐲 𝐢𝐟 𝐛𝐮𝐲𝐛𝐚𝐜𝐤𝐬 𝐤𝐞𝐞𝐩 𝐝𝐫𝐚𝐢𝐧𝐢𝐧𝐠 𝐜𝐚𝐬𝐡?
Cash and securities dropped by $233 million in nine months to $154.8 million while the board added $100 million to the buyback plan, leaving $144 million authorized against $3.4 million of quarterly free cash flow.

$TTI Q3 2026 earnings: Tetra sales hit a 10-year Q3 high, but operating profit stalls
Tetra Technologies, an oilfield services and industrial chemicals supplier, grew third-quarter sales while its offshore fluid margins shrank. Revenue rose 10% from a year ago to $168 million as Argentina water treatment and US industrial chemical sales hit ten-year highs for the period. However, slower deepwater drilling in the Gulf of America and higher freight costs left Adjusted EBITDA unchanged at $25 million. Chief executive Brady Murphy forecast double-digit percentage gains for both sales and Adjusted EBITDA in the fourth quarter.
• Revenue: $𝟏𝟔𝟖.𝟎𝐌 (+9.6% from a year ago)
• Adjusted EBITDA: $𝟐𝟓.𝟏𝐌 (+0.3% from a year ago (15.0% margin))
• Profit per share, excluding one-offs: $𝟎.𝟎𝟔 ($0.04 a year ago (diluted shares +11%))
• Fourth-quarter outlook: 𝐃𝐨𝐮𝐛𝐥𝐞-𝐝𝐢𝐠𝐢𝐭 𝐠𝐫𝐨𝐰𝐭𝐡 (from a year ago for revenue and Adjusted EBITDA)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because strong water and chemical sales only offset a deeper margin drop in offshore fluids, while future growth projects remain uncontracted. Water and Flowback Services lifted its Adjusted EBITDA margin to 16.7% and the Arkansas bromine plant stayed below budget, but Completion Fluids margin fell to 22.1%, below the 25% to 30% full-year plan, and the Oasis water-recycling business still has no signed contracts.
The question now is whether Tetra is starting a multi-year expansion from battery electrolytes, bromine, and data-center water, or simply riding an international oilfield cycle while those new ventures wait on permits and customers. If it is a broader transformation, offshore fluid margins will rebound above 25% and Texas regulators will clear the six pending water-reuse permits; otherwise, results will stay tied to oilfield activity and outside bromine costs. Fourth-quarter deepwater activity and the pending Texas permit rulings will decide.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐖𝐚𝐭𝐞𝐫 𝐚𝐧𝐝 𝐈𝐧𝐭𝐞𝐫𝐧𝐚𝐭𝐢𝐨𝐧𝐚𝐥 𝐆𝐫𝐨𝐰𝐭𝐡 𝐎𝐟𝐟𝐬𝐞𝐭 𝐖𝐞𝐚𝐤 𝐃𝐞𝐞𝐩𝐰𝐚𝐭𝐞𝐫
Tetra's Water and Flowback Services division treats water and tests oil and gas wells after drilling. Chief executive Brady Murphy has leaned on international contracts and automated equipment to offset a sluggish US oilfield. In the third quarter, that strategy carried the whole company: division revenue rose 21% from a year ago to $76.1 million, and its Adjusted EBITDA jumped 69% to $12.7 million.
• Water and Flowback Adjusted EBITDA margin: 16.7%, up 4.8 percentage points from a year ago
• Production testing revenue: up 60% from a year ago and 9% from last quarter
• Total international revenue: $68.8 million, or 41% of company sales
Sales in Argentina more than doubled as early production facilities ramped up in the Vaca Muerta shale basin. In the US, Tetra gained market share with SandStorm, its automated sand-filtering system for well testing, and it is now sending its first SandStorm units to the Middle East. Nine-month division margin sits at 15.3% by our math, meeting management's mid-teens full-year plan.
What to watch: the geographic revenue table in the third-quarter filing. It will show whether US oilfield water sales have stopped falling or if Argentina and industrial chemicals did all the work.
🟢 𝐈𝐧𝐝𝐮𝐬𝐭𝐫𝐢𝐚𝐥 𝐂𝐡𝐞𝐦𝐢𝐜𝐚𝐥𝐬 𝐚𝐧𝐝 𝐀𝐫𝐤𝐚𝐧𝐬𝐚𝐬 𝐏𝐥𝐚𝐧𝐭 𝐀𝐝𝐯𝐚𝐧𝐜𝐞
Alongside oilfield fluids, Tetra sells industrial chemicals such as calcium chloride and battery electrolytes, and it is building an Arkansas plant to extract its own bromine. Industrial chemical sales grew 32% from a year ago, reaching a ten-year third-quarter high and making up more than half of the Completion Fluids and Products division's $91.9 million in revenue.
Murphy credited demand from US semiconductor factories and energy-storage electrolytes. Meanwhile, the Arkansas bromine plant is less than 12 months from mechanical completion, and all major equipment is delivered or on order at costs "below our Board approved final investment decision (FID)". That keeps the early-2028 startup on track to replace expensive third-party bromine.
What to watch: year-end confirmation that Phase 2 of the Arkansas bromine plant reached mechanical completion on schedule. Any delay would force Tetra to buy costly outside bromine past 2027.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐂𝐨𝐦𝐩𝐥𝐞𝐭𝐢𝐨𝐧 𝐅𝐥𝐮𝐢𝐝𝐬 𝐌𝐚𝐫𝐠𝐢𝐧 𝐃𝐫𝐨𝐩𝐩𝐞𝐝 𝐁𝐞𝐥𝐨𝐰 𝐅𝐮𝐥𝐥-𝐘𝐞𝐚𝐫 𝐏𝐥𝐚𝐧
"Our third quarter results demonstrated broad-based strength across our portfolio, with multiple businesses achieving significant performance milestones," chief executive Brady Murphy said. Yet in Completion Fluids and Products, the division that supplies heavy brine fluids for offshore oil wells, Adjusted EBITDA fell 26% from a year ago to $20.3 million, and its margin dropped 8.4 percentage points to 22.1%.
The company blamed "product mix, lower deepwater activity in the Gulf of America, and higher diesel and associated freight costs". Across Tetra, the direct cost of making products and delivering services rose 3.2 percentage points of revenue to 73.3%, pulling gross margin down 2.8 percentage points. Because industrial chemicals grew 32% and topped half of division sales, offshore fluid sales outside chemicals fell at least 17% by our math.
The 22.1% margin landed below management's 25% to 30% full-year target range, pulling the nine-month rate down to 25.6% by our math. The release also did not mention the Beacon Offshore Energy project, where the first well using Tetra's new Neptune Z-Lite deepwater fluid was due this year.
What to watch: fourth-quarter Completion Fluids and Products Adjusted EBITDA margin and an update on the Beacon Z-Lite well. Another quarter near 22% would push the full-year margin below the 25% floor.
🔴 𝐖𝐚𝐭𝐞𝐫 𝐃𝐞𝐬𝐚𝐥𝐢𝐧𝐚𝐭𝐢𝐨𝐧 𝐒𝐭𝐢𝐥𝐥 𝐖𝐚𝐢𝐭𝐬 𝐨𝐧 𝐓𝐞𝐱𝐚𝐬 𝐏𝐞𝐫𝐦𝐢𝐭𝐬
Tetra Oasis is the company's patented system for cleaning salty oilfield water so data centers and power plants can reuse it. Murphy said the pipeline now holds seven projects, including four tied to data centers, but "Permitting remains the primary next step toward commercialization, with six beneficial reuse applications currently pending before the Texas Commission on Environmental Quality (TCEQ)".
Customers file the permits while the energy-services group answers water-quality questions from Texas and federal regulators. That leaves Tetra without a signed commercial contract even though its 2030 targets rely on desalinating 500,000 barrels a day.
What to watch: the first approved Texas beneficial reuse permit and a signed commercial Oasis contract. Until regulators approve the permits, data-center water cooling brings in no revenue.
🔴 𝐒𝐡𝐚𝐫𝐞 𝐃𝐢𝐥𝐮𝐭𝐢𝐨𝐧 𝐚𝐧𝐝 𝐖𝐨𝐫𝐤𝐢𝐧𝐠 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐃𝐫𝐚𝐢𝐧𝐞𝐝 𝐂𝐚𝐬𝐡
Tetra issued stock in June to help pay for its Arkansas bromine plant after earlier saying base-business cash flow would cover the bill. That offering lifted the third-quarter diluted share count by 10.8% from a year ago to 149.4 million, holding per-share profit excluding one-offs to $0.06.
Cash generation also slowed because customers took longer to pay. Nine-month operating cash flow fell 54% from a year ago to $31.3 million as unpaid customer bills absorbed $28.8 million. By our math, third-quarter operating cash flow was $8.8 million against $35.3 million of capital spending, so the Arkansas build is drawing on the June stock proceeds.
What to watch: fourth-quarter operating cash flow and customer receivables collection. If cash from operations does not rebound as Arkansas spending peaks in 2027, Tetra will lean harder on its credit lines.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
Several standing risks and growth drivers received no quantitative update in the third-quarter earnings release.
• Eos battery electrolyte dependency: management cited electrolyte sales as a driver, but gave no revenue figure, shipment volume, or update on whether customer Eos will hit its 4 gigawatt-hour factory target by year-end.
• Beacon Z-Lite deepwater timeline: the release did not say whether the first of three high-pressure Gulf of America wells will still happen in 2026.
• Third-party bromine cost for 2027: no disclosure on how much 2027 bromine supply is locked in or whether input costs will keep squeezing fluid margins next year.
• Critical minerals engineering: no update on the Arkansas lithium engineering study or the Magrathea magnesium joint venture.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐓𝐞𝐫𝐦 𝐋𝐨𝐚𝐧 𝐄𝐱𝐭𝐞𝐧𝐬𝐢𝐨𝐧 𝐋𝐨𝐰𝐞𝐫𝐬 𝐈𝐧𝐭𝐞𝐫𝐞𝐬𝐭 𝐂𝐨𝐬𝐭𝐬
In early October 2026, Tetra amended its $190 million term loan, extending the payoff date by nearly a year to December 31, 2030. The deal cuts the interest rate margin by 0.75 percentage points to the secured overnight rate plus 5.00% and pushes about $19 million of scheduled principal payments out to 2030, which "enhances TETRA's financial flexibility to fund the Arkansas bromine project".
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐓𝐫𝐚𝐝𝐞 𝐚𝐜𝐜𝐨𝐮𝐧𝐭𝐬 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞 (𝟐𝟔𝐐𝟑): $𝟏𝟐𝟕.𝟑 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Unpaid customer bills rose 27.9% from $99.6 million at the end of 2025, outpacing third-quarter revenue growth of 9.6%. The buildup tied up $28.8 million of cash over the first nine months of 2026, more than double the $10.8 million working-capital drag in the same period last year.
𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐞𝐱𝐩𝐞𝐧𝐝𝐢𝐭𝐮𝐫𝐞𝐬 (𝟐𝟔𝐐𝟑): $𝟑𝟓.𝟑 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
By our math, third-quarter spending on property and equipment rose to $35.3 million, or 21.0% of revenue, up from $23.3 million in the second quarter and $15.7 million a year ago. Nine-month capital spending reached $77.6 million as construction progressed on the Arkansas bromine plant.
𝐍𝐞𝐭 𝐝𝐞𝐛𝐭 (𝟐𝟔𝐐𝟑): $𝟓𝟕.𝟖 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Total debt of $183.8 million minus $84.3 million of cash and $41.7 million of short-term investments leaves $57.8 million of net debt by our math. That is down from $108.7 million at the end of 2025 because of the June stock offering, but up from $28.7 million at June 30 as Arkansas plant spending accelerated.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐐𝟒 𝟐𝟎𝟐𝟔 𝐑𝐞𝐯𝐞𝐧𝐮𝐞: 𝐔𝐩 𝐝𝐨𝐮𝐛𝐥𝐞 𝐝𝐢𝐠𝐢𝐭𝐬 𝐘𝐨𝐘 ⇗ accelerating
New. Chief executive Brady Murphy expects fourth-quarter sales to be "up double digits year-on-year" from last year's $146.7 million. By our math, a 12% gain would put fourth-quarter revenue near $164 million and full-year 2026 growth near 7%, helped by an easy comparison against a weak fourth quarter of 2025.
𝐐𝟒 𝟐𝟎𝟐𝟔 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀: 𝐔𝐩 𝐝𝐨𝐮𝐛𝐥𝐞 𝐝𝐢𝐠𝐢𝐭𝐬 𝐘𝐨𝐘 ⇗ accelerating
New. The plan calls for fourth-quarter Adjusted EBITDA to rise at least 10% from last year's depressed $20.4 million base. By our math, 12% growth would deliver about $22.8 million in the fourth quarter and $105.4 million for full-year 2026, down 7% from 2025.
𝐅𝐘𝟐𝟎𝟐𝟕 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐚𝐧𝐝 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀: 𝐈𝐧𝐜𝐫𝐞𝐚𝐬𝐞 𝐫𝐞𝐥𝐚𝐭𝐢𝐯𝐞 𝐭𝐨 𝟐𝟎𝟐𝟔 ⇒ stable
New. Management expects both revenue and Adjusted EBITDA to "increase relative to 2026" on deepwater activity, Gulf of America well completions, and Middle East SandStorm deployments. The company will give specific figures after oilfield customers announce their 2027 budgets.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐢𝐥𝐥 𝐭𝐡𝐞 𝐟𝐢𝐫𝐬𝐭 𝐁𝐞𝐚𝐜𝐨𝐧 𝐙-𝐋𝐢𝐭𝐞 𝐰𝐞𝐥𝐥 𝐬𝐭𝐢𝐥𝐥 𝐡𝐚𝐩𝐩𝐞𝐧 𝐢𝐧 𝟐𝟎𝟐𝟔?
Management previously expected to complete the first of three high-pressure Gulf of America wells for Beacon Offshore Energy in 2026, but the third-quarter release did not mention the contract while Gulf deepwater activity slowed.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐝𝐢𝐝 𝐛𝐚𝐭𝐭𝐞𝐫𝐲 𝐞𝐥𝐞𝐜𝐭𝐫𝐨𝐥𝐲𝐭𝐞𝐬 𝐠𝐞𝐧𝐞𝐫𝐚𝐭𝐞 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫?
Industrial chemical sales rose 32% partly on energy-storage electrolytes, yet Tetra still does not disclose electrolyte revenue or whether its main battery customer, Eos, has reached its 4 gigawatt-hour factory goal.
𝐖𝐡𝐞𝐧 𝐰𝐢𝐥𝐥 𝐓𝐞𝐱𝐚𝐬 𝐫𝐞𝐠𝐮𝐥𝐚𝐭𝐨𝐫𝐬 𝐫𝐮𝐥𝐞 𝐨𝐧 𝐭𝐡𝐞 𝐬𝐢𝐱 𝐎𝐚𝐬𝐢𝐬 𝐩𝐞𝐫𝐦𝐢𝐭𝐬?
Six beneficial reuse applications sit with the Texas Commission on Environmental Quality, and Tetra cannot sign commercial data-center desalination contracts until regulators approve the water-discharge rules.
𝐖𝐡𝐲 𝐝𝐢𝐝 𝐜𝐮𝐬𝐭𝐨𝐦𝐞𝐫 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞𝐬 𝐣𝐮𝐦𝐩 $𝟐𝟖 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐭𝐡𝐢𝐬 𝐲𝐞𝐚𝐫?
Trade accounts receivable climbed 28% over nine months to $127.3 million, cutting operating cash flow in half; investors need to know whether slow collections come from Argentina or US industrial buyers.

$HLMN Q3 2026 earnings: Hillman's kiosk sales jump, but it cuts its revenue plan
Hillman, a supplier of fasteners, hardware and key-copying kiosks, grew sales through acquisitions and kiosk upgrades while underlying hardware demand softened. Third-quarter revenue rose 8% and free cash flow reached $51 million as the company sold down inventory built up during last year's tariff hikes. Chief executive Jon Michael Adinolfi kept the full-year cash and operating profit plans unchanged, but trimmed the sales outlook by $25 million at the middle of the range.
• Net sales: $𝟒𝟓𝟕.𝟓𝐌 (+7.7% from a year ago)
• Profit per share, excluding one-offs: $𝟎.𝟐𝟐 (0% from a year ago ($0.22))
• Free cash flow: $𝟓𝟏.𝟏𝐌 ($9.1M a year ago)
• Full-year net sales outlook: 𝐂𝐮𝐭 $𝟐𝟓𝐌 (middle of the range: 7.6% growth)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🔴 Bearish
The story got worse because management had to cut its full-year sales target even after adding three acquired businesses this year. Meanwhile, closing the $315 million Kanebridge fastener deal pushed net debt up to 3.4 times trailing Adjusted EBITDA and forced the company to slow share buybacks. The good news: the high-margin key and engraving kiosk unit accelerated to 19% sales growth.
The question now is whether newly acquired industrial fastener sales and kiosk upgrades can make up for shrinking retail hardware volumes in 2027 as last year's price increases fade. Either pro and industrial account wins keep total growth near 8%, or falling unit demand drags growth down while debt sits above target. The third-quarter filing's volume disclosure and fourth-quarter results will tell.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐊𝐞𝐲 𝐚𝐧𝐝 𝐄𝐧𝐠𝐫𝐚𝐯𝐢𝐧𝐠 𝐊𝐢𝐨𝐬𝐤𝐬 𝐀𝐜𝐜𝐞𝐥𝐞𝐫𝐚𝐭𝐞𝐝 𝐭𝐨 𝟏𝟗% 𝐆𝐫𝐨𝐰𝐭𝐡
Robotics and Digital Solutions (RDS) is Hillman's unit for self-service key-copying and engraving machines inside retail stores. Chief executive Jon Michael Adinolfi highlighted the "high-margin Robotics and Digital Solutions segment - which had a great quarter, up 19.2%". That rate accelerated from 11.0% in the second quarter and 6.0% in the first quarter.
This matters because RDS carries an Adjusted EBITDA margin above 30%, about double the rest of the business. By our math, RDS brought in about $69.8 million of sales this quarter, while the rest of Hillman grew only 5.8% even with newly acquired hardware businesses.
What to watch: the segment table and MinuteKey 3.5 machine count in the quarterly filing and on Tuesday's call. Rising profit per machine would show the upgraded kiosks earn more after the rollout ends this year.
🟢 𝐈𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 𝐃𝐫𝐚𝐰𝐝𝐨𝐰𝐧 𝐋𝐢𝐟𝐭𝐞𝐝 𝐅𝐫𝐞𝐞 𝐂𝐚𝐬𝐡 𝐅𝐥𝐨𝐰 𝐭𝐨 $𝟓𝟏 𝐌𝐢𝐥𝐥𝐢𝐨𝐧
Last year Hillman spent cash to build up higher-cost inventory as new tariffs took effect, which squeezed its cash generation. This quarter the hardware supplier turned that stock back into cash, lifting free cash flow to $51.1 million from $9.1 million a year ago.
Across the first nine months of 2026, reducing inventory brought in $62.3 million of operating cash, compared with a $53.9 million cash drain a year earlier. That leaves $87.0 million of free cash flow so far this year, putting the company within $23.0 million of its $110 million full-year midpoint.
What to watch: fourth-quarter working capital and capital spending. Hitting the $105–115 million cash target will determine how fast the company can pay down its new acquisition debt.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐇𝐢𝐥𝐥𝐦𝐚𝐧 𝐂𝐮𝐭 𝐈𝐭𝐬 𝐒𝐚𝐥𝐞𝐬 𝐏𝐥𝐚𝐧 𝐄𝐯𝐞𝐧 𝐀𝐟𝐭𝐞𝐫 𝐁𝐮𝐲𝐢𝐧𝐠 𝐓𝐡𝐫𝐞𝐞 𝐁𝐮𝐬𝐢𝐧𝐞𝐬𝐬𝐞𝐬
"We are winning in Pro, where our channel relationships, sourcing agility, and field sales team are driving new business wins," Adinolfi said. Yet in the same release he cut the full-year net sales outlook midpoint by $25 million to $1.67 billion, "narrowing down our net sales range, given the macro environment".
• Initial 2026 sales outlook midpoint: $1.65 billion before acquisitions
• Expected 2026 sales from three acquisitions (Campbell, Delaney, Kanebridge): about $45 million in total
• Updated 2026 sales outlook midpoint: $1.67 billion, up only $20 million from the initial plan
• Fourth-quarter sales growth excluding acquisitions: about 3.3% by our math, vs 9.6% reported
This cuts against the growth story because Hillman raised its sales outlook twice earlier this year by adding acquired revenue, and has now given back more than half of those raises. By our math, underlying sales for the year are tracking about $25 million below the original plan as weaker hardware volumes offset new account wins.
What to watch: the price and unit volume breakdown for Hardware and Protective Solutions in the quarterly filing. Another high-single-digit volume drop would show higher prices and weak home-improvement demand are still hurting unit sales.
🔴🔴 𝐊𝐚𝐧𝐞𝐛𝐫𝐢𝐝𝐠𝐞 𝐃𝐞𝐚𝐥 𝐏𝐮𝐬𝐡𝐞𝐝 𝐃𝐞𝐛𝐭 𝐋𝐞𝐯𝐞𝐫𝐚𝐠𝐞 𝐭𝐨 𝟑.𝟒𝐱 𝐚𝐧𝐝 𝐂𝐮𝐭 𝐁𝐮𝐲𝐛𝐚𝐜𝐤𝐬
Hillman closed its $314.5 million purchase of Kanebridge, an industrial fastener distributor. Adinolfi said the deal "accelerates that momentum, establishing our position as a long-tail master distributor in the U. S. industrial market". While the deal expands the industrial business, it also adds debt right as underlying sales slow.
To pay for Kanebridge and refinance its loans, Hillman took on a new $735 million term loan and a $200 million add-on loan. Net debt rose by $267.2 million in the quarter to $932.6 million, pushing net debt to 3.4 times trailing Adjusted EBITDA from 2.4 times in June. Share buybacks dropped to $5.0 million from $13.3 million last quarter.
What to watch: net debt to Adjusted EBITDA over the next four quarters. Returning to the company's 2.5 times target by the end of 2027 requires pausing further deals and using cash flow for debt.
🔴 𝐇𝐢𝐠𝐡𝐞𝐫 𝐏𝐫𝐨𝐝𝐮𝐜𝐭 𝐚𝐧𝐝 𝐖𝐚𝐫𝐞𝐡𝐨𝐮𝐬𝐞 𝐂𝐨𝐬𝐭𝐬 𝐓𝐫𝐢𝐦𝐦𝐞𝐝 𝐭𝐡𝐞 𝐌𝐚𝐫𝐠𝐢𝐧
A year ago Hillman raised prices before higher-cost tariff inventory flowed through its cost of sales, lifting its third-quarter Adjusted EBITDA margin to a record 20.7%. This quarter that timing benefit disappeared, and the Adjusted EBITDA margin fell 1.0 percentage point to 19.7%, so Adjusted EBITDA grew only 2.4% on 7.7% sales growth.
By our math, cost of sales (the cost of making and buying products, excluding depreciation and amortization) rose 0.9 percentage points of revenue to 49.2%. Selling, warehouse, general and administrative expenses rose 2.0 percentage points of revenue to 34.5%, partly on $8.6 million of acquisition costs.
What to watch: fourth-quarter Adjusted EBITDA, which by our math must grow 17.5% to $67.6 million at a 16.9% margin to hit the $285 million full-year target. Missing that figure would show cost pressure extends beyond the tough third-quarter comparison.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
Several standing risks depend on segment and product tables that live in the quarterly filing or conference call rather than the earnings release.
• Personal Protective sales decline: down for three straight quarters through Q2; the 10-Q product category table will show whether Q3 stabilized.
• Hardware and Protective Solutions EBITDA margin: fell 1.5 percentage points in Q2; the 10-Q segment table will show Q3 margin performance.
• Tariff rules and China sourcing share: no update in the release on the 10% China sourcing capability or tariff refund timing.
• Big-box retail concentration and Kanebridge cross-selling: no customer concentration or post-close integration metrics reported yet.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐏𝐫𝐨𝐟𝐢𝐭 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬 (𝟐𝟔𝐐𝟑): $𝟒𝟐.𝟑 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ($𝟎.𝟐𝟐 𝐩𝐞𝐫 𝐬𝐡𝐚𝐫𝐞) ⇒ stable
Reported net income fell 73% from a year ago to $6.3 million ($0.03 per share) because Hillman booked $13.5 million of loan refinancing costs and $8.6 million of deal expenses. Excluding those one-offs and intangible amortization, profit slipped 2.1% from a year ago and per-share profit was unchanged at $0.22.
𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐬 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞 (𝟐𝟔𝐐𝟑): $𝟏𝟔𝟖.𝟐 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Money owed by customers rose 16.0% from a year ago and 46.3% from year-end, outpacing the 7.7% increase in third-quarter net sales. The jump reflects seasonal summer billings and the addition of Kanebridge's balance sheet at quarter-end, absorbing $38.8 million of operating cash over the first nine months.
𝐃𝐢𝐥𝐮𝐭𝐞𝐝 𝐬𝐡𝐚𝐫𝐞 𝐜𝐨𝐮𝐧𝐭 (𝟐𝟔𝐐𝟑): 𝟏𝟗𝟔.𝟏 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
The diluted share count fell 1.9% from a year ago (3.8 million fewer shares), which kept per-share profit excluding one-offs at $0.22 even though dollar profit dipped 2.1%. The hardware distributor spent $28.4 million buying back shares over the first nine months, but slowed repurchases to $5.0 million in Q3.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟔 𝐍𝐞𝐭 𝐒𝐚𝐥𝐞𝐬: $𝟏.𝟔𝟔𝟎–𝟏.𝟔𝟖𝟎 𝐛𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠇 cut from $1.670–1.720 billion
Cut. Management lowered the middle of the range by $25 million to $1.67 billion (7.6% annual growth), reversing the +$30 million and +$15 million acquisition-driven raises from Q1 and Q2. By our math, that leaves $400.2 million for Q4 (+9.6% from a year ago), or about 3.3% growth after stripping out expected acquired sales.
𝐅𝐘𝟐𝟔 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀: ~$𝟐𝟖𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠆 unchanged from ~$285 million
Unchanged. The target still calls for 3.5% growth for the full year, and implies a 17.1% full-year margin (up 0.3 percentage points from the August plan because sales are lower). By our math, hitting $285 million leaves $67.6 million for Q4, up 17.5% from a year ago against an easier comparison and including about $5 million from Kanebridge.
𝐅𝐘𝟐𝟔 𝐅𝐫𝐞𝐞 𝐂𝐚𝐬𝐡 𝐅𝐥𝐨𝐰: $𝟏𝟎𝟓–𝟏𝟏𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠆 unchanged from $105–115 million
Unchanged. The plan still has free cash flow more than tripling from last year's $35.1 million to $110 million at the middle of the range. After generating $87.0 million in the first nine months, the distributor needs $23.0 million in Q4 by our math, down from $51.1 million in Q3.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐝𝐢𝐝 𝐡𝐚𝐫𝐝𝐰𝐚𝐫𝐞 𝐮𝐧𝐢𝐭 𝐯𝐨𝐥𝐮𝐦𝐞𝐬 𝐟𝐚𝐥𝐥 𝐢𝐧 𝐐𝟑?
Cutting the full-year sales outlook by $25 million at the middle of the range suggests underlying hardware demand weakened further. Investors need the exact price and unit volume split for Hardware and Protective Solutions, which was down high-single digits in Q2.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐝𝐢𝐝 𝐚𝐜𝐪𝐮𝐢𝐬𝐢𝐭𝐢𝐨𝐧𝐬 𝐚𝐝𝐝 𝐭𝐨 𝐐𝟑 𝐬𝐚𝐥𝐞𝐬?
Hillman bought Campbell Chain and Delaney Hardware in Q2 and closed Kanebridge in Q3, but the release does not state their Q3 revenue. Without that figure, readers cannot separate underlying hardware sales from bought growth.
𝐇𝐨𝐰 𝐦𝐚𝐧𝐲 𝐌𝐢𝐧𝐮𝐭𝐞𝐊𝐞𝐲 𝟑.𝟓 𝐤𝐢𝐨𝐬𝐤𝐬 𝐚𝐫𝐞 𝐧𝐨𝐰 𝐢𝐧𝐬𝐭𝐚𝐥𝐥𝐞𝐝?
Robotics and Digital Solutions sales jumped 19.2%, and management previously targeted over 5,000 upgraded key machines by year-end (up from 4,500 in Q2). The machine count will show whether growth came from new placements or higher spending per machine.
𝐖𝐡𝐚𝐭 𝐢𝐬 𝐭𝐡𝐞 𝐢𝐧𝐭𝐞𝐫𝐞𝐬𝐭 𝐫𝐚𝐭𝐞 𝐨𝐧 𝐭𝐡𝐞 𝐧𝐞𝐰 $𝟗𝟑𝟓𝐌 𝐭𝐞𝐫𝐦 𝐥𝐨𝐚𝐧?
Gross debt rose to $967.7 million after the July refinancing and the August $200 million Kanebridge loan add-on. Knowing the annual interest bill is essential for modelling 2027 profit and cash available to pay down debt.

$CBT Q4 2026 earnings: Cabot's specialty chemicals grow fast, but tire carbon profit falls
Cabot's specialty chemicals division grew fast in the fourth quarter, but price cuts on tire carbon pulled total profit down. Fourth-quarter sales rose 12% from a year ago, while full-year profit per share excluding one-offs fell 11% to $6.42, near the top of the company's plan. New chief executive Erica McLaughlin set the fiscal 2027 profit per share plan at $6.15 to $6.75, which points to almost flat earnings at the middle of the range by our math.
• Revenue: $𝟏,𝟎𝟎𝟗𝐌 (+12.2% from a year ago)
• Profit per share, excluding one-offs: $𝟏.𝟔𝟏 (-5.3% from a year ago)
• Battery Materials EBITDA (FY26): $𝟒𝟑𝐌 (above the ~$40M target)
• FY27 profit per share outlook: $𝟔.𝟏𝟓–$𝟔.𝟕𝟓 (middle of the range: +0.5% growth)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because the flat 2027 profit plan offsets a strong fourth quarter in specialty chemicals and batteries. Securing the $50 million US government grant and beating the battery target helped the growth case, while a 27% profit drop in tire carbons kept the main drag in place.
The question now is whether battery additives and plant closures can lift total profit before tire carbon prices reset again. Either calendar 2027 tire contracts stabilize and let cost savings flow through, or Asian competition forces another year of lower profit per ton. Commentary on 2027 customer agreements during the first-quarter report will settle it.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐏𝐞𝐫𝐟𝐨𝐫𝐦𝐚𝐧𝐜𝐞 𝐂𝐡𝐞𝐦𝐢𝐜𝐚𝐥𝐬 𝐇𝐞𝐥𝐝 𝐈𝐭𝐬 𝐌𝐚𝐫𝐠𝐢𝐧 𝐆𝐚𝐢𝐧
Performance Chemicals makes specialty carbons, conductive additives for batteries, and fumed metal oxides used in electronics and infrastructure. New chief executive Erica McLaughlin said fourth-quarter profit was "driven by robust performance in our Performance Chemicals segment". Three months ago, management warned that rising raw material costs would catch up with earlier price increases and squeeze fourth-quarter profit per ton.
Instead, segment operating profit before interest and taxes (EBIT) jumped 43% from a year ago to $60 million, while sales grew 10% to $340 million. Operating profit margin in the division rose 4 percentage points to 17.6% because better product mix, lower costs, and higher volumes in battery materials and specialty carbons outweighed the feedstock drag.
What to watch: Performance Chemicals EBIT margin in the first quarter of fiscal 2027. Holding near 18% would show that demand from electronics and battery customers is lifting margins permanently rather than just beating a cost lag.
🟢 𝐁𝐚𝐭𝐭𝐞𝐫𝐲 𝐌𝐚𝐭𝐞𝐫𝐢𝐚𝐥𝐬 𝐁𝐞𝐚𝐭 𝐓𝐚𝐫𝐠𝐞𝐭 𝐚𝐧𝐝 𝐊𝐞𝐩𝐭 𝐆𝐫𝐚𝐧𝐭
Cabot's battery materials product line makes conductive carbon additives for electric vehicles and grid storage batteries. For fiscal 2026, the line generated $43 million in earnings before interest, taxes, depreciation, and amortization (EBITDA), which McLaughlin called "a new high for the product line" and which beat the $40 million target.
The chemical maker also resolved a standing risk around its government funding after switching its US expansion from a new Michigan plant to existing sites. It signed a modified $50 million grant with the US Department of Energy "to support our expansion of domestic production of advanced conductive additives for batteries at our facilities in Louisiana and Texas".
What to watch: whether management discloses full-year battery materials revenue in dollars on the conference call or in the annual filing. Because the line was omit from revenue tables for two quarters, investors need the top-line figure to verify if growth is slowing from the 43% pace set in the first half.
🟢 𝐃𝐞𝐛𝐭 𝐑𝐞𝐟𝐢𝐧𝐚𝐧𝐜𝐞𝐝 𝐚𝐧𝐝 𝐁𝐮𝐲𝐛𝐚𝐜𝐤𝐬 𝐑𝐞𝐬𝐮𝐦𝐞𝐝 𝐨𝐧 𝐒𝐜𝐡𝐞𝐝𝐮𝐥𝐞
Entering the fourth quarter, Cabot faced two financial commitments: refinancing a public bond maturing in September and restarting share buybacks after pausing them in the third quarter. The specialty chemicals group completed both tasks before the fiscal year ended on September 30.
Current debt due within a year fell from $260 million a year ago to $7 million, while long-term debt rose to $1.18 billion, leaving $1.5 billion in available liquidity. Management also spent $45 million on share repurchases in the quarter, bringing the full-year total to $146 million, right inside its $100 million to $200 million target.
What to watch: quarterly share repurchases in fiscal 2027. Keeping buybacks near $35 million to $45 million a quarter would continue trimming the share count by nearly 3% a year while profit growth stays muted.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐓𝐢𝐫𝐞 𝐂𝐚𝐫𝐛𝐨𝐧 𝐏𝐫𝐨𝐟𝐢𝐭 𝐅𝐞𝐥𝐥 𝐃𝐞𝐬𝐩𝐢𝐭𝐞 𝐇𝐢𝐠𝐡𝐞𝐫 𝐒𝐚𝐥𝐞𝐬
Reinforcement Materials, Cabot's largest division, sells reinforcing carbon black to tire and auto-parts makers. While McLaughlin praised the company's execution, fourth-quarter EBIT in this core business dropped 27% from a year ago to $87 million even as segment sales rose 12.6% to $634 million. Across the company, the cost of making products rose 4.3 percentage points to 79.8% of revenue, pulling gross margin down to 20.2%.
• Global Reinforcement Materials volume: up 5% from a year ago, helped by a plant purchase in Mexico and new capacity in Indonesia
• Asia Pacific and Americas volume: up 10% and 3% from a year ago
• Europe, Middle East, and Africa volume: down 7% from a year ago, worsening from a 4% drop last quarter
Volume growth did not turn into profit because gross profit per ton fell on the "outcomes of our calendar year 2026 customer agreements and less favorable regional product mix". Selling more tons in Asia while European tire production shrinks dilutes margins because Western contracts carry higher profit per ton.
What to watch: commentary on calendar year 2027 Western tire customer agreements during the first-quarter report. Another round of price cuts would prevent segment EBIT from recovering when the 2026 contract reset laps in the second quarter.
🔴🔴 𝐅𝐢𝐫𝐬𝐭 𝟐𝟎𝟐𝟕 𝐏𝐥𝐚𝐧 𝐏𝐨𝐢𝐧𝐭𝐬 𝐭𝐨 𝐅𝐥𝐚𝐭 𝐏𝐫𝐨𝐟𝐢𝐭
Investors have been waiting for fiscal 2027 to see if battery growth and plant closures can lift total earnings once the 2026 tire contract price cuts pass their one-year mark. In her first outlook as chief executive, McLaughlin set the fiscal 2027 profit per share target, excluding one-offs, at $6.15 to $6.75.
At the middle of the range, $6.45, profit per share grows just 0.5% by our math from the $6.42 earned in fiscal 2026, which itself was down 11.4% from fiscal 2025. Even with battery materials hitting $43 million in EBITDA, it accounts for just 5.9% of Cabot's $735 million in total Adjusted EBITDA by our math, too small to offset tire carbon pressure.
What to watch: the midpoint of the full-year profit outlook after the first quarter. A hold or a raise after calendar 2027 tire contracts are signed would show the initial range was cautious.
🔴 𝐏𝐥𝐚𝐧𝐭 𝐂𝐥𝐨𝐬𝐮𝐫𝐞𝐬 𝐊𝐞𝐩𝐭 𝐄𝐚𝐭𝐢𝐧𝐠 𝐈𝐧𝐭𝐨 𝐑𝐞𝐩𝐨𝐫𝐭𝐞𝐝 𝐏𝐫𝐨𝐟𝐢𝐭
To counter weak tire demand in Western markets and volatile energy costs, Cabot has been closing manufacturing units in Argentina, Wales, and the Netherlands while "investing in yield technology to improve the competitiveness of our network". Those actions are meant to save $22 million a year once completed, and we merged the cost-saving theme here because the charges are dominating reported results.
In the fourth quarter, pre-tax restructuring charges reached $15 million, bringing full-year restructuring costs to $72 million and total pre-tax one-off charges to $109 million, up from $30 million in fiscal 2025. Those expenses cut full-year reported profit per share by $2.40, leaving GAAP profit at $4.02 against $6.42 excluding one-offs.
What to watch: quarterly restructuring charges in fiscal 2027. Charges should drop toward the previously indicated $21 million total for the year as the Campana and Barry exits wrap up.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
Five standing concerns and watch items could not be read from the fourth-quarter earnings release and await the conference call or the annual report on Form 10-K.
• Underlying tire carbon volume: the release did not separate organic volume growth in the Americas and Asia from the Mexico acquisition and Indonesian capacity addition.
• Botlek plant consultation: no update on whether local consultation in the Netherlands has concluded to allow unit closures in fiscal 2027.
• European tire import duties: no commentary yet on whether December 2026 anti-dumping duties are helping early 2027 contract talks.
• Sarnia environmental compliance: no update in the release on the requested extension for sulfur dioxide controls at the Ontario plant.
• Finance chief search: McLaughlin took over as chief executive on October 1, and the release did not name a permanent replacement as chief financial officer.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐬 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞 𝐚𝐧𝐝 𝐢𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 (𝟐𝟔𝐐𝟒): $𝟏,𝟑𝟖𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Combined receivables and inventories rose 17.9% from a year ago by our math, outpacing fourth-quarter revenue growth of 12.2%. Accounts receivable jumped 19.4% to $801 million and inventories rose 15.9% to $584 million. Higher raw material costs tied up $10 million of working capital in the quarter and $68 million across the full year.
𝐅𝐫𝐞𝐞 𝐜𝐚𝐬𝐡 𝐟𝐥𝐨𝐰 (𝐅𝐘𝟐𝟔): $𝟐𝟏𝟒 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Full-year free cash flow — operating cash flow minus property and equipment additions — fell 45.3% from $391 million in fiscal 2025. Fourth-quarter free cash flow was $88 million, down 43.2% from $155 million a year ago, as lower tire carbon profit and working capital outflows outweighed a $67 million reduction in annual capital spending.
𝐃𝐢𝐥𝐮𝐭𝐞𝐝 𝐬𝐡𝐚𝐫𝐞 𝐜𝐨𝐮𝐧𝐭 (𝟐𝟔𝐐𝟒): 𝟓𝟏.𝟗 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Diluted shares fell 2.8% from 53.4 million a year ago and ticked down from 52.0 million in the third quarter. Consistent buybacks totaling $146 million across fiscal 2026 cushioned the drop in per-share profit.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟕 𝐏𝐫𝐨𝐟𝐢𝐭 𝐩𝐞𝐫 𝐬𝐡𝐚𝐫𝐞, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: $𝟔.𝟏𝟓–$𝟔.𝟕𝟓 ⇒ stable
New. The plan puts full-year profit per share at $6.45 in the middle of the range, up 0.5% from fiscal 2026 by our math. Management expects higher volumes in battery materials and electronics alongside restructuring savings to offset volatile energy costs and competitive pressure in tire carbons. Over the past two years, final profit has landed within 2% of the latest midpoint.
𝐅𝐘𝟐𝟕 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐭𝐚𝐱 𝐫𝐚𝐭𝐞: 𝟐𝟖%–𝟑𝟎% ⇒ stable
New. The expected tax rate on underlying operations matches the 28% to 30% range guided in the third quarter for fiscal 2026 and centers on the 29% rate delivered this year. It excludes discrete tax charges from valuation allowances and plant restructurings, which pushed the GAAP effective tax rate to 41% in fiscal 2026.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐚𝐭 𝐝𝐨 𝟐𝟎𝟐𝟕 𝐨𝐮𝐭𝐥𝐨𝐨𝐤 𝐚𝐬𝐬𝐮𝐦𝐩𝐭𝐢𝐨𝐧𝐬 𝐬𝐚𝐲 𝐚𝐛𝐨𝐮𝐭 𝐭𝐢𝐫𝐞 𝐜𝐨𝐧𝐭𝐫𝐚𝐜𝐭𝐬?
The $6.15 to $6.75 profit per share range implies almost no growth at the midpoint despite $22 million in planned cost savings. Investors need to know what calendar 2027 Western tire contract pricing is baked into that range.
𝐖𝐡𝐚𝐭 𝐰𝐚𝐬 𝐛𝐚𝐭𝐭𝐞𝐫𝐲 𝐦𝐚𝐭𝐞𝐫𝐢𝐚𝐥𝐬 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐢𝐧 𝐝𝐨𝐥𝐥𝐚𝐫𝐬 𝐟𝐨𝐫 𝟐𝟎𝟐𝟔?
Management reported $43 million in battery materials EBITDA but omitted the revenue growth rate for a second straight quarter. Disclosing annual dollar sales would show whether pricing or volume drove the EBITDA beat.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐨𝐟 𝐭𝐡𝐞 𝟓% 𝐯𝐨𝐥𝐮𝐦𝐞 𝐠𝐫𝐨𝐰𝐭𝐡 𝐰𝐚𝐬 𝐮𝐧𝐝𝐞𝐫𝐥𝐲𝐢𝐧𝐠?
Reinforcement Materials volume rose 10% in Asia and 3% in the Americas with help from new Indonesian capacity and the Mexico acquisition. Breaking out sales from businesses owned a year ago would show true tire demand.
𝐖𝐡𝐞𝐧 𝐰𝐢𝐥𝐥 𝐂𝐚𝐛𝐨𝐭 𝐧𝐚𝐦𝐞 𝐚 𝐩𝐞𝐫𝐦𝐚𝐧𝐞𝐧𝐭 𝐜𝐡𝐢𝐞𝐟 𝐟𝐢𝐧𝐚𝐧𝐜𝐢𝐚𝐥 𝐨𝐟𝐟𝐢𝐜𝐞𝐫?
Erica McLaughlin stepped up from finance chief to chief executive on October 1, and the earnings release did not mention a successor for the finance role during an active multi-plant restructuring.

$HSTM Q3 2026 earnings: HealthStream raises its full-year plan, but operating profit falls 13%
HealthStream, which sells software for hospitals to train and credential staff, grew revenue through acquisitions while its profit fell. Total sales rose 9% to $83 million, but operating profit dropped 13% on higher software and staffing costs. Chief executive Robert A. Frist, Jr. raised the full-year outlook, though by our math the plan has fourth-quarter revenue growth slowing to 5%.
• Sales from businesses owned a year ago: +𝟒.𝟕% (by our math, vs +8.9% total revenue growth)
• Operating income: $𝟔.𝟔𝐌 (-13% from a year ago)
• Cash and marketable securities: $𝟏𝟏𝟓.𝟐𝐌 (after a $40M private stock sale at $29.50)
• Full-year revenue outlook: 𝐑𝐚𝐢𝐬𝐞𝐝 $𝟐.𝟓𝐌 (middle of the range: 9.2% growth)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because a third-quarter beat against a cautious forecast offsets slower underlying growth. Sales from businesses owned a year ago grew just under 5% by our math, while a $40 million stock sale at $29.50 per share gives the company $115 million in cash for new deals. One caution: the updated outlook still points to a 7% drop in fourth-quarter Adjusted EBITDA as platform spending continues.
The question now is whether heavy platform spending and new acquisitions will lift underlying growth back above 5% next year. Either new hStream platform bundles accelerate hospital bookings, or slowing growth in flagship credentialing software keeps underlying growth in the low single digits. The fourth-quarter backlog and product growth disclosures on the call will show which way it breaks.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢 𝐓𝐡𝐢𝐫𝐝 𝐐𝐮𝐚𝐫𝐭𝐞𝐫 𝐁𝐞𝐚𝐭 𝐋𝐢𝐟𝐭𝐬 𝐭𝐡𝐞 𝐅𝐮𝐥𝐥-𝐘𝐞𝐚𝐫 𝐏𝐥𝐚𝐧
HealthStream provides software for hospitals to train, credential and schedule clinical staff. Three months ago, management forecast roughly 8% revenue growth and a 22% Adjusted EBITDA margin for the third quarter. Adjusted EBITDA is profit before interest, taxes, depreciation, stock pay and one-offs.
The company beat both targets, with sales up 8.9% to $83.3 million and the Adjusted EBITDA margin reaching 23.2% by our math. Because of the third-quarter beat, management raised the middle of its full-year outlook by $2.5 million for revenue, $1.25 million for net income and $1.5 million for Adjusted EBITDA. Beating the quarterly plan says the prior forecast was cautious, not that second-half spending pressure is gone.
What to watch: fourth-quarter revenue against the $82.7 million to $84.8 million range implied by the full-year outlook. A result above the top of that range would show that customer renewals in December outpaced management's cautious second-half assumptions.
🟢 𝐀 $𝟒𝟎 𝐌𝐢𝐥𝐥𝐢𝐨𝐧 𝐒𝐭𝐨𝐜𝐤 𝐒𝐚𝐥𝐞 𝐋𝐢𝐟𝐭𝐬 𝐂𝐚𝐬𝐡 𝐟𝐨𝐫 𝐃𝐞𝐚𝐥𝐬
After buying Virsys12, a provider data manager, and MissionCare Collective, a caregiver network, in late 2025, HealthStream spent $9.3 million buying back 432,476 of its own shares in the first half of 2026 at an average price of $21.50. The company did not buy back any shares in the third quarter, and let its repurchase plan expire on September 12.
Two days later, the Nashville group sold 1.36 million shares to WJRJJ Ventures at $29.50 each, raising $40 million in cash. That lifted cash and marketable securities to $115.2 million with zero debt, which management will use for "continued investment in its solutions, working capital, potential acquisitions, and other strategic initiatives" while issuing shares 37% above its first-half buyback price.
What to watch: acquisition announcements over the next two quarters. Putting the new cash into healthcare software acquisitions would keep total revenue growing near 9% even as last year's deals enter the comparison base.
🟢 𝐏𝐨𝐬𝐢𝐭𝐢𝐯𝐞𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐭𝐞𝐬𝐭
Chief executive Robert A. Frist, Jr. said the hStream platform connects "verified healthcare professionals and students, healthcare organizations, and industry partners in one powerful ecosystem". However, the earnings release did not update three product drivers that live in the conference call and quarterly filing.
• hStream Insights adoption: whether HealthStream brought CredentialStream, its hospital staff credentialing software, onto the data reporting layer as scheduled for the third quarter.
• Career Networks revenue: whether the 15 unbudgeted staff hired last quarter lifted sales in the job and clinical rotation networks.
• Multi-year bundle contracts: whether the Competency Suite, which packages clinical training tools, maintained double-digit growth after slowing in the first half.
What to watch: product growth rates and platform user counts in the third-quarter conference call remarks. Rising adoption across those three products would show the new platform spending is winning hospital contracts.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐄𝐱𝐢𝐬𝐭𝐢𝐧𝐠-𝐏𝐨𝐫𝐭𝐟𝐨𝐥𝐢𝐨 𝐆𝐫𝐨𝐰𝐭𝐡 𝐒𝐥𝐨𝐰𝐞𝐝 𝐁𝐞𝐥𝐨𝐰 𝟓%
Headline revenue rose $6.8 million, or 8.9%, from a year ago, helped by Virsys12 and MissionCare Collective, which HealthStream bought in the fourth quarter of 2025. To see how the business is performing on its own, we separate those acquired businesses and the second quarter's $2.0 million one-time contract catch-up from the existing product lines.
• Sales from businesses owned a year ago: up $3.6 million, or 4.7% by our math, down from 5.2% to 5.8% over the prior three quarters excluding one-offs
• Acquired revenue from Virsys12 and MissionCare: $3.2 million, adding 4.2 percentage points to total growth by our math
• Implied fourth-quarter total revenue growth: 5.1% at the middle of the full-year outlook by our math
This matters because the company will lap the fourth-quarter 2025 acquisitions next quarter, cutting their contribution to growth in half. With underlying sales growth now below the company's 5% to 7% medium-term goal, total growth is set to drop toward 5% in the fourth quarter.
What to watch: fourth-quarter underlying revenue growth in the full-year report. A second straight reading below 5% would show that slowing growth in older products is outweighing new platform sales.
🔴🔴 𝐇𝐢𝐠𝐡𝐞𝐫 𝐏𝐥𝐚𝐭𝐟𝐨𝐫𝐦 𝐂𝐨𝐬𝐭𝐬 𝐂𝐮𝐭 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐏𝐫𝐨𝐟𝐢𝐭 𝟏𝟑%
"Our third quarter continued that progress, with revenues up 8.9% to $83.3 million, and we are raising our full-year guidance," chief executive Robert A. Frist, Jr. said after highlighting nine-month operating income growth of 25.7%. In the third quarter alone, however, operating income fell 13.0% from a year ago to $6.6 million, and net income dropped 11.7% to $5.4 million.
Profit fell because operating costs grew faster than sales to fund investments "primarily in our platform and enterprise applications, including personnel costs, third-party software expenses, cloud hosting, and amortization expense from our fourth quarter 2025 acquisitions". By our math, cost of revenues—the direct cost of delivering software and services—rose 1.4 percentage points of revenue to 36.0%, and general and administrative overhead rose 0.7 percentage points to 10.3%.
Even excluding $250,000 of cybersecurity incident costs, operating income fell 9.7% by our math, and Adjusted EBITDA grew only 1.0% to $19.3 million. What to watch: fourth-quarter Adjusted EBITDA against the $17.0 million to $18.0 million implied by the outlook. That implied range represents a 7.2% drop at the middle from a year ago, showing that heavy spending will keep pressuring margins through year-end.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
HealthStream booked $250,000 of costs after insurance in the third quarter from its July 29 cybersecurity incident and included $300,000 for the full year, adding both back to Adjusted EBITDA. Five standing concerns require disclosures from the conference call or the quarterly filing that are not in the earnings release.
• CredentialStream growth: whether the flagship credentialing software slowed again after dropping from 23% growth a year ago to 14% last quarter; the call remarks will show it.
• Remaining performance obligations (RPO, total contracted backlog): whether backlog held near $685 million ahead of the fourth-quarter renewal season; the quarterly filing will show it.
• Legacy software attrition: whether older scheduling and credentialing products shrank by more than the $1.3 million year-over-year drag seen last quarter.
• Customer data fallout and hospital budgets: whether the data breach at 65 credentialing customers or Medicaid budget cuts hurt renewals or triggered legal claims.
• Credit line and legal items: whether the $50 million credit facility maturing October 6, 2026 was renewed, and the status of the sales overtime lawsuit.
What to watch: the RPO backlog table and cybersecurity footnote in the third-quarter 10-Q filing. A sequential drop in backlog below $680 million or new customer breach claims would show that slower underlying growth is carrying into 2027.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐓𝐨𝐭𝐚𝐥 𝐝𝐞𝐟𝐞𝐫𝐫𝐞𝐝 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 (𝟐𝟔𝐐𝟑): $𝟗𝟐.𝟗 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Deferred revenue—cash customers have paid upfront for software subscriptions not yet delivered—slipped $1.6 million from last quarter to $92.9 million ($91.9 million current plus $1.0 million noncurrent). Current deferred revenue rose 7.2% from a year ago by our math, trailing the 8.9% revenue growth rate as acquired balances work down.
𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐬 𝐚𝐧𝐝 𝐮𝐧𝐛𝐢𝐥𝐥𝐞𝐝 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞𝐬 (𝟐𝟔𝐐𝟑): $𝟑𝟖.𝟕 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Money owed by customers rose 14.8% from a year ago to $38.7 million, up from $36.8 million at the end of June. Receivables grew faster than the 8.9% sales increase, meaning a larger share of third-quarter billings remained uncollected at quarter-end.
𝐅𝐫𝐞𝐞 𝐜𝐚𝐬𝐡 𝐟𝐥𝐨𝐰 (𝟐𝟔𝐐𝟑): $𝟏𝟎.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
By our math, third-quarter operating cash flow of $17.4 million minus $7.4 million of cash capital spending left $10.0 million of free cash flow, down 5.0% from $10.5 million a year ago. For the first nine months, free cash flow rose 40.3% to $34.6 million on lower first-half capital spending.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟔 𝐑𝐞𝐯𝐞𝐧𝐮𝐞: $𝟑𝟑𝟏.𝟎–𝟑𝟑𝟑.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠅 raised from $327.0–332.0 million
Raised. The middle of the full-year outlook moved up $2.5 million to $332.0 million, or 9.2% growth from 2025. By our math, that leaves $83.8 million for the fourth quarter, or 5.1% growth from a year ago against 8.9% in the third quarter as the late-2025 acquisitions lap. It is the second raise this year after +$3.0 million last quarter.
𝐅𝐘𝟐𝟔 𝐍𝐞𝐭 𝐈𝐧𝐜𝐨𝐦𝐞: $𝟐𝟏.𝟖–𝟐𝟐.𝟒 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠅 raised from $19.5–22.2 million
Raised. The middle of the range rose $1.25 million to $22.1 million, reversing last quarter's cut and pointing to 20.5% growth for the year. By our math, that implies $4.15 million in the fourth quarter, up 63.7% from a year ago when a $3.8 million stock gift to employees depressed profit, and helped by higher interest income on the new $40 million cash balance.
𝐅𝐘𝟐𝟔 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀: $𝟕𝟕.𝟎–𝟕𝟖.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠅 raised from $74.0–78.0 million
Raised. HealthStream lifted the bottom of the range by $3.0 million, raising the middle by $1.5 million to $77.5 million, or 8.0% growth for the year. By our math, that leaves $17.5 million for the fourth quarter—down 7.2% from $18.8 million a year ago, with the margin dropping to 20.9% on platform and hiring expenses. It is the second raise this year (+$1.0M, +$1.5M).
𝐅𝐘𝟐𝟔 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐄𝐱𝐩𝐞𝐧𝐝𝐢𝐭𝐮𝐫𝐞𝐬: $𝟑𝟏.𝟎–𝟑𝟒.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠆 unchanged from $31.0–34.0 million
Unchanged. The plan still calls for $32.5 million at the middle of the range, up 1.9% from $31.9 million in 2025. With $23.4 million incurred through nine months ($15.9 million in the first half plus $7.5 million in the third quarter), the outlook leaves $7.6 million to $10.6 million of capital spending for the fourth quarter.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐲 𝐬𝐞𝐥𝐥 𝐬𝐭𝐨𝐜𝐤 𝐚𝐭 $𝟐𝟗.𝟓𝟎 𝐰𝐢𝐭𝐡 $𝟕𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐢𝐧 𝐜𝐚𝐬𝐡?
HealthStream already held over $75 million in cash and no debt before issuing $40 million of stock to WJRJJ Ventures. Does management have a large acquisition in late-stage talks that required immediate equity funding?
𝐖𝐡𝐚𝐭 𝐬𝐥𝐨𝐰𝐞𝐝 𝐞𝐱𝐢𝐬𝐭𝐢𝐧𝐠-𝐩𝐨𝐫𝐭𝐟𝐨𝐥𝐢𝐨 𝐠𝐫𝐨𝐰𝐭𝐡 𝐭𝐨 𝟒.𝟕%?
Sales growth from businesses owned a year ago slipped to 4.7% by our math, down from roughly 5.6% in the first half. How much of that slowdown came from CredentialStream versus older products running off?
𝐖𝐡𝐚𝐭 𝐢𝐬 𝐭𝐡𝐞 𝐜𝐨𝐧𝐭𝐫𝐚𝐜𝐭𝐞𝐝 𝐛𝐚𝐜𝐤𝐥𝐨𝐠 𝐡𝐞𝐚𝐝𝐢𝐧𝐠 𝐢𝐧𝐭𝐨 𝐐𝟒?
Remaining performance obligations stood at $685 million in June, and current deferred revenue grew 7.2% in the third quarter. What was the total backlog at September 30 ahead of the fourth-quarter renewal season?
𝐃𝐢𝐝 𝐭𝐡𝐞 𝐉𝐮𝐥𝐲 𝐝𝐚𝐭𝐚 𝐛𝐫𝐞𝐚𝐜𝐡 𝐜𝐚𝐮𝐬𝐞 𝐚𝐧𝐲 𝐜𝐮𝐬𝐭𝐨𝐦𝐞𝐫 𝐜𝐡𝐮𝐫𝐧?
The company booked $250,000 of cybersecurity expenses after insurance in the third quarter and expects $50,000 more in the fourth. Have any of the 65 affected credentialing customers delayed renewals or sought compensation?

$DHC Q3 2026 earnings: Diversified Healthcare senior housing grows, but manager fees cut profit
Diversified Healthcare Trust, an owner of senior living and medical buildings, filled more rooms while manager fees reduced cash flow. Profit from properties owned for a year rose 26%, as chief executive Christopher Bilotto pointed to senior housing occupancy reaching 84.4%. The trust raised its full-year senior housing profit target and leased seven nursing homes to cut upkeep costs, though by our math the plan points to growth slowing in the fourth quarter.
• Same-property cash NOI: $𝟕𝟕.𝟗𝐌 (+25.6% from a year ago)
• Senior housing same-property occupancy: 𝟖𝟒.𝟒% (+1.3 percentage points from last quarter)
• Normalized FFO per share: $𝟎.𝟏𝟑 ($0.02 a year ago (after $0.02 fee deduction))
• Full-year senior housing NOI outlook: 𝐑𝐚𝐢𝐬𝐞𝐝 $𝟓𝐌 (middle of the range: $195M (+33% YoY))
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🟢 Bullish
The story got better because senior housing occupancy jumped after a slow first half and a new nursing home lease locks in higher cash flow with less capital spending. One caution: following Securities and Exchange Commission input, the trust now deducts external manager RMR's $29 million estimated incentive fee from its cash profit and leverage metrics, which cut the full-year cash profit outlook and lifted net debt to 8.2 times cash flow.
The question now is whether senior housing profit can grow fast enough to offset biotech tenant departures and higher interest costs when $640 million of debt comes due in early 2028. Optimists point to rising occupancy and $4 billion of mortgage-free properties; skeptics note that incentive fees and capital spending leave little free cash. Fourth-quarter occupancy and the final January manager fee payout will show how much cash the business keeps.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐒𝐞𝐧𝐢𝐨𝐫 𝐇𝐨𝐮𝐬𝐢𝐧𝐠 𝐎𝐜𝐜𝐮𝐩𝐚𝐧𝐜𝐲 𝐚𝐧𝐝 𝐏𝐫𝐨𝐟𝐢𝐭 𝐊𝐞𝐩𝐭 𝐂𝐥𝐢𝐦𝐛𝐢𝐧𝐠
Diversified Healthcare Trust relies on its Senior Housing Operating Portfolio (SHOP), where it owns the buildings and pays managers to run them, for over 60% of its property profit. "These results demonstrate the continued success of our operator transition strategy and strong execution by our operating partners," chief executive Christopher Bilotto said. After a slow start to the year, occupancy in communities owned for at least a year jumped 1.3 percentage points from last quarter to 84.4%.
• Same-property senior housing net operating income (NOI): $48.0 million, up 50.4% from a year ago
• Same-property profit margin: 15.8%, up 4.7 percentage points from a year ago as property operating costs fell from 88.9% of segment revenue to 84.2%
• Average monthly rate: $5,696, up 5.2% from a year ago
• Full-year senior housing NOI outlook: raised by $5 million at the middle of the range, to $190–200 million
The jump from a year ago looks larger than the underlying trend because last year's third quarter included heavy labor costs from switching operators. Even so, third-quarter segment NOI of $49.7 million beat the $43.9–48.9 million quarterly pace that the prior full-year plan pointed to by our math, despite higher summer utility bills. Management trimmed its full-year same-property revenue growth assumption from 6.6% to 6.3%, but lower operating expense growth of 2.3% more than made up for it.
What to watch: fourth-quarter same-property senior housing NOI against the $50.7 million implied by the full-year outlook. Clearing that mark would show that rising occupancy can lift profit without relying on one-time cost rebates.
🟢 𝐒𝐤𝐢𝐥𝐥𝐞𝐝 𝐍𝐮𝐫𝐬𝐢𝐧𝐠 𝐋𝐞𝐚𝐬𝐞 𝐒𝐰𝐚𝐩𝐬 𝐂𝐚𝐩𝐞𝐱 𝐟𝐨𝐫 𝐅𝐢𝐱𝐞𝐝 𝐑𝐞𝐧𝐭
On October 1, the healthcare landlord moved seven skilled nursing facilities with 807 units out of its managed senior housing portfolio and into a 15-year lease with subsidiaries of The Ensign Group. Under this triple net lease structure, the tenant pays all property operating expenses and capital upkeep. Bilotto said the deal will generate $8.0 million in first-year annual rent "while significantly reducing our future capital expenditure requirements".
Over the prior twelve months, those seven properties produced $5.1 million of property profit and required $1.6 million of capital spending, leaving $3.5 million of net cash flow by our math. The new lease more than doubles that cash contribution and removes operating risk. Alongside this shift, the trust cut its full-year senior housing recurring capital spending plan by $10 million, to $70–80 million, while keeping its two major building conversions in Arizona and Maryland on track for completion by early 2027.
What to watch: first-quarter 2027 triple net leased senior living NOI and recurring capital spending. Those figures will show the first full quarter of the $8.0 million annual rent run-rate and confirm whether capital upkeep stays lower.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐈𝐧𝐜𝐞𝐧𝐭𝐢𝐯𝐞 𝐅𝐞𝐞𝐬 𝐂𝐮𝐭 𝐑𝐞𝐩𝐨𝐫𝐭𝐞𝐝 𝐂𝐚𝐬𝐡 𝐅𝐥𝐨𝐰 𝐎𝐮𝐭𝐥𝐨𝐨𝐤
The RMR Group manages the trust and earns an annual incentive fee tied to the company's three-year total shareholder return compared to a healthcare real estate index. Previously, management excluded these accrued fees from Adjusted EBITDAre (property earnings before interest, taxes, depreciation and one-offs) and Normalized FFO (funds from operations, a standard REIT cash profit measure) during the first three quarters of the year. This quarter, "based on recent SEC input", the trust began deducting the fee in every period and restated prior quarters.
While Bilotto highlighted that Normalized FFO rose to $0.13 per share from $0.02 a year ago, the accounting change cut the full-year Normalized FFO outlook by $0.10 at the middle of the range, to $0.46–0.52 per share. The full-year estimate now includes $29.3 million, or $0.12 per share, of incentive fees payable to RMR in January 2027, with $22.0 million already accrued through September. Because the fee depends on share performance rather than property cash flow, it drains cash while shareholders still receive a $0.01 quarterly dividend.
What to watch: the final 2026 incentive management fee recorded in fourth-quarter general and administrative expense. That January 2027 cash payout will directly reduce cash available for debt reduction.
🔴🔴 𝐁𝐚𝐥𝐚𝐧𝐜𝐞-𝐒𝐡𝐞𝐞𝐭 𝐋𝐞𝐯𝐞𝐫𝐚𝐠𝐞 𝐓𝐢𝐜𝐤𝐞𝐝 𝐔𝐩 𝐀𝐟𝐭𝐞𝐫 𝐅𝐞𝐞 𝐑𝐞𝐬𝐭𝐚𝐭𝐞𝐦𝐞𝐧𝐭
Over the past year, the real estate trust repaired its immediate balance sheet by selling properties and paying off near-term debt, which lifted its ratio of Adjusted EBITDAre to interest expense from 1.2x a year ago to 2.0x this quarter. Supporters point to that improved interest coverage and $4.0 billion of properties free of mortgages as proof that the company can handle its upcoming debt maturities.
However, deducting RMR's incentive fees from Adjusted EBITDAre raised the company's reported net debt to annualized EBITDAre ratio by 0.8x across the board. Instead of sitting at 7.1x as originally reported in the second quarter, net leverage was recast to 7.9x for the second quarter and rose to 8.2x in the third quarter, moving away from management's 6.5x–7.5x target. Meanwhile, the trust faces $640 million of debt maturing in early 2028—a $500 million bond at 4.75% in February and a $140 million mortgage in March—against $260.7 million of total liquidity.
What to watch: net debt to annualized Adjusted EBITDAre in the fourth quarter and any refinancing announcements for the February 2028 notes. Repricing that 4.75% bond near current secured rates of roughly 7% would add over $10 million in annual interest costs.
🔴 𝐌𝐞𝐝𝐢𝐜𝐚𝐥 𝐎𝐟𝐟𝐢𝐜𝐞 𝐚𝐧𝐝 𝐋𝐢𝐟𝐞 𝐒𝐜𝐢𝐞𝐧𝐜𝐞 𝐕𝐚𝐜𝐚𝐧𝐜𝐢𝐞𝐬 𝐖𝐞𝐢𝐠𝐡 𝐨𝐧 𝐎𝐜𝐜𝐮𝐩𝐚𝐧𝐜𝐲
Outside of senior housing, the trust owns 67 medical office and life science buildings that generate 30% of its property profit. The company leased 130,000 square feet in this segment during the quarter at rents 25.2% above prior levels, though that required $3.8 million in tenant improvements and concessions, or $29.47 per square foot. At the same time, occupancy in properties owned for a year fell 1.2 percentage points from last quarter to 94.5% "primarily due to a previously disclosed tenant vacating a property".
Total segment occupancy dropped 3.8 percentage points from the second quarter to 88.4%, and cash property profit slipped 1.6% from a year ago on a same-property basis to $22.9 million. More departures are ahead: life science tenant THINK Surgical, which pays $2.2 million in annual rent across 75,920 square feet, is scheduled to vacate in 2026. To trim carrying costs on empty buildings, the company agreed to sell a vacant 126,225-square-foot property in Durham, North Carolina for $10.5 million.
What to watch: fourth-quarter occupancy and cash NOI in the medical office and life science portfolio after the remaining 2026 lease expirations take effect. A further drop would show that new leasing is not yet keeping pace with biotech departures.
🔴 𝐎𝐩𝐞𝐫𝐚𝐭𝐨𝐫 𝐂𝐨𝐧𝐜𝐞𝐧𝐭𝐫𝐚𝐭𝐢𝐨𝐧 𝐚𝐧𝐝 𝐍𝐞𝐰 𝐌𝐚𝐧𝐚𝐠𝐞𝐫 𝐓𝐫𝐚𝐧𝐬𝐢𝐭𝐢𝐨𝐧𝐬
Because the trust cannot operate senior living communities directly under real estate tax rules, its results depend on third-party managers. Following last year's transfer of 116 communities to new operators, management concentration remains high: two firms, Discovery Senior Living and Sinceri Senior Living, manage 12,354 units and generate 47.1% of total senior housing property profit.
Operator turnover is also not completely finished. In September, the company gave notice to terminate its management contracts with Oaks Senior Living and plans to move six communities with 486 units—which generated $1.7 million of third-quarter NOI—to a new manager as early as the fourth quarter. Prior operator switches caused temporary labor cost spikes and occupancy dips during the handover period.
What to watch: fourth-quarter senior housing operating expenses during the six-community handover. Any spike in transition labor costs would test whether the portfolio can absorb manager changes without denting margins.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐂𝐚𝐬𝐡 𝐚𝐯𝐚𝐢𝐥𝐚𝐛𝐥𝐞 𝐟𝐨𝐫 𝐝𝐢𝐬𝐭𝐫𝐢𝐛𝐮𝐭𝐢𝐨𝐧 (𝟐𝟔𝐐𝟑): $𝟔.𝟖 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Cash available for distribution (CAD)—cash profit after routine property upkeep—fell to $6.8 million ($0.03 per share) from $8.5 million last quarter and $11.5 million a year ago. The drop reflects recurring capital spending rising from $18.7 million in the first quarter and $22.9 million in the second to $26.1 million this quarter.
𝐍𝐞𝐭 𝐝𝐞𝐛𝐭 (𝟐𝟔𝐐𝟑): $𝟐.𝟑𝟑 𝐛𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Net debt—total debt principal of $2.44 billion minus $110.7 million of cash—fell 9.6% from $2.58 billion a year ago following last year's property sales. Sequentially, net debt ticked up slightly from $2.33 billion in the second quarter as cash on hand declined by $6.1 million.
𝐍𝐞𝐭 𝐥𝐨𝐬𝐬 (𝟐𝟔𝐐𝟑): $𝟓𝟎.𝟐 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇄ reversing
The accounting net loss widened from $37.4 million ($0.16 per share) in the second quarter to $50.2 million ($0.21 per share), though it narrowed from $164.0 million a year ago. This quarter's loss included $14.5 million of property write-downs and $62.9 million of depreciation.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟔 𝐒𝐚𝐦𝐞 𝐏𝐫𝐨𝐩𝐞𝐫𝐭𝐲 𝐍𝐎𝐈: $𝟑𝟏𝟐.𝟎–𝟑𝟐𝟖.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠅 raised from $307.0–323.0 million
Raised. Management lifted the full-year same-property profit outlook by $5.0 million at the middle of the range, to about 17.0% growth from a year ago. All of the increase came from senior housing, which moved up $5.0 million to $190.0–200.0 million, while medical office and life science stayed at $94.0–98.0 million. By our math, the plan leaves $81.9 million for the fourth quarter, or 16.9% growth from a year ago.
𝐅𝐘𝟐𝟔 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀𝐫𝐞: $𝟐𝟕𝟓.𝟕–𝟐𝟗𝟎.𝟕 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠇 cut from $300.0–315.0 million
Cut on an accounting change, raised underlying. Including $29.3 million of estimated RMR incentive fees lowered the range by $24.3 million at the middle; excluding that fee, the underlying outlook rose by $5.0 million. By our math, the updated middle of the range leaves $70.3 million for the fourth quarter, down from $73.4 million in the third quarter and up 5.4% from a year ago.
𝐅𝐘𝟐𝟔 𝐍𝐨𝐫𝐦𝐚𝐥𝐢𝐳𝐞𝐝 𝐅𝐅𝐎: $𝟏𝟏𝟎.𝟕–𝟏𝟐𝟓.𝟕 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇒ stable
🠇 cut from $135.0–150.0 million
Cut on an accounting change, raised underlying. Deducting the $29.3 million estimated incentive fee lowered the range by $24.3 million at the middle, meaning the underlying cash profit outlook rose by $5.0 million. By our math, the middle of the range implies $32.1 million in the fourth quarter, up from $30.7 million in the third quarter.
𝐅𝐘𝟐𝟔 𝐍𝐨𝐫𝐦𝐚𝐥𝐢𝐳𝐞𝐝 𝐅𝐅𝐎 𝐩𝐞𝐫 𝐂𝐨𝐦𝐦𝐨𝐧 𝐒𝐡𝐚𝐫𝐞: $𝟎.𝟒𝟔–𝟎.𝟓𝟐 ⇒ stable
🠇 cut from $0.56–0.62
Cut on an accounting change, raised underlying. Including $0.12 per share of estimated incentive management fees reduced the middle of the range by $0.10, reflecting a $0.02 per share underlying raise. With $0.36 per share earned through nine months, the middle of the range leaves $0.13 per share for the fourth quarter, matching the third quarter.
𝐅𝐘𝟐𝟔 𝐑𝐞𝐜𝐮𝐫𝐫𝐢𝐧𝐠 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐄𝐱𝐩𝐞𝐧𝐝𝐢𝐭𝐮𝐫𝐞𝐬: $𝟗𝟎.𝟎–𝟏𝟎𝟓.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠇 cut from $100.0–115.0 million
Cut. The trust reduced its full-year routine property upkeep budget by $10.0 million at the middle of the range, entirely within senior housing ($70.0–80.0 million vs $80.0–90.0 million previously). With $67.8 million spent in the first nine months, the middle of the range implies $29.7 million of spending in the fourth quarter, up from $26.1 million in the third.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐚𝐭 𝐚𝐫𝐞 𝐭𝐡𝐞 𝐫𝐞𝐧𝐭 𝐭𝐞𝐫𝐦𝐬 𝐨𝐧 𝐭𝐡𝐞 𝐯𝐚𝐜𝐚𝐭𝐞𝐝 𝐛𝐢𝐨𝐭𝐞𝐜𝐡 𝐬𝐩𝐚𝐜𝐞𝐬?
Same-property medical office and life science occupancy fell 1.2 percentage points this quarter after a tenant left, and THINK Surgical ($2.2 million annual rent) is set to vacate. Investors need to know how much rent replacement tenants are paying on the vacated spaces and when cash rent begins.
𝐇𝐨𝐰 𝐰𝐢𝐥𝐥 𝐃𝐇𝐂 𝐫𝐞𝐟𝐢𝐧𝐚𝐧𝐜𝐞 𝐭𝐡𝐞 $𝟔𝟒𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝟐𝟎𝟐𝟖 𝐝𝐞𝐛𝐭 𝐰𝐚𝐥𝐥?
A $500 million bond at 4.75% matures in February 2028 and a $140 million floating-rate mortgage matures in March 2028, against $260.7 million of liquidity today. Management has not yet detailed how much of this debt it plans to pay down via asset sales versus refinancing at higher secured rates.
𝐇𝐚𝐯𝐞 𝐥𝐞𝐠𝐚𝐜𝐲 𝐬𝐞𝐧𝐢𝐨𝐫 𝐡𝐨𝐮𝐬𝐢𝐧𝐠 𝐨𝐩𝐞𝐫𝐚𝐭𝐨𝐫𝐬 𝐬𝐢𝐠𝐧𝐞𝐝 𝐭𝐡𝐞 𝐧𝐞𝐰 𝐟𝐞𝐞 𝐜𝐨𝐧𝐭𝐫𝐚𝐜𝐭𝐬?
Last quarter, management said it was renegotiating contracts across more than 80 communities to lower base fees for 2027, and in September it terminated Oaks Senior Living across six properties. The release did not state how many legacy agreements are finalized for January.
𝐇𝐨𝐰 𝐚𝐫𝐞 𝐭𝐡𝐞 𝟏𝟏𝟔 𝐭𝐫𝐚𝐧𝐬𝐢𝐭𝐢𝐨𝐧𝐞𝐝 𝐜𝐨𝐦𝐦𝐮𝐧𝐢𝐭𝐢𝐞𝐬 𝐩𝐞𝐫𝐟𝐨𝐫𝐦𝐢𝐧𝐠 𝐯𝐞𝐫𝐬𝐮𝐬 𝐥𝐞𝐠𝐚𝐜𝐲 𝐩𝐫𝐨𝐩𝐞𝐫𝐭𝐢𝐞𝐬?
Same-property senior housing occupancy rose to 84.4% and profit margin reached 15.8%, but the release combines all 184 comparable properties. Splitting occupancy and margin between the communities transferred from AlerisLife last year and the rest of the portfolio would show where the gains are coming from.

$FTEL Q2 2026 earnings: GMEX Robotics gym sales inch up, but crypto losses mount
GMEX Robotics, the Australian online seller of gym equipment formerly called Fitell, pivoted into cryptocurrency investing while its core retail losses widened. Six-month merchandise revenue edged up 3% to $2.7 million on promotional order growth, and chief executive Yinying Lu restated the half-year accounts to apply fair value rules to new convertible debt. Even after the accounting revision, consulting fees and a $4.7 million unrealized crypto loss pushed the six-month net loss to $7.0 million.
• Merchandise revenue (6M): $𝟐.𝟕𝟑𝐌 (+3.2% from a year ago)
• Operating loss (6M): $𝟒.𝟎𝟕𝐌 ($1.17M loss a year ago)
• Net loss, excluding one-offs (6M): $𝟑.𝟕𝟗𝐌 (+125.6% from a year ago)
• Common shares outstanding: 𝟏.𝟔𝟎𝐌 (+407% in six months)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🔴🔴 Very Bearish
The story got worse because financing and advisory costs overwhelmed the tiny fitness equipment business. Borrowing $65 million via variable-rate convertible notes to buy digital tokens triggered fivefold share dilution in six months and drove operating cash burn to $4.4 million. One positive: excluding a one-off consignment inventory write-down, underlying retail gross margin held steady at 38% by our math.
The question now is whether the company can stop its cash burn and share dilution before unrestricted funds run out. Either management cuts consulting spend and unlocks its restricted stablecoin collateral, or variable-price note conversions continue to multiply the share count to cover expenses. The fiscal 2026 annual report will show whether the cash balance and share count stabilized.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢 𝐏𝐫𝐨𝐦𝐨𝐭𝐢𝐨𝐧𝐬 𝐋𝐢𝐟𝐭𝐞𝐝 𝐀𝐮𝐬𝐭𝐫𝐚𝐥𝐢𝐚𝐧 𝐆𝐲𝐦 𝐄𝐪𝐮𝐢𝐩𝐦𝐞𝐧𝐭 𝐎𝐫𝐝𝐞𝐫𝐬
GMEX Robotics, formerly known as Fitell, generates all of its operating revenue by selling gym and fitness equipment in Australia through its subsidiary GD Wellness. Merchandise sales rose 3.2% from a year ago to $2.73 million in the six months ended December 31, 2025. The company attributed this gain to "increased efforts on our promotional campaign and exploring new channels to solicit new customers".
Customer order volume grew 8.0% from a year ago to 11,563 orders, which offset a 4.4% drop in average revenue per order to $236.15. "The management considered the drop to be gentle and normal in nature," the filing stated. Because promotions brought in smaller basket sizes, the fitness retailer had to ship 852 additional orders just to add $83,558 in top-line sales.
What to watch: full-year merchandise order counts and average revenue per order in the fiscal 2026 annual report. A further slide in order value would show that customer acquisition depends on discounting.
🟢 𝐔𝐧𝐝𝐞𝐫𝐥𝐲𝐢𝐧𝐠 𝐆𝐫𝐨𝐬𝐬 𝐌𝐚𝐫𝐠𝐢𝐧 𝐇𝐞𝐥𝐝 𝐒𝐭𝐞𝐚𝐝𝐲 𝐁𝐞𝐟𝐨𝐫𝐞 𝐖𝐫𝐢𝐭𝐞-𝐃𝐨𝐰𝐧
On the restated income statement, cost of goods sold—the price of buying and shipping fitness gear—rose 17.0% from a year ago to $1.91 million. That jump compressed reported gross margin by 8.2 percentage points to 30.1% of revenue. In its commentary, GMEX Robotics noted that the decrease resulted from a "one-off stock allowance expense related to some slow-moving consignment stock".
In the original April filing, the Australian retailer had placed this $227,087 consignment reserve inside general and administrative expenses, before moving it into cost of goods sold in the amended report. Excluding that single inventory charge, underlying gross profit was $1.05 million, or 38.4% of revenue by our math, matching the 38.3% gross margin earned a year earlier despite lower average order prices.
What to watch: gross margin and inventory reserve disclosures in the second half of fiscal 2026. Another consignment write-down would show that slow-moving stock is a recurring merchandise cost rather than a one-off charge.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐀𝐝𝐯𝐢𝐬𝐨𝐫𝐲 𝐅𝐞𝐞𝐬 𝐄𝐱𝐜𝐞𝐞𝐝𝐞𝐝 𝐓𝐨𝐭𝐚𝐥 𝐂𝐨𝐦𝐩𝐚𝐧𝐲 𝐑𝐞𝐯𝐞𝐧𝐮𝐞
"Gross profit margin was 30.1% and 38.3% for the six-month periods ended December 31, 2025 and 2024, respectively, which was very stable," the company wrote, describing its cost structure as steady. Yet total operating expenses more than doubled from a year ago to $4.89 million, or 179.0% of revenue, widening the operating loss from $1.17 million to $4.07 million.
• Consulting fees: $2.93 million, up 85.8 percentage points to 107.5% of revenue
• General and administrative expenses (overhead and legal): $887,177, up 6.8 percentage points to 32.5% of revenue
• Personnel expenses (staff pay and benefits): $670,783, up 2.7 percentage points to 24.6% of revenue
• Normalized net loss (excluding one-offs): $3.79 million, up 125.6% from $1.68 million a year ago
The company spent money on advisors for "issues related to capital raises, business direction and strategy options, including crypto currencies investments, and domicile change". Even after stripping out $1.69 million in one-off digital asset consulting and legal fees, remaining consulting expenses equaled 58.3% of revenue by our math, and the board warned that "there remains material uncertainty as to whether the Company will continue as a going concern".
What to watch: consulting fees and operating cash burn in the fiscal 2026 annual report. A second half with consulting costs above gross profit would drain unrestricted cash and require new financing.
🔴🔴 𝐒𝐨𝐥𝐚𝐧𝐚 𝐋𝐨𝐬𝐬𝐞𝐬 𝐂𝐮𝐭 𝐢𝐧𝐭𝐨 𝐍𝐞𝐰 𝐂𝐫𝐲𝐩𝐭𝐨 𝐓𝐫𝐞𝐚𝐬𝐮𝐫𝐲
Starting in September 2025, the fitness retailer began buying cryptocurrencies and stablecoins—digital tokens pegged to the US dollar—for "diversification of corporate treasury strategies and maximize returns on cash balances". During the half year, the group spent $58.49 million in cash to purchase digital assets and sold $3.16 million, leaving a net cost basis of $55.33 million.
• Solana cryptocurrency: cost basis of $8.49 million, carrying value of $399,654 (an unrealized loss of $8.09 million, or 95.3% by our math)
• Pump cryptocurrency: cost basis of $1.51 million, carrying value of $3.44 million (an unrealized gain of $1.92 million)
• Frax USD stablecoins: cost basis of $45.33 million, carrying value of $46.84 million (an unrealized gain of $1.51 million)
In total, GMEX Robotics booked a $4.65 million unrealized loss on digital assets, equal to 170.5% of its six-month merchandise revenue. Furthermore, the company holds $49.15 million of its $50.67 million digital asset balance inside BitGo wallets jointly controlled with lenders as collateral for convertible debt, leaving only $1.52 million of stablecoins under its sole control.
What to watch: the carrying value of the Solana and Pump tokens and any collateral liquidations in the next filing. Further crypto price drops would shrink the collateral backing the company's debt.
🔴🔴 𝐍𝐨𝐭𝐞 𝐂𝐨𝐧𝐯𝐞𝐫𝐬𝐢𝐨𝐧𝐬 𝐌𝐮𝐥𝐭𝐢𝐩𝐥𝐢𝐞𝐝 𝐒𝐡𝐚𝐫𝐞 𝐂𝐨𝐮𝐧𝐭 𝐅𝐢𝐯𝐞𝐟𝐨𝐥𝐝
To fund its digital asset purchases, GMEX Robotics issued $65.0 million in face value of Series A and Series C convertible notes—debt that lenders can exchange for stock—between September and November 2025, raising $63.70 million in cash. The notes allow lenders to convert debt into Class A shares at 95% of the lowest daily volume-weighted average stock price over the preceding ten trading days.
During the six-month period, note holder ATW converted $12.05 million of principal and $54,325 of interest into 1,110,713 Class A shares. Along with shares issued for cash and services, total shares outstanding jumped 407.3% by our math in six months, rising from 315,161 to 1,598,801 after adjusting for two reverse stock splits (1-for-16 in September 2025 and 1-for-8 in January 2026).
The company still carries $44.74 million of convertible notes at fair value on its balance sheet, and it sold another $250,000 of Series D convertible notes in March 2026 at a $3.00 initial conversion price. In December 2025, the board also declared a cash dividend totaling $1.04 million, committing cash while operations burned $4.42 million.
What to watch: remaining convertible note principal and Class A share count in the fiscal 2026 annual report. Continued conversions at a discount to market prices will dilute existing shareholders further.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐑𝐞𝐬𝐭𝐚𝐭𝐞𝐦𝐞𝐧𝐭 𝐚𝐧𝐝 𝐑𝐨𝐛𝐨𝐭𝐢𝐜𝐬 𝐑𝐞𝐛𝐫𝐚𝐧𝐝 𝐂𝐡𝐚𝐧𝐠𝐞𝐝 𝐭𝐡𝐞 𝐂𝐨𝐫𝐩𝐨𝐫𝐚𝐭𝐞 𝐒𝐞𝐭𝐮𝐩
In November 2026, chief executive Yinying Lu signed an amended half-year report to restate the unaudited results originally published in April 2026. The company elected fair value accounting for its convertible notes, recording a $3.09 million valuation gain and reducing six-month net loss from $9.87 million to $7.05 million. In March 2026, it moved its legal domicile to the British Virgin Islands and rebranded to GMEX Robotics, "extending its consumer-first foundation beyond fitness equipment e-commerce into the design and deployment of AI-powered robotics and intelligent consumer technologies".
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐂𝐚𝐬𝐡 𝐚𝐧𝐝 𝐮𝐧𝐫𝐞𝐬𝐭𝐫𝐢𝐜𝐭𝐞𝐝 𝐬𝐭𝐚𝐛𝐥𝐞𝐜𝐨𝐢𝐧𝐬 (𝟐𝟔𝐐𝟐): $𝟏𝟎.𝟑𝟐 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Unrestricted cash rose from $2.89 million in June 2025 to $8.80 million in December 2025, and GMEX Robotics also holds $1.52 million in unrestricted stablecoins. The cash build came from $65.68 million of debt and equity financing, as operations burned $4.42 million in cash during the six-month period.
𝐈𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 𝐚𝐧𝐝 𝐝𝐞𝐟𝐞𝐫𝐫𝐞𝐝 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 (𝟐𝟔𝐐𝟐): $𝟐.𝟖𝟒 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐢𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 ⇘ decelerating
Finished goods inventory fell 6.8% from June 2025 to $2.84 million as the Australian subsidiary shipped more orders before year-end and wrote down $227,087 of consignment stock. Deferred revenue—customer deposits for equipment not yet delivered—decreased 5.1% over the same six months to $318,700.
𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐬 𝐚𝐧𝐝 𝐥𝐨𝐚𝐧 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞𝐬 (𝟐𝟔𝐐𝟐): $𝟐.𝟖𝟒 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐜𝐨𝐦𝐛𝐢𝐧𝐞𝐝 ⇗ accelerating
Accounts receivable climbed 39.6% from June 2025 to $338,023, while a $2.50 million loan to an independent borrower remained on the books. Unpaid interest on that loan grew from $212,500 to $297,500, accounting for 88% of accounts receivable by our math, and the firm booked a $100,000 impairment on other receivables.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐲 𝐝𝐢𝐝 𝐒𝐨𝐥𝐚𝐧𝐚 𝐥𝐨𝐬𝐞 𝟗𝟓% 𝐨𝐟 𝐢𝐭𝐬 𝐜𝐨𝐬𝐭 𝐛𝐚𝐬𝐢𝐬?
Note 5 shows 27,516 Solana tokens bought for $8.49 million (about $308 each by our math) but valued at $399,654 despite a listed market price of $124.89. Management should explain whether tokens were lost, locked, or miscalculated in the table.
𝐖𝐡𝐚𝐭 𝐜𝐨𝐦𝐦𝐞𝐫𝐜𝐢𝐚𝐥 𝐩𝐫𝐨𝐝𝐮𝐜𝐭𝐬 𝐞𝐱𝐢𝐬𝐭 𝐟𝐨𝐫 𝐭𝐡𝐞 𝐫𝐨𝐛𝐨𝐭𝐢𝐜𝐬 𝐫𝐞𝐛𝐫𝐚𝐧𝐝?
The company renamed itself GMEX Robotics in March 2026 to design AI-powered robotics, yet it spent nothing on research and development and holds only $17,846 in physical equipment (a single motor vehicle). Investors need to know how robotics will be funded and built.
𝐖𝐢𝐥𝐥 𝐭𝐡𝐞 $𝟐.𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐭𝐡𝐢𝐫𝐝-𝐩𝐚𝐫𝐭𝐲 𝐥𝐨𝐚𝐧 𝐛𝐞 𝐫𝐞𝐩𝐚𝐢𝐝?
The August 2023 loan of $2.50 million matured in August 2026, and accrued unpaid interest reached $297,500 by December 2025. Since the amended report was filed in November 2026 without mentioning repayment in subsequent events, management should confirm if the borrower defaulted.
𝐖𝐡𝐨 𝐫𝐞𝐜𝐞𝐢𝐯𝐞𝐝 𝐭𝐡𝐞 $𝟐.𝟗𝟑 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐢𝐧 𝐜𝐨𝐧𝐬𝐮𝐥𝐭𝐢𝐧𝐠 𝐟𝐞𝐞𝐬?
Six-month consulting payments exceeded total merchandise revenue, and the company prepaid another $730,143 in upfront consulting deposits. Management should disclose the recipients and clarify whether any fees remain payable in the second half.

$CRC Q3 2026 earnings: California Resources beats cash profit plan, but oil discounts widen
California Resources Corporation, the California oil, gas and carbon storage producer, beat its third-quarter cash profit plan on summer electricity sales while its core oil business faced wider price discounts and higher field costs. Cash profit reached $341 million as the Elk Hills power plant earned $35 million, offsetting a $315 million net loss caused by non-cash oil hedge charges. Chief executive Francisco Leon closed the Crimson pipeline purchase, agreed to sell the Utah oil fields for $90 million, and resumed share buybacks.
• Cash profit (Adjusted EBITDAX): $𝟑𝟒𝟏𝐌 (beat $285–325M plan; +1% from a year ago)
• Oil price before hedges (% of Brent): 𝟗𝟏% (95% last quarter; 97% a year ago)
• Free cash flow: $𝟏𝟒𝟕𝐌 (+29% from last quarter; -22% from a year ago)
• Q4 cash profit outlook: $𝟑𝟒𝟎–𝟑𝟖𝟎𝐌 (assumes $102.90/Bbl Brent oil)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because seasonal power profits and a $103 oil price assumption in the fourth-quarter plan mask persistent weakness in the oil fields. While resuming buybacks at $30 million and exiting Utah clean up capital allocation, the price the company receives for its oil before hedges fell to 91% of Brent, and the fourth-quarter plan keeps it at 91–93% despite owning the new pipelines. Well operating costs also missed the company's plan on higher steamflood fuel and maintenance bills.
The question now is whether the 91–93% oil price realization is a temporary pipeline dispute or a lasting discount from California refinery closures. If the Crimson pipelines fix the bottleneck, realizations should recover toward 96% of Brent and add roughly $40 million a quarter in cash profit; if refinery demand has permanently shifted to waterborne imports, the discount will stick. The full-year 2027 outlook next quarter will show which side is right.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢 𝐏𝐨𝐰𝐞𝐫 𝐏𝐥𝐚𝐧𝐭 𝐏𝐫𝐨𝐟𝐢𝐭 𝐚𝐧𝐝 𝐎𝐢𝐥 𝐏𝐫𝐢𝐜𝐞𝐬 𝐋𝐢𝐟𝐭𝐞𝐝 𝐂𝐚𝐬𝐡 𝐏𝐫𝐨𝐟𝐢𝐭
California Resources Corporation (CRC), an oil, gas and carbon management producer in California, tracks Adjusted EBITDAX — cash profit before interest, taxes, depreciation, exploration and one-offs. After missing its target last quarter, the company beat the top of its $285–325 million third-quarter plan by $16 million.
• Third-quarter Adjusted EBITDAX: $341 million, up 1% from last quarter and 1% from a year ago
• Electricity revenue minus generation costs: $35 million, compared with a $18–24 million plan and a $4 million loss last quarter
• Fourth-quarter Adjusted EBITDAX outlook: $340–380 million, based on $102.90 per barrel Brent oil
The third-quarter beat came from its Elk Hills power plant and higher Brent crude prices ($91.36 per barrel versus the $83.14 plan). Electricity profit beat the plan "primarily due to higher prices for resource adequacy revenue and sales from electricity delivered to the wholesale market", the company said. The fourth-quarter plan rises again because management assumes $102.90 Brent oil, even as power profit drops back to $5–11 million.
What to watch: fourth-quarter cash profit against actual Brent oil prices. If oil averages below $102.90 per barrel, cash profit will trail the $340–380 million outlook.
🟢 𝐏𝐨𝐫𝐭𝐟𝐨𝐥𝐢𝐨 𝐌𝐨𝐯𝐞𝐬 𝐂𝐞𝐧𝐭𝐞𝐫 𝐭𝐡𝐞 𝐁𝐮𝐬𝐢𝐧𝐞𝐬𝐬 𝐨𝐧 𝐂𝐚𝐥𝐢𝐟𝐨𝐫𝐧𝐢𝐚
"As we look to 2027, CRC is moving from acquisition to optimization," chief executive Francisco Leon said. He wants the oil producer to focus on "lowering costs, improving capital efficiency and putting our midstream, power and carbon opportunities to work".
The company closed its purchase of Crimson Midstream, a California pipeline operator, and agreed to sell its Uinta Basin oil fields in Utah for about $90 million in cash. Those fields produced 2 thousand barrels of oil per day and 9 million cubic feet of gas per day this quarter. Selling Utah cleans up a reversal from earlier this year, when management briefly planned to add a Utah drilling rig before calling the asset non-core.
Meanwhile, general and administrative overhead excluding one-offs fell to $79 million from $89 million last quarter as savings from the December 2025 Berry merger took hold. Management also kept its 2027 drilling, completion and well-maintenance capital plan at $450–475 million across six California rigs, matching the 5% lower budget it set three months ago.
What to watch: the full-year 2027 outlook arriving with fourth-quarter results. It will show whether the Crimson pipelines and Berry cost savings lower per-barrel operating expenses.
🟢 𝐁𝐮𝐲𝐛𝐚𝐜𝐤𝐬 𝐑𝐞𝐬𝐮𝐦𝐞𝐝 𝐀𝐥𝐨𝐧𝐠𝐬𝐢𝐝𝐞 𝐚 𝟒% 𝐃𝐢𝐯𝐢𝐝𝐞𝐧𝐝 𝐈𝐧𝐜𝐫𝐞𝐚𝐬𝐞
Share buybacks had nearly stopped this year, falling from $353 million in the first half of 2025 to $10 million in the first quarter of 2026 and zero in the second. Management blamed the second-quarter pause on legal trading restrictions while it negotiated the Crimson pipeline deal and refinanced debt.
With the Crimson deal signed, the producer bought back 0.6 million shares for $30 million at an average price of $53.48. The board also raised the quarterly cash dividend by 4% to $0.42 per share, after paying $36 million in dividends during the third quarter. Total cash returned to shareholders reached $66 million, or 45% of the quarter's $147 million in free cash flow.
What to watch: fourth-quarter share repurchases after the $90 million Utah sale closes by year-end. A larger buyback would show that deal restrictions, rather than tight cash, caused the first-half pause.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐎𝐢𝐥 𝐏𝐫𝐢𝐜𝐞 𝐃𝐢𝐬𝐜𝐨𝐮𝐧𝐭𝐬 𝐖𝐨𝐫𝐬𝐞𝐧𝐞𝐝 𝐚𝐧𝐝 𝐅𝐢𝐞𝐥𝐝 𝐂𝐨𝐬𝐭𝐬 𝐑𝐨𝐬𝐞
Leon praised the company's "ongoing focus on sustainable efficiency gains", and management previously called second-quarter pipeline bottlenecks a temporary issue. Yet the price CRC received for its oil before hedges fell further behind the Brent benchmark, and field operating costs missed the company's own plan.
• Oil price before hedges: 91% of Brent ($83.42 per barrel), down from 95% in Q2 and 97% a year ago
• Fourth-quarter oil realization outlook: 91–93% of Brent, showing no recovery by year-end
• Operating costs: $386 million (35.2% of revenue before derivatives, up 3.4 percentage points from Q2), worse than the $360–380 million plan
Operating costs — the direct expense of running oil and gas wells — rose "primarily due to higher prices for natural gas purchased and used in steamflood operations, and higher workover activity", the company said. Steamflooding burns natural gas to heat heavy underground oil so it flows. At the same time, receiving 91% of Brent instead of 95% costs about $40 million a quarter on 121 thousand barrels a day. Management's fourth-quarter plan keeps operating costs high at $370–390 million and oil prices at 91–93% of Brent.
What to watch: first-quarter 2027 oil price realizations after a full quarter of owning the Crimson pipelines. If realizations stay near 91–93% of Brent, the discount is a lasting California market shift rather than a temporary dispute.
🔴 𝐎𝐢𝐥 𝐇𝐞𝐝𝐠𝐞𝐬 𝐊𝐞𝐩𝐭 𝐂𝐚𝐩𝐩𝐢𝐧𝐠 𝐂𝐚𝐬𝐡 𝐏𝐫𝐢𝐜𝐞𝐬 𝐚𝐭 𝟕𝟗% 𝐨𝐟 𝐁𝐫𝐞𝐧𝐭
CRC uses commodity derivatives — financial price hedges — to lock in oil prices, which protects cash flow when crude falls but caps revenue when crude rises. Because Brent crude averaged $91.36 per barrel in the third quarter, those contracts cost the company $121 million in cash oil settlements.
After those hedge payments, the producer kept $72.46 per barrel of oil, or 79% of Brent, matching the 79% share it kept in the second quarter and down from 98% a year ago. Rising oil prices also reduced the accounting value of future hedge contracts, creating a $540 million non-cash charge that pushed the company to a $315 million net loss. If Brent reaches management's $102.90 fourth-quarter assumption, hedge payments will take an even larger cut of oil revenue.
What to watch: cash derivative settlements in the fourth-quarter report. They will show how much of the rally above $90 Brent actually reaches the company's bank account.
🔴 𝐂𝐚𝐫𝐛𝐨𝐧 𝐚𝐧𝐝 𝐏𝐨𝐰𝐞𝐫 𝐃𝐞𝐚𝐥𝐬 𝐑𝐞𝐦𝐚𝐢𝐧 𝐍𝐨𝐧-𝐁𝐢𝐧𝐝𝐢𝐧𝐠 𝐰𝐡𝐢𝐥𝐞 𝐋𝐨𝐬𝐬𝐞𝐬 𝐂𝐨𝐧𝐭𝐢𝐧𝐮𝐞
Through its Carbon TerraVault unit, the company wants to turn depleted underground oil fields into paid storage sites for carbon dioxide and pair them with low-carbon power plants. This quarter it signed a memorandum of understanding with Bloom Energy to evaluate "the potential development of 1 gigawatt (GW) or more of solid-oxide fuel cell power generation paired with carbon capture and storage".
As the release notes, such agreements are non-binding and require binding customer contracts, investment decisions and federal permits. After nearly two years of similar announcements, the company still has no binding power-purchase deal with a data center and no major third-party carbon revenue. The carbon segment lost $8 million in Adjusted EBITDAX, matching its first- and second-quarter losses, and management cut segment capital spending to $1 million (with $0–2 million planned for the fourth quarter). Meanwhile, legacy offshore platform costs took another $6 million ($26 million over nine months), and the release gave no update on state carbon-program rules or permits.
What to watch: segment revenue in the full-year filing and any binding customer contract. Until a paying customer signs a binding deal, the carbon and power business remains a cash drain.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐍𝐞𝐭 𝐩𝐫𝐨𝐝𝐮𝐜𝐭𝐢𝐨𝐧 (𝟐𝟔𝐐𝟑): 𝟏𝟓𝟐 𝐌𝐁𝐨𝐞/𝐝 ⇗ accelerating
Total output in thousand barrels of oil equivalent per day rose 2.0% from last quarter and 11.0% from a year ago, landing inside the 151–154 outlook. By our math, excluding the roughly 22 MBoe/d added by the December 2025 Berry merger, output from wells owned a year ago fell about 5%. New gas processing connections lifted natural gas volumes 7.0% from last quarter.
𝐅𝐫𝐞𝐞 𝐜𝐚𝐬𝐡 𝐟𝐥𝐨𝐰 (𝟐𝟔𝐐𝟑): $𝟏𝟒𝟕 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇄ reversing
Cash left after capital investments rose 28.9% from $114 million last quarter (and a $32 million outflow in the first quarter), but fell 21.8% from $188 million a year ago. Operating cash flow rose to $305 million as the company sold oil inventory built up in the second quarter, while capital spending rose to $158 million.
𝐍𝐞𝐭 𝐝𝐞𝐛𝐭 (𝟐𝟔𝐐𝟑): $𝟏,𝟐𝟒𝟔 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
By our math, carrying debt of $1,281 million minus $35 million of available cash edged down from $1,238 million at the end of June as cash dipped by $8 million to help close the Crimson pipeline deal. Total current liabilities on the balance sheet rose 54.5% since December to $1,622 million because higher oil prices increased hedge liabilities.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐐𝟒 𝐍𝐞𝐭 𝐏𝐫𝐨𝐝𝐮𝐜𝐭𝐢𝐨𝐧: 𝟏𝟓𝟎–𝟏𝟓𝟐 𝐌𝐁𝐨𝐞/𝐝 (𝟕𝟗% 𝐨𝐢𝐥) ⇘ decelerating
New. The plan calls for 151 MBoe/d at the middle of the range, down 0.7% from the third quarter and up 10.2% from a year ago. The forecast still includes the Utah fields (about 3.5 MBoe/d) until the sale closes at year-end, while oil drops by 1 percentage point to 79% of total output.
𝐐𝟒 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀𝐗: $𝟑𝟒𝟎–𝟑𝟖𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
New. The middle of the range ($360 million) is up 5.6% from the third quarter and up 43.4% from a year ago. By our math, adding this to nine-month results puts the full year at $1,323–1,363 million, above the $1,200–1,300 million full-year target set last quarter, because management raised its Brent oil assumption from $84.51 to $102.90 per barrel.
𝐐𝟒 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐈𝐧𝐯𝐞𝐬𝐭𝐦𝐞𝐧𝐭𝐬: $𝟏𝟏𝟎–𝟏𝟑𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠆 unchanged from $70–130 million (implied by prior FY26 outlook)
Unchanged against the upper half of what the prior full-year plan left for the fourth quarter. At the $120 million middle of the range, spending drops 24.1% from the third quarter and is flat against a year ago as the company runs five drilling rigs before adding a sixth rig in early 2027.
𝐐𝟒 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐂𝐨𝐬𝐭𝐬: $𝟑𝟕𝟎–𝟑𝟗𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇒ stable
New. The $380 million middle of the range is down 1.6% from the third quarter's $386 million actual result, but $10 million higher than the range management had planned for the third quarter, showing that higher well-maintenance and steamflood fuel costs are sticking around.
𝐐𝟒 𝐆𝐞𝐧𝐞𝐫𝐚𝐥 𝐚𝐧𝐝 𝐀𝐝𝐦𝐢𝐧𝐢𝐬𝐭𝐫𝐚𝐭𝐢𝐯𝐞 𝐄𝐱𝐩𝐞𝐧𝐬𝐞𝐬: $𝟗𝟓–𝟗𝟗 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ($𝟖𝟑–𝟗𝟑 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬) ⇗ accelerating
New. At the middle of the range, overhead rises to $97 million ($88 million excluding stock compensation), up 11.4% from $79 million excluding one-offs in the third quarter.
𝐐𝟒 𝐃𝐃&𝐀, 𝐓𝐚𝐱𝐞𝐬 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐚𝐧 𝐈𝐧𝐜𝐨𝐦𝐞, 𝐚𝐧𝐝 𝐈𝐧𝐭𝐞𝐫𝐞𝐬𝐭: 𝐃𝐃&𝐀 $𝟏𝟐𝟖–𝟏𝟒𝟎𝐌 | 𝐎𝐭𝐡𝐞𝐫 𝐓𝐚𝐱𝐞𝐬 $𝟔𝟖–𝟕𝟖𝐌 | 𝐈𝐧𝐭𝐞𝐫𝐞𝐬𝐭 $𝟐𝟖–𝟑𝟐𝐌 ⇒ stable
New. Depreciation, depletion and amortization averages $134 million (down from $137 million in Q3), production and property taxes average $73 million (down from $81 million), and net interest expense averages $30 million (up from $26 million).
𝐐𝟒 𝐄𝐥𝐞𝐜𝐭𝐫𝐢𝐜𝐢𝐭𝐲, 𝐏𝐮𝐫𝐜𝐡𝐚𝐬𝐞𝐝 𝐂𝐨𝐦𝐦𝐨𝐝𝐢𝐭𝐢𝐞𝐬, 𝐓𝐫𝐚𝐧𝐬𝐩𝐨𝐫𝐭, 𝐚𝐧𝐝 𝐎𝐭𝐡𝐞𝐫 𝐍𝐞𝐭 𝐄𝐱𝐩𝐞𝐧𝐬𝐞: 𝐄𝐥𝐞𝐜𝐭𝐫𝐢𝐜𝐢𝐭𝐲 𝐍𝐞𝐭 $𝟓–𝟏𝟏𝐌 | 𝐌𝐚𝐫𝐤𝐞𝐭𝐢𝐧𝐠 $𝟏𝟏–𝟏𝟓𝐌 | 𝐓𝐫𝐚𝐧𝐬𝐩𝐨𝐫𝐭 $𝟑𝟎–𝟑𝟓𝐌 | 𝐎𝐭𝐡𝐞𝐫 𝐍𝐞𝐭 𝐄𝐱𝐩𝐞𝐧𝐬𝐞 $𝟐𝟎–𝟑𝟎𝐌 ⇘ decelerating
New. Net electricity profit drops from $35 million in the third quarter to $8 million at the middle of the range as summer power demand ends. Marketing profit ($13 million midpoint), transport costs ($32.5 million) and other net operating expenses ($25 million) stay near third-quarter levels.
𝐐𝟒 𝐏𝐫𝐢𝐜𝐞 𝐑𝐞𝐚𝐥𝐢𝐳𝐚𝐭𝐢𝐨𝐧𝐬 (% 𝐨𝐟 𝐁𝐞𝐧𝐜𝐡𝐦𝐚𝐫𝐤): 𝐎𝐢𝐥 𝟗𝟏–𝟗𝟑% 𝐨𝐟 𝐁𝐫𝐞𝐧𝐭 | 𝐍𝐆𝐋 𝟓𝟓–𝟔𝟐% 𝐨𝐟 𝐁𝐫𝐞𝐧𝐭 | 𝐆𝐚𝐬 𝟏𝟏𝟎–𝟏𝟏𝟔% 𝐨𝐟 𝐍𝐘𝐌𝐄𝐗 ⇒ stable
🠇 cut from Oil 92–94% of Brent (implied by prior FY26 outlook)
Cut on oil. The 92% middle of the range for oil sits 1 percentage point below what management's prior 94% full-year target implied for the fourth quarter, keeping oil discounts near the third quarter's 91% level. Natural gas realizations remain high at 113% of NYMEX after winter pricing begins.
𝟐𝟎𝟐𝟕 𝐃𝐫𝐢𝐥𝐥𝐢𝐧𝐠, 𝐂𝐨𝐦𝐩𝐥𝐞𝐭𝐢𝐨𝐧𝐬 𝐚𝐧𝐝 𝐖𝐨𝐫𝐤𝐨𝐯𝐞𝐫 𝐂𝐚𝐩𝐢𝐭𝐚𝐥: $𝟒𝟓𝟎–𝟒𝟕𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠆 unchanged from $450–475 million
Unchanged. Management kept its preliminary 2027 well-spending plan at $450–475 million across six California rigs, up from the $370–390 million planned for 2026, and will issue a complete 2027 plan next quarter.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐲 𝐝𝐢𝐝 𝐨𝐢𝐥 𝐩𝐫𝐢𝐜𝐞 𝐝𝐢𝐬𝐜𝐨𝐮𝐧𝐭𝐬 𝐰𝐢𝐝𝐞𝐧 𝐭𝐨 𝟗𝟏% 𝐨𝐟 𝐁𝐫𝐞𝐧𝐭?
Management said in Q2 that pipeline disputes were temporary and predicted 93% of Brent in Q3 and a Q4 recovery. Instead, Q3 fell to 91% and Q4 is planned at 91–93% even after closing the Crimson pipeline purchase.
𝐖𝐡𝐲 𝐝𝐨𝐞𝐬 𝐐𝟒 𝐚𝐬𝐬𝐮𝐦𝐞 $𝟏𝟎𝟐.𝟗𝟎 𝐁𝐫𝐞𝐧𝐭 𝐨𝐢𝐥, 𝐚𝐧𝐝 𝐰𝐡𝐚𝐭 𝐢𝐬 𝐡𝐞𝐝𝐠𝐞𝐝?
The $340–380 million Q4 cash profit plan rests on $102.90 per barrel Brent, up $11.54 from Q3 actuals. Investors need to know how much of that increase is lost to oil price hedges capped near $68–84 per barrel.
𝐖𝐡𝐚𝐭 𝐞𝐚𝐫𝐧𝐢𝐧𝐠𝐬 𝐰𝐢𝐥𝐥 𝐭𝐡𝐞 𝐂𝐫𝐢𝐦𝐬𝐨𝐧 𝐩𝐢𝐩𝐞𝐥𝐢𝐧𝐞𝐬 𝐚𝐝𝐝 𝐢𝐧 𝟐𝟎𝟐𝟕?
The company closed the Crimson Midstream purchase and sold the Utah fields for $90 million, but did not update its full-year 2026 table or disclose how much pipeline tariff profit Crimson adds and how much cash profit the Utah sale removes.
𝐖𝐡𝐞𝐧 𝐰𝐢𝐥𝐥 𝐚 𝐝𝐚𝐭𝐚 𝐜𝐞𝐧𝐭𝐞𝐫 𝐨𝐫 𝐜𝐚𝐫𝐛𝐨𝐧 𝐜𝐮𝐬𝐭𝐨𝐦𝐞𝐫 𝐬𝐢𝐠𝐧 𝐚 𝐛𝐢𝐧𝐝𝐢𝐧𝐠 𝐜𝐨𝐧𝐭𝐫𝐚𝐜𝐭?
The Bloom Energy fuel-cell agreement is another non-binding memorandum of understanding, while the carbon unit lost $8 million and spent just $1 million in capital. Investors need a date for first binding third-party revenue.

$ALG Q3 2026 earnings: Alamo Group orders rebound, but underlying industrial sales drop 13%
Alamo Group, the maker of municipal street sweepers and agricultural mowers, saw underlying sales drop while it cleaned up its weaker brands. Reported revenue fell 4% to $403 million — or about 6% by our math excluding the Petersen acquisition and brand exit charges — and profit per share excluding one-offs fell 12%. Chief executive Robert Hureau completed the exit of underperforming mower lines, taking $33 million in charges, and spent $159 million after quarter-end to buy UK truck maker Econ Engineering.
• Underlying revenue (ex Petersen & exits): -𝟔% (from a year ago by our math (-4.0% reported to $403.1M))
• Profit per share, excluding one-offs: $𝟐.𝟎𝟔 (-12% from a year ago ($0.17 reported after exit charges))
• Total order bookings: $𝟑𝟕𝟓.𝟏𝐌 (+6.8% from a year ago by our math (backlog -15.7%))
• Near-term outlook: 𝐍𝐨𝐧𝐞 𝐠𝐢𝐯𝐞𝐧 (no numerical outlook in release; $158.7M Econ deal closed Oct 27)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because progress on self-help and acquisitions was offset by a sharp drop in underlying Industrial shipments. On the bright side, Vegetation margins excluding one-offs reached 12.5%, overall gross margin rose for the first time in six quarters, and Industrial bookings jumped 24% by our math. The bad news: Industrial sales from businesses owned a year ago fell 13% as material and freight inflation squeezed its margin, while Vegetation orders dropped 11%.
The question now is whether the 24% rebound in Industrial bookings is genuine municipal demand or mostly the addition of Petersen. If underlying orders are growing and recent price increases stick, the Industrial slowdown will be brief; if Petersen drove the order gain, underlying revenue will keep shrinking. The organic order split in the third-quarter filing and fourth-quarter Industrial margins will tell.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢 𝐈𝐧𝐝𝐮𝐬𝐭𝐫𝐢𝐚𝐥 𝐎𝐫𝐝𝐞𝐫𝐬 𝐑𝐞𝐛𝐨𝐮𝐧𝐝𝐞𝐝 𝐨𝐧 𝐕𝐚𝐜𝐮𝐮𝐦 𝐓𝐫𝐮𝐜𝐤𝐬
Alamo Group makes heavy equipment in two divisions: Industrial Equipment, which sells vacuum trucks, street sweepers and snow ploughs to governments and contractors, and Vegetation Management, which sells mowers and tree-care machines. Investors worried that Industrial customer orders were drying up after the division's order backlog — signed orders waiting to be built — fell 28% from a year ago last quarter.
Order intake strengthened in the third quarter, chief executive Robert Hureau said, with "particularly encouraging activity in vacuum trucks and sweepers". By our math, Industrial net bookings rose 24.2% from a year ago to $217.9 million. Because the division shipped $232.8 million of equipment, its backlog still dipped by $14.9 million from June to $350.4 million, down 20.0% from a year ago.
The jump in bookings matters because it lifted the ratio of new orders to shipments from 0.85 in the second quarter to 0.94, by our math. However, the press release does not split out how much of that 24.2% order growth came from Petersen Industries, the bulky-waste grapple maker bought in January.
What to watch: the underlying Industrial order growth rate excluding Petersen in the third-quarter filing. A positive underlying order number would show that municipal demand has stabilised before the backlog runs down further.
🟢 𝐕𝐞𝐠𝐞𝐭𝐚𝐭𝐢𝐨𝐧 𝐌𝐚𝐫𝐠𝐢𝐧 𝐑𝐨𝐬𝐞 𝐚𝐧𝐝 𝐆𝐫𝐨𝐬𝐬 𝐌𝐚𝐫𝐠𝐢𝐧 𝐈𝐦𝐩𝐫𝐨𝐯𝐞𝐝
Over the past year Alamo Group consolidated factories in its Vegetation Management division, which caused production delays earlier in 2025. Hureau said he is pleased with the division's progress toward "restoring the Division’s operating margins to healthy levels". Excluding $7.3 million of divestiture charges, Vegetation sales from businesses owned a year ago rose 2.7%, as factories shipped orders faster.
That better factory output lifted Vegetation's EBITDA margin, excluding one-offs, by 2.8 percentage points from a year ago to 12.5%. Across the whole company, gross margin excluding one-offs — profit after the cost of making the products — rose 0.4 percentage points to 24.7%. That gain ended five straight quarters of year-on-year gross margin declines, even though selling and administrative overhead rose 0.4 percentage points to 13.9% of sales.
What to watch: fourth-quarter Vegetation EBITDA margin excluding one-offs against last year's depressed 2.3% level. Holding near 12% in the seasonally slow fourth quarter would confirm that the factory fixes and brand exits permanently lowered fixed costs.
🟢 𝐄𝐜𝐨𝐧 𝐃𝐞𝐚𝐥 𝐏𝐮𝐭𝐬 𝐈𝐝𝐥𝐞 𝐂𝐚𝐬𝐡 𝐭𝐨 𝐖𝐨𝐫𝐤
Because organic demand has slowed, Alamo Group relies on acquisitions to reach its long-term target of 8% to 10% annual sales growth. After buying Petersen in January, the company went two quarters without a deal and ended September with $230.7 million in cash against $232.3 million of debt, leaving net debt at just $1.7 million.
On October 27, the equipment maker bought Econ Engineering Group, "a leading U. K. manufacturer of roadway maintenance vocational trucks", for £120.0 million ($158.7 million) using its credit line. By our math, the purchase lifts net debt to about $160 million, still well below management's ceiling of 2.5 times annual EBITDA.
What to watch: Econ's annual revenue and profit margin on the conference call. Those numbers will show the price multiple paid and how much Econ adds to 2027 Industrial growth.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐈𝐧𝐝𝐮𝐬𝐭𝐫𝐢𝐚𝐥 𝐒𝐚𝐥𝐞𝐬 𝐃𝐫𝐨𝐩𝐩𝐞𝐝 𝟏𝟑% 𝐚𝐬 𝐂𝐨𝐬𝐭𝐬 𝐑𝐨𝐬𝐞
Industrial Equipment brings in nearly three-fifths of Alamo Group's revenue and carried the company through the agricultural downturn. As its order backlog shrank over the past year, the risk was that lower backlog coverage would turn into falling shipments against last year's 14.5% underlying sales growth.
"Our Industrial Equipment Division experienced margin pressure during the quarter from elevated material and freight costs," Hureau said. He added that the division raised prices, but "the timing of those actions lagged inflation during the quarter". Meanwhile, softer end markets and earlier order timing hit shipments.
• Industrial reported sales: $232.8 million, down 5.8% from a year ago
• Industrial sales excluding Petersen: down 12.6% from a year ago (with Petersen adding about $16.9 million by our math)
• Industrial EBITDA margin, excluding one-offs: 13.4%, down 2.1 percentage points from 15.5% a year ago
• Industrial operating margin, excluding one-offs: 10.4%, down 2.5 percentage points from 12.9% a year ago
A 12.6% drop in underlying sales is too large to blame on a tough comparison alone. Because factories had fewer trucks to build, fixed overhead took a larger share of revenue at the exact time materials and shipping got more expensive.
What to watch: Industrial EBITDA margin excluding one-offs in the fourth quarter. If price increases catch up with material and freight costs as Hureau described, the margin should recover from 13.4% toward the 16% level seen in the first half.
🔴 𝐕𝐞𝐠𝐞𝐭𝐚𝐭𝐢𝐨𝐧 𝐎𝐫𝐝𝐞𝐫𝐬 𝐅𝐞𝐥𝐥 𝟏𝟏% 𝐁𝐞𝐡𝐢𝐧𝐝 𝐅𝐚𝐜𝐭𝐨𝐫𝐲 𝐆𝐚𝐢𝐧𝐬
Management has argued that the worst is over for Vegetation Management after two quarters of sales growth. While underlying sales rose 2.7% in the third quarter, the release notes that the increase came from improved manufacturing throughput — clearing existing orders through the factories faster — rather than stronger customer demand.
The order numbers cut against the recovery story. By our math, Vegetation net bookings fell 10.5% from a year ago to $157.2 million, after running flat in the second quarter. New orders equalled 92% of sales, pulling the division's backlog down 5.2% from a year ago to $170.9 million, its first year-on-year decline in four quarters.
What to watch: Vegetation net bookings in the fourth quarter, when dealers place pre-season orders for spring mowing. A second quarter of 10% order declines would leave factories short of work once the current backlog is built.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
Two standing concerns about Alamo Group's margin plans and revenue predictability got no new data or fell short this quarter.
• Sequential sales drop: total revenue fell 10.6% from the second quarter to $403.1 million, a steeper fall than Hureau's comment last quarter that third-quarter sales move down slightly from the second quarter.
• Procurement and parts savings: management targets 3 percentage points of margin gain from centralised purchasing and higher-margin spare parts, but the release gave no figures on either lever; the quarterly filing or call will show if parts moved above 16% of sales.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐁𝐫𝐚𝐧𝐝 𝐄𝐱𝐢𝐭𝐬 𝐂𝐨𝐬𝐭 $𝟑𝟑 𝐌𝐢𝐥𝐥𝐢𝐨𝐧 𝐓𝐡𝐢𝐬 𝐐𝐮𝐚𝐫𝐭𝐞𝐫
Hureau said Alamo Group took a major step by "completing our planned portfolio optimization activities, particularly within our Vegetation Management Division, and acquiring Econ". Selling and shutting down weaker lines — including the Dixie Chopper mower and Boxer compact loader brands — triggered $33.3 million in pre-tax charges ($7.3 million against sales, $15.5 million in cost of sales, and $9.0 million in overhead), cutting reported profit per share to $0.17 vs $2.06 excluding one-offs.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐅𝐫𝐞𝐞 𝐜𝐚𝐬𝐡 𝐟𝐥𝐨𝐰 (𝟐𝟔𝐐𝟑): $𝟓𝟒.𝟖 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
By our math, third-quarter free cash flow — operating cash after capital spending — rose 3.3% from a year ago to $54.8 million, up from $40.4 million in the second quarter. Over the last twelve months, operating cash flow reached $158.3 million, or 204% of net income, easily topping the company's 100% target.
𝐈𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐢𝐞𝐬 𝐚𝐧𝐝 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞𝐬 (𝟐𝟔𝐐𝟑): $𝟒𝟐𝟎.𝟏 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Inventories fell by $12.2 million from June to $420.1 million, partly reflecting write-downs on exited product lines, though they remain 11.1% higher than a year ago because of the Petersen acquisition. Accounts receivable — money owed by customers — dropped 6.3% from a year ago to $314.0 million, releasing cash as third-quarter shipments slowed.
𝐒𝐡𝐚𝐫𝐞 𝐫𝐞𝐩𝐮𝐫𝐜𝐡𝐚𝐬𝐞𝐬 (𝟐𝟔𝐐𝟑): $𝟎.𝟐 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
By our math, Alamo Group spent just $0.16 million buying back its own shares in the third quarter, down from $9.4 million in the second quarter. Management conserved cash ahead of the $158.7 million Econ acquisition in October, leaving diluted share count down 0.2% from a year ago at 12.07 million.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐋𝐨𝐧𝐠-𝐓𝐞𝐫𝐦 𝐄𝐁𝐈𝐓𝐃𝐀 𝐌𝐚𝐫𝐠𝐢𝐧, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: ~𝟏𝟖% ⇘ decelerating
🠆 unchanged from ~18%
Unchanged. Alamo Group does not publish quarterly numerical outlooks in its earnings release, but it stands by its long-term target of an 18% EBITDA margin excluding one-offs (and 15% operating margin). Third-quarter EBITDA margin excluding one-offs came in at 13.0%, down from 14.2% in the second quarter, leaving a 5-percentage-point gap to the target.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐚𝐭 𝐚𝐫𝐞 𝐄𝐜𝐨𝐧'𝐬 𝐚𝐧𝐧𝐮𝐚𝐥 𝐬𝐚𝐥𝐞𝐬 𝐚𝐧𝐝 𝐩𝐫𝐨𝐟𝐢𝐭 𝐦𝐚𝐫𝐠𝐢𝐧𝐬?
Alamo Group paid $158.7 million for Econ Engineering in October but did not disclose its revenue or EBITDA. Investors need those figures to see the purchase price multiple and how much profit Econ will add in 2027.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐝𝐢𝐝 𝐈𝐧𝐝𝐮𝐬𝐭𝐫𝐢𝐚𝐥 𝐨𝐫𝐝𝐞𝐫𝐬 𝐠𝐫𝐨𝐰 𝐰𝐢𝐭𝐡𝐨𝐮𝐭 𝐏𝐞𝐭𝐞𝐫𝐬𝐞𝐧?
Industrial bookings jumped 24.2% from a year ago to $217.9 million, but Petersen was not in last year's base. Disclosing the organic order growth rate will show whether municipal demand for vacuum trucks and sweepers actually rebounded.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐝𝐢𝐝 𝐭𝐡𝐞 𝐞𝐱𝐢𝐭𝐞𝐝 𝐛𝐫𝐚𝐧𝐝𝐬 𝐠𝐞𝐧𝐞𝐫𝐚𝐭𝐞?
Winding down and selling Dixie Chopper, Boxer, and other lines cost $33.3 million in third-quarter charges. Management has not said how much annual revenue walked out the door with those brands or how much profit they were losing.
𝐖𝐢𝐥𝐥 𝐟𝐮𝐥𝐥-𝐲𝐞𝐚𝐫 𝐜𝐚𝐩𝐢𝐭𝐚𝐥 𝐬𝐩𝐞𝐧𝐝𝐢𝐧𝐠 𝐬𝐭𝐢𝐥𝐥 𝐫𝐞𝐚𝐜𝐡 $𝟐𝟖–𝟑𝟑 𝐦𝐢𝐥𝐥𝐢𝐨𝐧?
Capital spending totalled $16.1 million over the first nine months, including $5.7 million in Q3 by our math. Hitting the prior $28–33 million full-year outlook from the second-quarter filing would require $12–17 million in Q4 alone.

$IIPR Q3 2026 earnings: Innovative Industrial Properties cash flow rises, but contracted rent drops
Innovative Industrial Properties, a landlord to cannabis growers and life science developers, lost rent from evicted cannabis tenants while collecting interest from new loans. Contractual yearly base rent dropped 18% from June to $223 million as the company terminated 16 leases and repossessed buildings. Even so, executive chairman Alan Gold pointed to a 7% quarterly rise in per-share operating cash flow to $1.96, helped by $10 million of income from life science developer IQHQ and $12 million collected or seized from defaulted tenants.
• Contractual annualized base rent: $𝟐𝟐𝟐.𝟓𝐌 (-18.4% from last quarter)
• Operating portfolio leased rate: 𝟗𝟎.𝟎% (95.8% last quarter)
• AFFO per share (REIT cash flow): $𝟏.𝟗𝟔 (+14.6% from a year ago)
• Life science total commitments: $𝟓𝟒𝟓.𝟎𝐌 (up $275.0M this quarter)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🔴 Bearish
The story got worse because tenant defaults cut deep into the core property portfolio, knocking the leased rate down 6 percentage points to 90%. To replace that lost rent, the company doubled its commitments to IQHQ to $545 million while borrowing more and issuing 9.25% preferred stock. One positive: the landlord finished evicting PharmaCann and signed new tenants for several repossessed properties.
The question now is whether high-interest loans to IQHQ can carry the $1.90 quarterly dividend until replacement cannabis tenants start paying cash rent. Either IQHQ's 15% yields bridge the gap, or financing costs and exhausted security deposits pull recurring cash flow below the dividend. Fourth-quarter cash flow after security deposits run out will tell.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢 𝐓𝐞𝐧𝐚𝐧𝐭 𝐖𝐨𝐫𝐤𝐨𝐮𝐭𝐬 𝐂𝐥𝐞𝐚𝐫 𝐏𝐫𝐨𝐛𝐥𝐞𝐦 𝐋𝐞𝐚𝐬𝐞𝐬 𝐒𝐥𝐨𝐰𝐥𝐲
Innovative Industrial Properties is replacing cannabis tenants that stopped paying rent. In the third quarter, the landlord ended all remaining leases with PharmaCann and signed Grown Rogue to take over the New York cultivation facility. It also signed a new tenant for 4Front's former 114,000 square foot building in Washington, while Battle Green transferred its Ohio lease to an affiliate of Vireo Growth with a parent company guarantee.
After the quarter closed, the real estate trust signed a lease for a vacant 270,000 square foot facility in Pennsylvania, waiting on state cannabis license transfers. For the three remaining properties leased to 4Front, representing 7.1% of yearly base rent, the company has "tentative arrangements with prospective new tenants for the three assets leased to 4Front" that it expects to take effect when receivership ends, "anticipated to occur by year end 2026 or early 2027".
What to watch: the completion of the 4Front receivership proceedings by early 2027. Closing those transfers will show whether the new leases start paying cash rent without further delays.
🟢 𝐒𝐡𝐚𝐫𝐞 𝐁𝐮𝐲𝐛𝐚𝐜𝐤𝐬 𝐁𝐨𝐨𝐬𝐭𝐞𝐝 𝐏𝐞𝐫-𝐒𝐡𝐚𝐫𝐞 𝐂𝐚𝐬𝐡 𝐅𝐥𝐨𝐰
The cannabis landlord repurchased $89.0 million of its own common stock during the first nine months of 2026, mostly alongside its June convertible note offering. Because those buybacks happened midway through the second quarter, the third quarter was the first period to show their full effect on the share count.
Weighted-average diluted shares used to calculate operating cash flow dropped 3.5% from last quarter to 28.0 million. While total adjusted funds from operations (AFFO), a REIT cash flow measure that strips out property depreciation and one-off legal costs, rose 3.3% from the second quarter to $54.8 million, the lower share count lifted the per-share figure by 7.1% to $1.96. Note holders can exchange their debt for 5.8 million shares, which the company excludes from its per-share metric.
What to watch: any further common stock issuances or buybacks in the fourth quarter. Keeping the share count near 28.0 million helps the company cover its $1.90 quarterly dividend while it re-leases vacant buildings.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐋𝐞𝐚𝐬𝐞 𝐓𝐞𝐫𝐦𝐢𝐧𝐚𝐭𝐢𝐨𝐧𝐬 𝐂𝐮𝐭 𝐂𝐨𝐧𝐭𝐫𝐚𝐜𝐭𝐮𝐚𝐥 𝐑𝐞𝐧𝐭 𝐛𝐲 𝟏𝟖%
"We are pleased to report strong earnings with our AFFO per share up 7% compared to the second quarter, and are encouraged by the continued leasing momentum across our portfolio, reflecting our team's ongoing efforts to re-lease properties," executive chairman Alan Gold said. Gold wants investors to focus on the new leases signed this quarter.
The portfolio numbers show that tenant exits outpaced new signings by two to one. The company terminated 16 leases covering 1.2 million square feet after repossessing properties from PharmaCann, Parallel, and The Cannabist, while signing six leases for 604,000 square feet.
• Contractual annualized base rent: $222.5 million, down 18.4% from last quarter by our math
• Operating portfolio leased rate: 90.0%, down 5.8 percentage points from last quarter
• Florida portfolio leased rate: 47.9%, after Parallel defaulted on two properties
This matters because contractual base rent is the starting point for future revenue. Even after adding interest from new life science loans, combined yearly rent and interest fell 8.6% from June to $296.7 million by our math.
What to watch: contractual annualized base rent in the fourth quarter supplemental report. Another drop would show that new leases are still not replacing the rent lost from defaulted cannabis operators.
🔴🔴 𝐃𝐞𝐟𝐚𝐮𝐥𝐭 𝐑𝐞𝐜𝐨𝐯𝐞𝐫𝐢𝐞𝐬 𝐃𝐫𝐨𝐯𝐞 𝐭𝐡𝐞 𝐃𝐢𝐯𝐢𝐝𝐞𝐧𝐝 𝐂𝐨𝐯𝐞𝐫𝐚𝐠𝐞
Innovative Industrial Properties paid a $1.90 per share common dividend in the third quarter. With AFFO at $1.96 per share, the dividend payout ratio fell to 97%, bringing the payout below 100% for the first time in a year.
However, that coverage relied on temporary collections and seized collateral from troubled tenants. The company said the slight revenue increase came from "higher revenue related to properties repossessed during the third quarter of 2026 as a result of the application of security deposits, partially offset by lower rental revenue from property sales and lease terminations". Across five defaulted operators — PharmaCann, 4Front, Parallel, The Cannabist, and Battle Green — the landlord booked $7.8 million in cash payments and applied $3.8 million of security deposits, adding $11.6 million or $0.41 per share to cash flow.
Without those defaulted tenant items, AFFO was $1.55 per share by our math, well below the $1.90 dividend. Once a property is repossessed and its security deposit is spent, that temporary revenue stops until a new tenant moves in and starts paying rent.
What to watch: security deposits applied to revenue in the fourth quarter. Because Parallel and PharmaCann leases are now terminated, deposit income should fall, testing whether recurring cash flow can cover the $1.90 dividend.
🔴🔴 𝐋𝐢𝐟𝐞 𝐒𝐜𝐢𝐞𝐧𝐜𝐞 𝐋𝐨𝐚𝐧𝐬 𝐋𝐢𝐟𝐭 𝐈𝐧𝐜𝐨𝐦𝐞 𝐚𝐧𝐝 𝐒𝐢𝐧𝐠𝐥𝐞-𝐁𝐨𝐫𝐫𝐨𝐰𝐞𝐫 𝐑𝐢𝐬𝐤
To offset cannabis tenant defaults, management is lending heavily to the life science sector, which bulls view as a high-yield growth driver. In September, the company committed $245.0 million for a mezzanine loan — debt that sits behind senior mortgages — on the Alewife Park campus in Massachusetts, which Gold said "further expands our presence in the life science sector".
Every dollar of this life science portfolio is tied to one private developer, IQHQ, where Gold previously served as executive chairman. The landlord funded $111.0 million of the Alewife loan at closing (yielding 15.8%) and bought another $30.0 million of IQHQ preferred stock (yielding 15.0%), lifting Q3 IQHQ income to $10.4 million. Including $134.0 million of future Alewife loan draws, total commitments to IQHQ reached $545.0 million, or 17.9% of total gross assets by our math.
What to watch: paid-in-kind dividends and interest on life science investments on the cash flow statement, which totaled $5.1 million over the first nine months of 2026. If non-cash interest grows as a share of IQHQ income, the company collects less actual cash to pay its own dividends.
🔴 𝐍𝐞𝐰 𝐃𝐞𝐛𝐭 𝐚𝐧𝐝 𝐏𝐫𝐞𝐟𝐞𝐫𝐫𝐞𝐝 𝐒𝐡𝐚𝐫𝐞𝐬 𝐑𝐚𝐢𝐬𝐞 𝐅𝐮𝐧𝐝𝐢𝐧𝐠 𝐂𝐨𝐬𝐭𝐬
The company has demonstrated steady access to capital this year, issuing convertible notes, term loans, and preferred shares to pay off its May 2026 bonds and fund IQHQ investments. In October, it raised $54.2 million in gross proceeds from a new 9.25% Series B preferred stock offering and collected $49.0 million when the buyer of its Perth, New York property repaid a seller-financed loan.
However, this new capital costs much more than the retired 5.50% bonds. In the third quarter, interest expense jumped to $11.8 million from $4.5 million a year ago, while preferred stock dividends more than tripled to $3.2 million. Together, quarterly financing charges rose 171% from a year ago to $15.0 million by our math. In addition, the company only extended its $87.5 million revolving credit facility (carrying a 9.00% interest rate) by 90 days to January 21, 2027.
What to watch: the refinancing or repayment of the $87.5 million credit facility before January 21, 2027, and whether the company must pay a higher interest rate to secure a multi-year extension.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐅𝐞𝐝𝐞𝐫𝐚𝐥 𝐑𝐞𝐬𝐜𝐡𝐞𝐝𝐮𝐥𝐢𝐧𝐠 𝐑𝐞𝐦𝐚𝐢𝐧𝐬 𝐚 𝐌𝐞𝐝𝐢𝐜𝐚𝐥-𝐎𝐧𝐥𝐲 𝐒𝐭𝐞𝐩
In its investor presentation, Innovative Industrial Properties highlighted the April 2026 federal reclassification of state-licensed medical cannabis to Schedule III. The company noted that this change may remove Section 280E federal tax burdens for qualifying medical operators and improve their cash flow, while the Drug Enforcement Administration continues to evaluate broader changes to marijuana's federal status.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐍𝐞𝐭 𝐝𝐞𝐛𝐭 (𝟐𝟔𝐐𝟑): $𝟓𝟔𝟗.𝟐 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Net debt — total borrowings minus cash — rose 35.9% from last quarter, lifting leverage to 18.7% of total gross assets and 2.1 times annualized Adjusted EBITDA (up from 14% and 1.7 times in June). The company drew $85.0 million net on its credit lines to help fund $141.0 million of IQHQ investments in September.
𝐀𝐝𝐯𝐚𝐧𝐜𝐞 𝐫𝐞𝐧𝐭 𝐚𝐧𝐝 𝐬𝐞𝐜𝐮𝐫𝐢𝐭𝐲 𝐝𝐞𝐩𝐨𝐬𝐢𝐭𝐬 (𝟐𝟔𝐐𝟑): $𝟒𝟏.𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Rent received in advance and tenant security deposits held on the balance sheet fell 7.1% from June and 17.5% from December 2025 ($50.3 million). The balance shrinks each quarter as the landlord applies seized security deposits ($3.8 million in Q3) to cover unpaid rent from defaulted tenants.
𝐏𝐫𝐨𝐩𝐞𝐫𝐭𝐲 𝐞𝐱𝐩𝐞𝐧𝐬𝐞𝐬 (𝟐𝟔𝐐𝟑): $𝟔.𝟗 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Property expenses — taxes, insurance, and maintenance on buildings — dropped 12.7% from a year ago and 3.6% from the second quarter. As a share of total revenue, property costs fell 1.6 percentage points from a year ago to 10.7%.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐚𝐭 𝐫𝐞𝐧𝐭 𝐫𝐚𝐭𝐞𝐬 𝐝𝐢𝐝 𝐧𝐞𝐰 𝐭𝐞𝐧𝐚𝐧𝐭𝐬 𝐚𝐠𝐫𝐞𝐞 𝐭𝐨 𝐩𝐚𝐲?
The company signed six leases for 604,000 square feet in Q3 and another 270,000 square feet in October, but did not disclose the rent per square foot compared to the terminated contracts.
𝐖𝐡𝐲 𝐰𝐚𝐬 𝐭𝐡𝐞 𝐜𝐫𝐞𝐝𝐢𝐭 𝐟𝐚𝐜𝐢𝐥𝐢𝐭𝐲 𝐞𝐱𝐭𝐞𝐧𝐝𝐞𝐝 𝐟𝐨𝐫 𝐨𝐧𝐥𝐲 𝟗𝟎 𝐝𝐚𝐲𝐬?
After quarter end, the $87.5 million revolving credit facility (at 9.00% interest) was extended by just three months to January 21, 2027, leaving a near-term maturity to settle.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐨𝐟 𝐈𝐐𝐇𝐐'𝐬 𝐐𝟑 𝐢𝐧𝐜𝐨𝐦𝐞 𝐰𝐚𝐬 𝐩𝐚𝐢𝐝 𝐢𝐧 𝐜𝐚𝐬𝐡?
IQHQ generated $10.4 million of interest and dividend income in Q3, and nine-month cash flows show $5.1 million of non-cash paid-in-kind income, but the exact Q3 cash vs non-cash split was not disclosed.
𝐖𝐡𝐚𝐭 𝐢𝐬 𝐭𝐡𝐞 𝐬𝐭𝐚𝐭𝐮𝐬 𝐨𝐟 𝐭𝐡𝐞 𝐒𝐄𝐂 𝐢𝐧𝐯𝐞𝐬𝐭𝐢𝐠𝐚𝐭𝐢𝐨𝐧 𝐚𝐧𝐝 𝐥𝐚𝐰𝐬𝐮𝐢𝐭𝐬?
The company booked $784,000 of litigation-related expense in Q3 ($4.0 million over nine months), and the earnings release does not update the SEC subpoena or class action suits before the 10-Q filing.

$AESI Q3 2026 earnings: Atlas secures data center funding, but its sand business loses money
Atlas Energy Solutions, a supplier of oilfield frac sand and private power generators, saw its sand business swing to a gross loss while its power division expanded. Total revenue edged up 3% from a year ago, but EBITDA excluding one-offs dropped 40% from last quarter to $30 million as sand volumes and prices both fell. Chief executive John Turner said the company turned down low-priced sand bids, yet average sand prices still dropped to $16.93 per ton and plant costs missed targets.
• Revenue: $𝟐𝟔𝟕.𝟖𝐌 (+3.1% from a year ago)
• Ebitda, excluding one-offs: $𝟑𝟎.𝟑𝐌 (-40.4% from last quarter)
• Proppant average sales price: $𝟏𝟔.𝟗𝟑/𝐭𝐨𝐧 ($17.70/ton last quarter)
• Q4 Ebitda outlook, excluding one-offs: 𝐂𝐮𝐭 ($40–50M vs ~$50M prior floor)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🟢 Bullish
The story got better because two equipment reimbursement deals with an artificial intelligence lab and a $424 million bank bridge loan eased the immediate cash crunch on the power build-out. Those agreements cover 283 megawatts for two data center projects and rescued a balance sheet where cash had fallen to $22 million at quarter-end. The bad news: management's fourth-quarter profit outlook of $40 million to $50 million steps back from its earlier goal of matching the second quarter's $50 million.
The question now is whether the AI lab equipment agreements turn into long-term power contracts and whether refilled sand volumes carry higher prices. Bulls see scarce power generation slots locking in multi-year data center cash flows, while bears see nearly $1 billion of net debt backed by a shrinking commodity sand business. Binding data center contract announcements and fourth-quarter sand pricing will settle it.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐀𝐈 𝐋𝐚𝐛 𝐀𝐠𝐫𝐞𝐞𝐦𝐞𝐧𝐭𝐬 𝐄𝐚𝐬𝐞 𝐍𝐞𝐚𝐫-𝐓𝐞𝐫𝐦 𝐅𝐮𝐧𝐝𝐢𝐧𝐠 𝐑𝐢𝐬𝐤
Atlas is pivoting from oilfield sand to building private power plants for data centers, which required ordering over $1 billion of generators ahead of signed customer contracts. Chief executive John Turner said two new Cost Reimbursement Agreements (CRAs), where a customer pays for equipment upfront during talks, and a $424 million bank loan "have significantly reduced the near-term financing and supply chain risk".
The company signed those two agreements with a frontier artificial intelligence lab "supporting balance-of-plant equipment and an incremental 283 megawatts ("MW") to enable two significant data center projects". After the quarter closed, Goldman Sachs and Barclays provided the $424 million bridge loan, lifting total liquidity to $499.4 million as of October 23.
This matters because the AI lab is helping pay for transformer and switchgear equipment while the two sides negotiate final power contracts. However, reimbursement deals are not final long-term leases, as Turner noted the two projects are still "currently negotiating".
What to watch: binding long-term power purchase agreements on those 283 megawatts over the next two quarters. Converting reimbursement deals into multi-year contracts would allow Atlas to replace the temporary bridge loan with permanent project financing.
🟢 𝐏𝐨𝐰𝐞𝐫 𝐒𝐞𝐠𝐦𝐞𝐧𝐭 𝐂𝐚𝐫𝐫𝐢𝐞𝐬 𝐎𝐯𝐞𝐫 𝟒𝟎% 𝐨𝐟 𝐏𝐫𝐨𝐟𝐢𝐭
The power division rents natural gas generators to oilfield operators and technology companies that cannot wait for utility grid connections. While the legacy sand business struggled this quarter, power revenue jumped 90.3% from a year ago and 11.3% from last quarter to $32.6 million.
Gross profit excluding depreciation — revenue minus direct operating costs — reached $21.7 million in power, a 67% margin compared to 13% in sand and logistics. That gave power 41.5% of the company's $52.3 million total gross profit excluding depreciation, while Turner confirmed the first 120-megawatt permanent plant in Socorro, Texas "remains on track to come online at the end of the first quarter of next year".
What to watch: Socorro plant energization at the end of the first quarter of 2027. Turning that facility on starts a five-year contract that management expects to generate $50 million to $55 million of annual free cash flow.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐇𝐨𝐥𝐝𝐢𝐧𝐠 𝐒𝐚𝐧𝐝 𝐏𝐫𝐢𝐜𝐞𝐬 𝐂𝐮𝐭 𝐕𝐨𝐥𝐮𝐦𝐞 𝐚𝐧𝐝 𝐏𝐫𝐢𝐜𝐞
Atlas mines proppant — specialized sand pumped into oil wells during hydraulic fracturing — and delivers it across West Texas. Turner said management made a deliberate choice "to hold the line on pricing rather than chase uneconomic bids", adding that the commercial team has since refilled its order book "with line of sight to more than 23 million allocated tons for 2027".
• Proppant sales price: $16.93 per ton, down 4.4% from $17.70 last quarter and down 16.8% from a year ago
• Proppant sales volume: 5.4 million tons, down 3.6% from last quarter and near the 5.3 million floor
• Plant and logistics cost plus royalties: $14.06 per ton by our math, missing the $12.39 ceiling
• Logistics service margin excluding depreciation: 8.6% by our math, below the 10% floor
The numbers cut against the pricing discipline claim because refusing cheap orders did not stop average sand prices from falling another $0.77 per ton. Lower volume also hurt fixed-cost absorption at the plants, pushing cost of sales excluding depreciation up 5.3 percentage points of revenue from a year ago and swinging the sand division to a $10.1 million gross loss.
What to watch: fourth-quarter proppant average sales price. A drop below $16.93 per ton as refilled orders ship would show that Atlas gave up price to win back the 23 million tons for 2027.
🔴🔴 𝐏𝐨𝐰𝐞𝐫 𝐁𝐮𝐢𝐥𝐝 𝐃𝐫𝐚𝐢𝐧𝐞𝐝 𝐂𝐚𝐬𝐡 𝐁𝐞𝐟𝐨𝐫𝐞 𝐁𝐫𝐢𝐝𝐠𝐞 𝐋𝐨𝐚𝐧
Building private power plants requires heavy upfront spending before customers pay for electricity. In the third quarter, cash capital expenditures jumped to $184.7 million, or 69% of revenue, up from $153.8 million in the second quarter and $29.3 million in the first.
On an accrual basis, growth and maintenance capital spending totaled $186.9 million, consuming 93% of management's $200 million second-half budget in a single quarter by our math. That spending drained cash on the balance sheet from $168.2 million in June to $22.3 million in September and pushed net debt up to $963.2 million.
The $424 million bridge loan signed in October solved the immediate cash crunch, lifting cash back to $152.2 million by October 23. However, bridge loans are short-term debt, and $252.8 million of the remaining facility is already spoken for to pay for equipment purchase obligations.
What to watch: fourth-quarter capital expenditures against the remaining $13.1 million implied by the second-half budget. Spending far above that remainder would mean the full-year capital plan of $350 million to $375 million has been breached.
🔴 𝐅𝐨𝐮𝐫𝐭𝐡-𝐐𝐮𝐚𝐫𝐭𝐞𝐫 𝐏𝐫𝐨𝐟𝐢𝐭 𝐓𝐚𝐫𝐠𝐞𝐭 𝐒𝐭𝐞𝐩𝐬 𝐁𝐚𝐜𝐤 𝐅𝐫𝐨𝐦 𝐏𝐫𝐢𝐨𝐫 𝐅𝐥𝐨𝐨𝐫
Three months ago, management indicated that fourth-quarter EBITDA excluding one-offs — earnings before interest, taxes, depreciation and amortization — would match or beat the second quarter's level. The second quarter originally printed at $49.5 million and was revised up to $50.8 million in this release after reclassifying past legal costs.
Now Atlas forecasts fourth-quarter EBITDA excluding one-offs of $40 million to $50 million. Even though Turner said "we expect sequential improvement across all of our business lines during the fourth quarter", the $45 million middle of the range sits 11.5% below the restated second-quarter result.
What to watch: fourth-quarter EBITDA excluding one-offs against the $50 million top of the range. Falling short of $50 million would confirm that refilling sand volumes did not restore second-quarter profit power.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐓𝐡𝐢𝐬 𝐐𝐮𝐚𝐫𝐭𝐞𝐫 𝐃𝐢𝐝𝐧'𝐭 𝐀𝐧𝐬𝐰𝐞𝐫
Four standing risks from prior quarters received no new figures in the third-quarter earnings release.
• Oilfield power deployment: management targeted 180 to 200 megawatts deployed by year-end, but the release gave no third-quarter megawatt count.
• Term-loan leverage covenant: net debt reached $963.2 million while EBITDA excluding one-offs fell; the quarterly filing will show headroom under the 4.0x debt limit.
• Socorro contract renewal risk: the first data-center contract still has a five-year initial term, leaving long-term returns dependent on extensions.
• Convertible note dilution: $450 million of convertible debt still sits on the books with capped call protection ending at $22.32 per share.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐑𝐞𝐠𝐢𝐨𝐧𝐚𝐥 𝐋𝐨𝐠𝐢𝐬𝐭𝐢𝐜𝐬 𝐒𝐡𝐮𝐭𝐝𝐨𝐰𝐧 𝐀𝐝𝐝𝐬 𝐎𝐧𝐞-𝐎𝐟𝐟 𝐂𝐨𝐬𝐭
Weak oilfield completion activity outside the core Permian Basin prompted Atlas to pull back from a non-core operating area during the quarter. Within logistics operating costs, the company booked $1.4 million "tied to the cessation of operations in a particular region", which management identified in the footnotes as a Northeast logistics shutdown and added back to EBITDA excluding one-offs.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐅𝐫𝐞𝐞 𝐜𝐚𝐬𝐡 𝐟𝐥𝐨𝐰 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬 (𝟐𝟔𝐐𝟑): $𝟐𝟓.𝟑 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Fell from $38.3 million in the second quarter as operating profit dropped, though it rose 8.3% from $23.4 million a year ago. Atlas defines this measure as EBITDA excluding one-offs minus maintenance capital spending, which fell to $5.0 million this quarter from $12.6 million in the second quarter, lifting cash conversion to 84%.
𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐬 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞 (𝟐𝟔𝐐𝟑): $𝟐𝟏𝟒.𝟏 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇒ stable
Edged down from $217.5 million in June, contributing to a $13.1 million working capital cash inflow this quarter. However, uncollected customer bills remain 18.4% higher than the $180.8 million balance at the end of 2025 by our math, even though third-quarter revenue grew only 3.1% from a year ago.
𝐂𝐚𝐬𝐡 𝐨𝐯𝐞𝐫𝐡𝐞𝐚𝐝 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬 (𝟐𝟔𝐐𝟑): $𝟐𝟓.𝟐 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Cash selling, general and administrative expense rose 9.7% from $22.9 million last quarter and exceeded management's $22 million to $24 million target range. Total overhead was $38.8 million before stripping out $8.8 million of stock compensation, $2.1 million of depreciation, and $2.8 million of legal and transaction fees.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐐𝟒 𝟐𝟎𝟐𝟔 𝐄𝐁𝐈𝐓𝐃𝐀 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: $𝟒𝟎.𝟎–𝟓𝟎.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠇 cut from Match or exceed Q2 ($49.5M reported, $50.8M restated)
Cut. The new $45 million middle of the range is 48.4% higher than the third quarter's $30.3 million, but sits below the prior target of matching or beating the second quarter. Against last year's depressed fourth quarter of $36.7 million, the plan points to 22.5% growth by our math, driven by refilled sand orders and expanded power rentals.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐞𝐧 𝐰𝐢𝐥𝐥 𝐭𝐡𝐞 𝐀𝐈 𝐥𝐚𝐛 𝐚𝐠𝐫𝐞𝐞𝐦𝐞𝐧𝐭𝐬 𝐛𝐞𝐜𝐨𝐦𝐞 𝐛𝐢𝐧𝐝𝐢𝐧𝐠 𝐩𝐨𝐰𝐞𝐫 𝐜𝐨𝐧𝐭𝐫𝐚𝐜𝐭𝐬?
The two Cost Reimbursement Agreements cover 283 megawatts of equipment, but the power purchase agreements are still under negotiation. Investors need to know the expected signing timeline, contract length, and how much upfront capital the customer is reimbursing.
𝐀𝐭 𝐰𝐡𝐚𝐭 𝐩𝐫𝐢𝐜𝐞 𝐝𝐢𝐝 𝐀𝐭𝐥𝐚𝐬 𝐫𝐞𝐟𝐢𝐥𝐥 𝐟𝐨𝐮𝐫𝐭𝐡-𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐚𝐧𝐝 𝟐𝟎𝟐𝟕 𝐬𝐚𝐧𝐝 𝐯𝐨𝐥𝐮𝐦𝐞𝐬?
Proppant prices fell to $16.93 per ton in the third quarter even as management turned down cheap bids. With 23 million tons allocated for 2027, the average contract price on those tons determines whether sand cash flow recovers.
𝐖𝐢𝐥𝐥 𝐟𝐨𝐮𝐫𝐭𝐡-𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐜𝐚𝐩𝐢𝐭𝐚𝐥 𝐬𝐩𝐞𝐧𝐝𝐢𝐧𝐠 𝐛𝐫𝐞𝐚𝐜𝐡 𝐭𝐡𝐞 𝐟𝐮𝐥𝐥-𝐲𝐞𝐚𝐫 𝐛𝐮𝐝𝐠𝐞𝐭?
Third-quarter accrual capital spending of $186.9 million used up 93% of the $200 million second-half budget. Management did not update the $350 million to $375 million full-year capex range in the release.
𝐖𝐡𝐚𝐭 𝐚𝐫𝐞 𝐭𝐡𝐞 𝐢𝐧𝐭𝐞𝐫𝐞𝐬𝐭 𝐫𝐚𝐭𝐞 𝐚𝐧𝐝 𝐦𝐚𝐭𝐮𝐫𝐢𝐭𝐲 𝐨𝐧 𝐭𝐡𝐞 $𝟒𝟐𝟒𝐌 𝐛𝐫𝐢𝐝𝐠𝐞 𝐥𝐨𝐚𝐧?
Atlas drew down roughly $171 million of the new Goldman Sachs and Barclays bridge facility by October 23, with $252.8 million reserved for equipment obligations. The cost and due date of this short-term facility matter until project debt replaces it.

$INSP Q3 2026 earnings: Inspire wins a 2028 billing code, but 2026 sales shrink
Inspire Medical Systems, the maker of implanted sleep-apnea nerve stimulators, grew sales from last quarter while year-over-year revenue kept falling. Third-quarter revenue dropped 8% from a year ago to $207 million, which beat the company's own plan as U. S. doctors adjusted to new Medicare billing rules. Chief executive Tim Herbert kept the middle of the full-year sales outlook unchanged, so by our math the plan points to a 10% drop in the fourth quarter.
• Revenue: $𝟐𝟎𝟔.𝟕𝐌 (-7.9% from a year ago, +3.0% from last quarter)
• Operating margin, excluding one-offs: 𝟎.𝟗% (4.9% a year ago)
• Full-year revenue outlook: 𝐍𝐚𝐫𝐫𝐨𝐰𝐞𝐝 ($850–860M (middle of the range unchanged at -6%))
• Initial 2027 revenue outlook: 𝐋𝐨𝐰-𝐬𝐢𝐧𝐠𝐥𝐞 𝐝𝐢𝐠𝐢𝐭 𝐠𝐫𝐨𝐰𝐭𝐡 (first issued in presentation)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because a long-term billing win was offset by a weak 2027 growth preview. Medical regulators approved a dedicated billing code for the newer Inspire V implant starting in 2028, which removes a major long-term hurdle, and a Q3 beat shows the prior plan was cautious. The bad news: management previewed only low-single-digit sales growth for 2027 against an easy 2026 comparison, while restructuring and legal settlements pushed the third quarter into a $24 million reported loss.
The question now is whether the 2026 sales drop is just temporary billing friction or permanent demand loss from weight-loss drugs and new rivals. If billing friction is the only problem, higher proposed 2027 Medicare hospital payments will lift implant volumes quickly; if weight-loss drugs are shrinking the patient pool, growth will stay in the low single digits. Management's formal 2027 revenue plan next quarter will settle it.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
concern eased — 𝐀 𝐃𝐞𝐝𝐢𝐜𝐚𝐭𝐞𝐝 𝐁𝐢𝐥𝐥𝐢𝐧𝐠 𝐂𝐨𝐝𝐞 𝐀𝐫𝐫𝐢𝐯𝐞𝐬 𝐟𝐨𝐫 𝟐𝟎𝟐𝟖
Inspire Medical Systems makes implanted nerve stimulators that keep airways open during sleep. Its fifth-generation device, Inspire V, uses a single wire lead, and the lack of a dedicated medical billing code (CPT code) has disrupted U. S. sales all year. After rejecting an initial request in May, the American Medical Association panel approved a dedicated Category I billing code in September.
"When this takes effect in January 2028, a dedicated code set will give physicians and hospitals enhanced clarity around coding and reimbursement," chief executive Tim Herbert said. The approval removes the risk that doctors must bill under temporary modifiers forever. However, the new code does not start for five quarters, and a medical committee still has to set the doctor payment rate in mid-2027.
What to watch: the final 2027 Medicare hospital and surgery-center payment rules due in November 2026. If Medicare locks in its proposed 12% to 15% facility rate increases, clinics will have a financial reason to schedule more implants before the 2028 code starts.
🟢 𝐒𝐞𝐪𝐮𝐞𝐧𝐭𝐢𝐚𝐥 𝐆𝐫𝐨𝐰𝐭𝐡 𝐑𝐞𝐭𝐮𝐫𝐧𝐬 𝐚𝐬 𝐁𝐢𝐥𝐥𝐢𝐧𝐠 𝐅𝐫𝐢𝐜𝐭𝐢𝐨𝐧 𝐄𝐚𝐬𝐞𝐬
In the first half of 2026, U. S. hospitals and surgeons slowed implants because Medicare discontinued the old billing code for Inspire V. Management rolled out temporary hospital billing codes (C-codes) in April and educated clinics on how to submit claims. In the third quarter, revenue rose 3.0% from the second quarter to $206.7 million, beating the company's plan for an 8% to 10% year-over-year drop.
Herbert said "there is greater comfort among implanting physicians with the current coding dynamic." Only two regional Medicare contractors cut surgeon fees under the temporary billing modifier, and all six states in Medicare's prior-approval pilot (WISeR) adopted the new hospital code. Meanwhile, the shift to Inspire V lifted gross margin by 0.2 percentage points from a year ago to 86.0%, and new conference studies backed the therapy's health benefits.
What to watch: whether sequential revenue growth continues in the first quarter of 2027 after the holiday season. A drop worse than normal first-quarter seasonality would show that doctor comfort alone cannot overcome the lower surgeon fee.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐓𝐡𝐞 𝐎𝐮𝐭𝐥𝐨𝐨𝐤 𝐋𝐞𝐚𝐯𝐞𝐬 𝐅𝐨𝐮𝐫𝐭𝐡-𝐐𝐮𝐚𝐫𝐭𝐞𝐫 𝐒𝐚𝐥𝐞𝐬 𝐃𝐨𝐰𝐧 𝟏𝟎%
Herbert highlighted that third-quarter U. S. performance beat internal expectations as doctors grew comfortable with billing rules. Yet the sleep-therapy maker only narrowed its full-year revenue forecast to $850 million to $860 million, leaving the $855 million middle of the range unchanged. Because third-quarter revenue beat the prior plan by $2.4 million, holding the full-year midpoint trims the fourth-quarter outlook by the same amount.
• Third-quarter revenue: $206.7 million, down 7.9% from a year ago
• Fourth-quarter revenue implied by the full-year outlook: $243.1 million at the middle of the range, down 9.6% from a year ago by our math
• Initial 2027 revenue preview: "Anticipating low-single digit growth in 2027" on slide 26 of the investor presentation
A deeper year-over-year decline in the fourth quarter cuts against the claim that billing friction is steadily fading. Furthermore, the first half of 2026 suffered from severe billing disruption, so a low-single-digit rebound in 2027 barely recovers the lost ground.
What to watch: formal 2027 revenue outlook on the fourth-quarter report in early 2027. A forecast below 5% growth against an easy 2026 comparison would indicate that demand is slowing beyond temporary billing issues.
🔴 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐏𝐫𝐨𝐟𝐢𝐭 𝐍𝐨𝐰 𝐑𝐞𝐬𝐭𝐬 𝐨𝐧 𝐭𝐡𝐞 𝐅𝐨𝐮𝐫𝐭𝐡 𝐐𝐮𝐚𝐫𝐭𝐞𝐫
Falling sales are squeezing profitability even before one-time charges. Reported selling and administrative costs (marketing, sales reps, and overhead) jumped 18.4 percentage points of revenue from a year ago to 89.2% because of restructuring and legal bills. Excluding those one-offs, by our math, selling and administrative costs still rose 4.2 percentage points to 74.4% of revenue, while research and development stayed flat at 10.7%.
As a result, operating margin excluding one-offs fell 4.0 percentage points from a year ago to 0.9%, or $1.9 million. For the first nine months of 2026, operating profit excluding one-offs totals $5.4 million. Yet management kept its full-year operating margin target at 4.5% to 5.5% excluding one-offs. By our math, that leaves $37.4 million of profit—a 15.4% margin—for the fourth quarter alone.
What to watch: fourth-quarter operating margin excluding one-offs against the implied 15.4% target. A shortfall in high-deductible fourth-quarter procedures would cause Inspire to miss its full-year profit plan.
🔴 𝐋𝐞𝐠𝐚𝐥 𝐂𝐨𝐬𝐭𝐬 𝐌𝐨𝐮𝐧𝐭 𝐖𝐡𝐢𝐥𝐞 𝐈𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 𝐊𝐞𝐞𝐩𝐬 𝐏𝐢𝐥𝐢𝐧𝐠 𝐔𝐩
Inspire faces a Department of Justice investigation into its marketing and billing practices, patent lawsuits with rival Nyxoah, and shareholder lawsuits. This quarter, the device maker also booked a $7.0 million charge for the "proposed settlement of a pixel-tracking class action" alongside $3.6 million in ongoing legal fees. Meanwhile, net inventory on the balance sheet climbed again even though sales shrank.
• Third-quarter legal fees and settlement: $10.6 million combined, or 5.1% of revenue by our math
• Net inventories: $179.0 million, up 26.2% from a year ago and up 5.0% from last quarter by our math
• Inventory relative to sales: 86.6% of third-quarter revenue, up from 63.2% a year ago by our math
Holding $179.0 million of inventory—more than six quarters of manufacturing cost—ties up cash and creates write-down risk as clinics stop using older Inspire IV units.
What to watch: inventory reserves and legal disclosures in the third-quarter 10-Q filing. Any write-down of older Inspire IV stock or new settlement reserves would show these balance-sheet risks turning into losses.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
Three standing threats to patient demand received no new figures in the third-quarter release or presentation.
• Weight-loss drugs (GLP-1s): previously flagged as a near-term sales headwind; the quarterly filing's risk discussion will show if patient deferrals worsened.
• Medicare prior-approval pilot (WISeR): active in six states; CMS announcements will show if the agency expands the program to more states in 2027.
• Rival implants: Nyxoah launched its competing Genio sleep device in the U. S.; fourth-quarter center productivity will show if rivals are taking share.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐏𝐫𝐨𝐣𝐞𝐜𝐭 𝐇𝐨𝐫𝐢𝐳𝐨𝐧 𝐑𝐞𝐬𝐭𝐫𝐮𝐜𝐭𝐮𝐫𝐢𝐧𝐠 𝐑𝐞𝐜𝐨𝐠𝐧𝐢𝐳𝐞𝐬 $𝟐𝟒 𝐌𝐢𝐥𝐥𝐢𝐨𝐧 𝐂𝐡𝐚𝐫𝐠𝐞
In August, Inspire launched a cost-cutting program it calls Project Horizon, focused on "Optimizing organizational structure and supply chain to reallocate $30 million of annualized operating expense to drive future revenue growth." In the third quarter, the company recorded $24.1 million in pre-tax restructuring charges—about 95% of the expected $25 million total—and a $4.1 million stock-pay credit from employee departures. Management plans to redirect the savings into patient scheduling and education starting in 2027.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐜𝐚𝐬𝐡 𝐟𝐥𝐨𝐰 (𝟐𝟔𝐐𝟑): $𝟒𝟔.𝟒 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Cash generated from operations doubled from $23.2 million last quarter, lifting total cash and investments to $453.1 million. However, operating cash flow fell 32.3% from $68.5 million a year ago because net earnings dropped and last year's third quarter included a one-time catch-up in customer collections after a billing-portal delay.
𝐃𝐢𝐥𝐮𝐭𝐞𝐝 𝐬𝐡𝐚𝐫𝐞 𝐜𝐨𝐮𝐧𝐭 (𝟐𝟔𝐐𝟑): 𝟐𝟖.𝟗 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Weighted average diluted shares fell 2.3% from 29.6 million a year ago and stayed flat from last quarter. The medical-device maker bought back $175 million of stock in 2025, which lowered the share count, but it has not repurchased shares in 2026 despite holding $453.1 million in cash and investments with zero debt.
𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐬 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞 (𝟐𝟔𝐐𝟑): $𝟏𝟎𝟒.𝟕 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇒ stable
Money owed by hospitals and clinics for delivered devices fell 3.0% from a year ago and rose 1.3% from last quarter, moving in line with third-quarter sales. Since December 2025, accounts receivable have dropped 12.5% from $119.7 million as billing-portal collection delays from 2025 cleared.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟔 𝐑𝐞𝐯𝐞𝐧𝐮𝐞: $𝟖𝟓𝟎–𝟖𝟔𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠆 unchanged from $835–875 million
Unchanged at the middle of the range. The sleep-therapy group tightened its forecast by $15 million on both ends, keeping the midpoint at $855 million, or a 6.2% drop from 2025. By our math, that leaves $243.1 million for the fourth quarter—a 9.6% drop from a year ago, steeper than the third quarter's 7.9% decline. After a $125 million cut in the first quarter and a $5 million raise in the second, the full-year target has stabilized.
𝐅𝐘𝟐𝟔 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐦𝐚𝐫𝐠𝐢𝐧, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: 𝟒.𝟓%–𝟓.𝟓% ⇗ accelerating
🠆 unchanged from 4.0%–6.0%
Unchanged at the middle of the range. The plan still calls for a 5.0% operating margin excluding one-offs this year, down from 7.3% in 2025. Because the first nine months delivered a 0.9% margin, by our math, the fourth quarter must reach a 15.4% margin ($37.4 million in operating profit) on seasonally higher year-end procedure volume.
𝐅𝐘𝟐𝟔 𝐃𝐢𝐥𝐮𝐭𝐞𝐝 𝐄𝐏𝐒, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: $𝟏.𝟐𝟎–$𝟏.𝟒𝟎 ⇗ accelerating
🠅 raised from $1.05–$1.45
Raised. Management lifted the middle of the range by $0.05 to $1.30 per share, which still represents a 46.3% drop from $2.42 in 2025. With $0.38 earned in the first nine months, by our math, the outlook leaves $0.92 per share for the fourth quarter, helped by a lower share-count assumption of 28.9 million.
𝐅𝐘𝟐𝟔 𝐃𝐢𝐥𝐮𝐭𝐞𝐝 𝐄𝐏𝐒 (𝐆𝐀𝐀𝐏): $(𝟎.𝟑𝟔)–$(𝟎.𝟏𝟎) ⇄ reversing
🠇 cut from $(0.42)–$0.17
Cut. The middle of the range moved down by $0.105 to a loss of $0.23 per share, as the new $7.0 million legal settlement and $24.1 million in Project Horizon restructuring charges weighed on reported results. By our math, after a loss of $1.23 per share in the first nine months, the plan requires $1.00 of reported profit per share in the fourth quarter.
𝐅𝐘𝟐𝟔 𝐄𝐟𝐟𝐞𝐜𝐭𝐢𝐯𝐞 𝐭𝐚𝐱 𝐫𝐚𝐭𝐞 (𝐆𝐀𝐀𝐏 𝐚𝐧𝐝 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬): 𝟏𝟐𝟎%–𝟏𝟕𝟓% 𝐆𝐀𝐀𝐏 (𝟑𝟑%–𝟑𝟒% 𝐞𝐱𝐜𝐥. 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬) ⇗ accelerating
🠅 raised from 95%–100% GAAP (30%–35% excl. one-offs)
Raised on a reported basis. Inspire lifted its reported tax-rate assumption to 120%–175% because employee stock awards vested at lower values than when granted, creating $16.0 million in non-deductible tax charges over the first nine months. Excluding one-offs, the tax rate outlook narrowed to 33%–34%, slightly above the 32.7% rate recorded in the first nine months.
𝐅𝐘𝟐𝟔 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐞𝐱𝐩𝐞𝐧𝐝𝐢𝐭𝐮𝐫𝐞𝐬 𝐚𝐧𝐝 𝐝𝐢𝐥𝐮𝐭𝐞𝐝 𝐬𝐡𝐚𝐫𝐞𝐬: $𝟑𝟓–𝟒𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐜𝐚𝐩𝐞𝐱; ~𝟐𝟖.𝟗 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐬𝐡𝐚𝐫𝐞𝐬 ⇒ stable
🠆 unchanged from $35–40 million capex; ~29.4 million shares
Equipment spending held; share count trimmed. Capital spending remains at $35 million to $40 million following two cuts earlier in the year. Management lowered its full-year diluted share estimate by 0.5 million to 28.9 million, matching the third quarter's actual share count and reflecting employee share forfeitures from the Project Horizon layoffs.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐲 𝐝𝐨𝐞𝐬 𝟐𝟎𝟐𝟕 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐠𝐫𝐨𝐰 𝐨𝐧𝐥𝐲 𝐥𝐨𝐰-𝐬𝐢𝐧𝐠𝐥𝐞 𝐝𝐢𝐠𝐢𝐭𝐬?
The first half of 2026 lost about $60 million in sales to billing disruption. If doctors are now comfortable with the codes and Medicare proposes 12% to 15% higher hospital payments for 2027, why does slide 26 preview only low-single-digit growth next year?
𝐖𝐡𝐚𝐭 𝐚𝐫𝐞 𝐭𝐡𝐞 𝐚𝐜𝐭𝐮𝐚𝐥 𝐩𝐫𝐢𝐨𝐫-𝐚𝐮𝐭𝐡𝐨𝐫𝐢𝐳𝐚𝐭𝐢𝐨𝐧 𝐚𝐧𝐝 𝐔.𝐒. 𝐢𝐦𝐩𝐥𝐚𝐧𝐭 𝐯𝐨𝐥𝐮𝐦𝐞𝐬?
Management calls insurance prior-authorization submissions its main leading indicator, yet the release gives no numbers for submissions or U. S. procedures. Without those counts, investors cannot tell if patient demand is recovering or if weight-loss drugs are shrinking the funnel.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐨𝐟 𝐭𝐡𝐞 $𝟏𝟕𝟗 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 𝐢𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 𝐢𝐬 𝐈𝐧𝐬𝐩𝐢𝐫𝐞 𝐈𝐕?
Net inventory has grown to $179.0 million—more than six quarters of cost of goods sold—even after Project Horizon wrote down $24.1 million in restructuring costs. How much older Inspire IV stock remains on the books, and could it require a write-down?
𝐖𝐡𝐚𝐭 𝐢𝐬 𝐭𝐡𝐞 𝐬𝐭𝐚𝐭𝐮𝐬 𝐨𝐟 𝐭𝐡𝐞 𝐉𝐮𝐬𝐭𝐢𝐜𝐞 𝐃𝐞𝐩𝐚𝐫𝐭𝐦𝐞𝐧𝐭 𝐢𝐧𝐯𝐞𝐬𝐭𝐢𝐠𝐚𝐭𝐢𝐨𝐧?
Inspire spent $3.6 million this quarter ($8.7 million year-to-date) on legal fees for the Department of Justice billing probe and Nyxoah patent suits, plus $7.0 million to settle a privacy suit. Has the government made any demands regarding billing practices?

$PS Q3 2026 earnings: Pershing Square grows fee revenue, but taxes cut cash profit
Pershing Square collected its first full quarter of fees from its new US fund, but new corporate taxes reduced cash profit. Management fees excluding one-offs rose 15% from a year ago to $76 million, while underlying fees without the new US vehicle fell 20% by our math. Because the alternative asset manager now pays corporate taxes, distributable profit fell 12% to $49 million and the firm cut its dividend.
• Management fees excluding PSUS: $𝟓𝟐.𝟕𝐌 (-20% from a year ago by our math)
• Management fees, excluding one-offs: $𝟕𝟓.𝟔𝐌 (+15% from a year ago)
• Distributable profit per share: $𝟎.𝟏𝟐 (-14% from a year ago after new corporate taxes)
• Corporate tax outlook: 𝐔𝐧𝐜𝐡𝐚𝐧𝐠𝐞𝐝 ($11.5M first-time tax charge in Q3)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because the third-quarter fee step-up and the corporate tax drag both came from April's initial public offering mechanics. Portfolio gains added $813 million to fee-paying assets and lifted the fee margin to 84%, which helps next quarter's billing base. One caution: the new US fund closed the quarter 26% below its $50 offering price by our math, while credit line debt rose to fund $80 million of venture seed investments.
The question now is whether Pershing Square can grow its fee base through new fund launches or remains tied to stock market gains in its existing portfolio. If it launches its venture fund to outside investors and narrows the US fund's price discount, fee growth can resume; otherwise, growth depends on market marks. Fourth-quarter fundraising updates and year-end performance fee results will decide.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢 𝐍𝐞𝐰 𝐔𝐒 𝐅𝐮𝐧𝐝 𝐋𝐢𝐟𝐭𝐞𝐝 𝐅𝐞𝐞 𝐏𝐫𝐨𝐟𝐢𝐭
Pershing Square earns management fees as a percentage of the money in its investment funds. In April the firm launched Pershing Square USA (PSUS), a New York-listed fund that charges a 2% annual fee. Because "Management fee revenue for Q2 2026 reflects fees earned from PSUS only for the portion of the quarter following the closing of the Combined IPO on April 30, 2026", the third quarter was its first full period of fees.
PSUS generated $23.0 million of management fees, up from $16.5 million in the second quarter. That pushed total management fees, excluding one-offs, up 14.7% from a year ago to $75.6 million. Operating expenses scarcely grew: employee pay fell 0.7 percentage points of fee revenue to 7.5%, and overhead fell 1.0 percentage point to 7.6%. As a result, fee-related earnings — operating profit from recurring fees — rose 12.7% to $63.7 million, and the fee margin expanded 1.9 percentage points to 84.2%.
What to watch: fourth-quarter gross management fees. Because the firm bills its funds in advance based on assets at the start of the quarter, the 3.2% third-quarter rise in fee-paying assets points to higher fee revenue next quarter.
🟢 𝐏𝐨𝐫𝐭𝐟𝐨𝐥𝐢𝐨 𝐆𝐚𝐢𝐧𝐬 𝐒𝐭𝐚𝐛𝐢𝐥𝐢𝐬𝐞𝐝 𝐭𝐡𝐞 𝐅𝐞𝐞 𝐁𝐚𝐬𝐞
Pershing Square pitches itself as a manager of permanent capital — fund money that investors cannot redeem on demand. That structure protects the firm from client withdrawals, which reached 98% of fee-paying assets at quarter-end, but it still leaves the fee base exposed when stock prices fall.
In the third quarter, rising portfolio values added $813 million to fee-paying assets under management (FPAUM), the capital base on which the firm earns fees. That lifted FPAUM 3.2% from the prior quarter to $22.96 billion, with gains across the flagship European fund PSH (+$417 million), PSUS (+$250 million) and real estate group Howard Hughes (+$134 million). Still, third-quarter gains only partly reversed earlier drops, leaving nine-month market changes at negative $1.95 billion.
What to watch: year-end net asset value for PSH in the fourth-quarter report. A strong fourth-quarter portfolio gain is required to push PSH above its high-water mark — the peak value it must beat to earn performance bonuses — and unlock annual performance fees.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐔𝐧𝐝𝐞𝐫𝐥𝐲𝐢𝐧𝐠 𝐅𝐞𝐞𝐬 𝐅𝐞𝐥𝐥 𝐖𝐢𝐭𝐡𝐨𝐮𝐭 𝐭𝐡𝐞 𝐔𝐒 𝐅𝐮𝐧𝐝
The company highlights that its recurring fee revenue grew 10% from a year ago. However, all of that growth came from adding PSUS in April, while fees from its existing funds shrank.
• Management fees excluding PSUS: $52.7 million, down 20.1% from a year ago by our math
• PSH management fees: $47.2 million, down 14.2% from a year ago
• Howard Hughes variable fee: $0, compared with $3.4 million a year ago
• Private funds management fees: $1.7 million, down 55.4% after "investor withdrawals and redemptions from PSLP and PSINTL in order to participate in the Combined IPO and Combined Private Placement"
By our math, fee-paying assets outside PSUS stood at $18.12 billion, down 17.6% from $21.98 billion a year ago. Furthermore, PSUS shares closed the quarter at $37.10, which is 25.8% below their $50.00 initial offering price by our math. Because a fund trading below its asset value cannot easily sell new shares without diluting existing holders, Pershing Square relies on portfolio gains rather than new share sales to grow its core fees.
What to watch: the market price of PSUS relative to its asset value in the fourth quarter. A persistent discount blocks follow-on share offerings for the fund.
🔴 𝐂𝐨𝐫𝐩𝐨𝐫𝐚𝐭𝐞 𝐓𝐚𝐱𝐞𝐬 𝐂𝐮𝐭 𝐂𝐚𝐬𝐡 𝐟𝐨𝐫 𝐃𝐢𝐯𝐢𝐝𝐞𝐧𝐝𝐬
Before going public in April, Pershing Square operated as a partnership and paid no federal corporate income tax. The company noted that "Following the Corporate Conversion effected in connection with the Combined IPO, PS Inc. is subject to U. S. federal, state and local corporate income taxes."
The third quarter brought the first tax bill inside distributable earnings, the firm's measure of cash profit available for dividends. Taxes and related payables took $11.5 million, or 18.9% of pre-tax distributable profit by our math. Combined with $2.7 million of net interest expense, the tax charge pushed after-tax distributable earnings down 12.4% from a year ago — and 8.9% from last quarter — to $49.5 million, or $0.12 per share. Consequently, the firm cut its quarterly dividend by 15.6% by our math, from $0.122 to $0.103 per share.
What to watch: the tax line in fourth-quarter distributable earnings. It will show whether the 18.9% tax deduction is the normal rate on recurring fees and annual performance fees.
🔴 𝐃𝐞𝐛𝐭-𝐅𝐮𝐧𝐝𝐞𝐝 𝐒𝐭𝐚𝐤𝐞𝐬 𝐖𝐞𝐢𝐠𝐡 𝐨𝐧 𝐭𝐡𝐞 𝐁𝐚𝐥𝐚𝐧𝐜𝐞 𝐒𝐡𝐞𝐞𝐭
Pershing Square uses its own balance sheet to seed new funds, which bulls view as a pipeline for future fee growth and bears view as a balance-sheet risk. While paying out most of its cash profit as dividends, the firm has borrowed on its credit lines to buy stakes in its own funds.
At the end of September, the company held $80 million of investments in Pershing Square Ventures (PS Ventures), its new venture vehicle, alongside $196 million in PSUS shares and $663 million in Howard Hughes stock. To fund these holdings, outstanding debt reached $297 million — a $100 million term loan and $197 million on its revolving credit line — while cash stood at $1 million. Meanwhile, falling share prices at PSUS caused another $3.5 million paper loss this quarter, bringing nine-month paper losses on PSUS to $53.9 million.
What to watch: formal launch terms and external fundraising for PS Ventures by year-end. Raising outside capital would turn the $80 million debt-funded seed into fee-paying assets.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
Several standing risks around annual bonus fees, legal disputes and governance received no new detail in the third-quarter earnings release.
• Flagship fund performance fees: PSH crystallizes its annual performance fee on December 31; the release recorded zero preferred performance fees for the third quarter and did not state how far PSH sits below its high-water mark.
• Howard Hughes variable fee: Howard Hughes shares closed at $73.62, above the initial $66.15 reference price, yet the variable fee dropped to zero; the quarterly filing will clarify the volume-weighted average price calculation.
• Howard Hughes contract lawsuit: the release gave no update on the shareholder lawsuit challenging the Howard Hughes management contract; the quarterly filing's legal footnote will carry any court developments.
• Founder control and share exchange: no new disclosures on the agreement allowing the founder to exchange PSH shares for company stock in later years.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐈𝐏𝐎 𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐢𝐧𝐠 𝐂𝐡𝐚𝐫𝐠𝐞𝐬 𝐊𝐞𝐩𝐭 𝐑𝐞𝐬𝐮𝐥𝐭𝐬 𝐍𝐞𝐠𝐚𝐭𝐢𝐯𝐞
Under standard accounting rules, Pershing Square reported a third-quarter net loss of $19.9 million, or $0.05 per share. Two non-cash items from the April initial public offering caused the loss: $64.8 million of "non-cash amortization expense related to employee equity grants" and $19.0 million of revenue deductions for shares given to initial fund investors and the Howard Hughes contract premium. Both charges will recur for years without reducing cash flow.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐓𝐨𝐭𝐚𝐥 𝐚𝐬𝐬𝐞𝐭𝐬 𝐮𝐧𝐝𝐞𝐫 𝐦𝐚𝐧𝐚𝐠𝐞𝐦𝐞𝐧𝐭 (𝟐𝟔𝐐𝟑): $𝟑𝟐.𝟕𝟖 𝐛𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Total assets under management — which include fund debt and employee money that does not pay fees — rose 0.9% from last quarter and 4.2% from a year ago. Market gains of $836 million and $18 million of private fund inflows outweighed $565 million of outflows, which primarily reflected debt changes at Howard Hughes.
𝐑𝐞𝐩𝐨𝐫𝐭𝐞𝐝 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 (𝟐𝟔𝐐𝟑): $𝟓𝟔.𝟔𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇄ reversing
Revenue under standard accounting fell 14.5% from a year ago by our math, but rose 4.5% from the second quarter. The figure deducts $19.0 million of non-cash amortization for shares granted to initial PSUS investors and the Howard Hughes contract premium, up from $13.9 million in the second quarter and $3.7 million a year ago.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐂𝐨𝐫𝐩𝐨𝐫𝐚𝐭𝐞 𝐢𝐧𝐜𝐨𝐦𝐞 𝐭𝐚𝐱𝐞𝐬 𝐢𝐧 𝐝𝐢𝐬𝐭𝐫𝐢𝐛𝐮𝐭𝐚𝐛𝐥𝐞 𝐞𝐚𝐫𝐧𝐢𝐧𝐠𝐬: $𝟏𝟏.𝟓𝟑 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠆 unchanged from Subject to corporate income tax beginning in Q3 2026
Unchanged. The firm previously stated that distributable earnings would include corporate income taxes starting in the third quarter, and it booked an $11.5 million charge. By our math, that equals an 18.9% tax rate on $61.0 million of pre-tax distributable earnings, reducing after-tax cash profit to $49.5 million.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐇𝐨𝐰 𝐟𝐚𝐫 𝐢𝐬 𝐏𝐒𝐇 𝐟𝐫𝐨𝐦 𝐢𝐭𝐬 𝐩𝐞𝐫𝐟𝐨𝐫𝐦𝐚𝐧𝐜𝐞 𝐟𝐞𝐞 𝐭𝐡𝐫𝐞𝐬𝐡𝐨𝐥𝐝?
Pershing Square earns up to $115.6 million in preferred performance fees at year-end if its flagship PSH fund rises about 5% above its peak asset value. The release did not disclose PSH's distance to that mark at September 30.
𝐖𝐡𝐲 𝐰𝐚𝐬 𝐭𝐡𝐞 𝐇𝐨𝐰𝐚𝐫𝐝 𝐇𝐮𝐠𝐡𝐞𝐬 𝐯𝐚𝐫𝐢𝐚𝐛𝐥𝐞 𝐟𝐞𝐞 𝐳𝐞𝐫𝐨?
Howard Hughes shares ended the quarter at $73.62, well above the initial $66.15 reference price, yet Pershing Square booked zero variable fee in the third quarter after booking $64,000 in the second quarter.
𝐖𝐡𝐚𝐭 𝐚𝐫𝐞 𝐭𝐡𝐞 𝐥𝐚𝐮𝐧𝐜𝐡 𝐭𝐞𝐫𝐦𝐬 𝐟𝐨𝐫 𝐏𝐞𝐫𝐬𝐡𝐢𝐧𝐠 𝐒𝐪𝐮𝐚𝐫𝐞 𝐕𝐞𝐧𝐭𝐮𝐫𝐞𝐬?
Balance-sheet investments in PS Ventures reached $80 million while cash dropped to $1 million and credit line debt hit $197 million. Investors need the timeline, fee rates and target outside capital for the vehicle.
𝐈𝐬 𝐭𝐡𝐞 𝟏𝟖.𝟗% 𝐭𝐚𝐱 𝐫𝐚𝐭𝐞 𝐨𝐧 𝐜𝐚𝐬𝐡 𝐩𝐫𝐨𝐟𝐢𝐭 𝐧𝐨𝐫𝐦𝐚𝐥?
The first corporate tax deduction in distributable earnings took $11.5 million, or 18.9% of pre-tax cash profit by our math. Management has not said whether year-end tax adjustments affected this initial rate.

$HUN Q3 2026 earnings: Huntsman raises chemical prices fast, while cash flow lags
Huntsman's chemical price increases are lifting profits ahead of its planned merger with Olin, even though cash flow trails last year. Revenue at the chemical maker rose 18% from a year ago, and profit before depreciation and one-offs (adjusted EBITDA) climbed 40% to $132 million, beating management's call for flat results from the second quarter. Chief executive Peter Huntsman kept his year-end target for net debt at about 4 times annual profit, down from 4.7 times today by our math.
• Revenue: $𝟏,𝟕𝟏𝟕𝐌 (+18% from a year ago)
• Adjusted EBITDA: $𝟏𝟑𝟐𝐌 (+40% from a year ago)
• Net debt to annual adjusted EBITDA: 𝟒.𝟕𝐱 (down from 5.4x in Q2 (by our math))
• Year-end debt leverage outlook: 𝐔𝐧𝐜𝐡𝐚𝐧𝐠𝐞𝐝 (target of ~4.0x by year-end)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🟢 Bullish
The story got better because price hikes in insulation chemicals sped up to 19% and specialty resin volumes jumped 12%, showing the profit recovery does not rely on temporary competitor outages. Shareholders also approved the Olin deal, and management narrowed the expected closing to the first quarter of 2027. One caution: nine-month free cash flow remains negative, and overhead expenses still have not fallen.
The question now is whether Huntsman can free up enough cash from working capital to hit its year-end debt target while capital spending nearly doubles in the fourth quarter. Either fourth-quarter working capital releases over $100 million as seasonal inventory unwinds, or debt stays stubbornly high heading into the merger close. Fourth-quarter cash flow and the conference call's profit outlook will settle it.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐈𝐧𝐬𝐮𝐥𝐚𝐭𝐢𝐨𝐧 𝐂𝐡𝐞𝐦𝐢𝐜𝐚𝐥 𝐏𝐫𝐢𝐜𝐞𝐬 𝐊𝐞𝐞𝐩 𝐑𝐢𝐬𝐢𝐧𝐠
Polyurethanes is Huntsman's largest division, making MDI, a key chemical for building insulation and foam. After falling for all of 2025, its prices turned positive last quarter. Bears worried that the rebound relied on temporary factory outages at rivals and that new US competitor capacity would cap prices.
Instead, price increases sped up in the third quarter. The chemical maker raised Polyurethanes selling prices by 19% from a year ago, nearly double last quarter's 10% pace, citing "improved supply and demand dynamics and higher raw materials costs". Sales volumes also rose 2%, lifting division operating profit before depreciation and one-offs (adjusted EBITDA) by 56% to $75 million.
This matters because higher prices are outrunning raw material inflation and carrying the company's earnings recovery before construction demand fully returns. What to watch: fourth-quarter Polyurethanes price changes, which will show whether these gains hold during the winter construction slowdown.
🟢 𝐒𝐩𝐞𝐜𝐢𝐚𝐥𝐭𝐲 𝐑𝐞𝐬𝐢𝐧𝐬 𝐆𝐫𝐨𝐰 𝐕𝐨𝐥𝐮𝐦𝐞 𝐛𝐲 𝟏𝟐%
Advanced Materials makes specialty epoxy resins and adhesives used in airplanes, cars and the electrical grid. It is the company's highest-margin business. In the third quarter, the division grew sales 18% from a year ago to $314 million, driven by a 12% jump in sales volume across "aerospace, automotive and power markets" and a 6% rise in prices from selling a richer mix of products.
Division adjusted EBITDA climbed 41% to $62 million. By our math, 37% of every new revenue dollar turned into profit, proving that volume growth in specialty markets is holding up beyond the strong second-quarter aerospace season. What to watch: fourth-quarter division profit, where any reading above last year's $36 million will confirm the growth is structural rather than seasonal.
🟢 𝐎𝐥𝐢𝐧 𝐌𝐞𝐫𝐠𝐞𝐫 𝐖𝐢𝐧𝐬 𝐕𝐨𝐭𝐞𝐬 𝐚𝐧𝐝 𝐒𝐞𝐭𝐬 𝐐𝟏 𝐂𝐥𝐨𝐬𝐞
In June, Huntsman agreed to an all-stock merger of equals with chlorine producer Olin Corporation to integrate raw materials and cut costs. The deal faced closing risks from shareholder votes and antitrust reviews. During the third quarter, shareholders approved the transaction on August 25, and regulators in the United States and several other countries cleared it.
Chief executive Peter Huntsman narrowed the expected closing window from the first half of 2027, saying the company is working on remaining approvals "which we now expect to close in the first quarter of 2027". That reduces the risk that the manufacturer is left alone with high debt. What to watch: final regulatory clearances in Europe and China before March 2027, which are the last hurdles to closing.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐂𝐚𝐬𝐡 𝐅𝐥𝐨𝐰 𝐒𝐭𝐢𝐥𝐥 𝐓𝐫𝐚𝐢𝐥𝐬 𝐋𝐚𝐬𝐭 𝐘𝐞𝐚𝐫
Huntsman needs cash to cut its debt before the merger closes. "Better results and cash flow are expected to reduce net debt leverage to approximately 4 times by year-end, a significant improvement from the beginning of the year," chief executive Peter Huntsman said. By our math, net debt sits at 4.7 times the last twelve months' adjusted EBITDA, down from 5.4 times in June.
• Third-quarter free cash flow: $82 million, down 48% from $157 million a year ago
• Nine-month free cash flow: negative $99 million, vs positive $105 million a year ago
• Borrowings against customer bills (accounts receivable programs): $235 million, up $83 million since December
The company cut net debt by $57 million this quarter, but working capital brought in only $12 million compared to $90 million a year ago, and it leaned further on short-term bill financing. What to watch: fourth-quarter cash from working capital, because reaching the 4 times target requires freeing up cash tied in inventory and customer bills while capital spending rises.
🔴 𝐎𝐯𝐞𝐫𝐡𝐞𝐚𝐝 𝐂𝐨𝐬𝐭𝐬 𝐒𝐭𝐢𝐥𝐥 𝐃𝐨 𝐍𝐨𝐭 𝐅𝐚𝐥𝐥
Huntsman has been running a restructuring programme to take out $100 million in annual costs and cited "cost savings achieved from our cost optimization program" for helping division profits. However, total company cost lines have not shrunk. Selling, general and administrative expenses (overhead and sales pay) rose $5 million from a year ago to $168 million, though faster sales growth reduced them by 1.4 percentage points of revenue to 9.8%.
Meanwhile, the cost of making the products (cost of goods sold) rose 0.2 percentage points of revenue to 86.2%, trimming gross margin to 13.8%. Inflation is eating the restructuring savings, so profit growth relies almost entirely on raising prices. What to watch: segment fixed costs in the quarterly filing, which will show if total factory and overhead costs finally drop below $400 million.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
Three standing concerns from last quarter could not be tested from the earnings release alone.
• European Polyurethanes profitability: management previously expected Europe to turn profitable on an adjusted EBITDA basis in the third quarter despite higher natural gas costs; the release says European volumes and prices rose, but only the conference call will confirm if the region made money.
• Segment fixed cost base: total adjusted fixed costs across divisions were $399 million last quarter; the quarterly filing's segment footnote will show whether cost cuts beat inflation.
• Olin merger chlorine savings timing: over $100 million of long-term merger savings wait on a third-party chlorine contract expiring at the end of 2030; the release gave no update on early capture.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐎𝐯𝐞𝐫𝐚𝐥𝐥 𝐕𝐨𝐥𝐮𝐦𝐞 𝐆𝐫𝐨𝐰𝐭𝐡 𝐑𝐞𝐦𝐚𝐢𝐧𝐬 𝐌𝐨𝐝𝐞𝐬𝐭
While chemical prices jumped 15% across Huntsman's divisions, overall sales volume grew only 3% from a year ago. In Performance Products, which makes amines and surfactants for construction, coatings and fuel additives, volume slipped 1% even as higher raw material and shipping costs pushed prices up 7%. Broad industrial and housing demand remains slow, leaving price increases to do most of the work.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐏𝐞𝐫𝐟𝐨𝐫𝐦𝐚𝐧𝐜𝐞 𝐏𝐫𝐨𝐝𝐮𝐜𝐭𝐬 𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀 (𝟐𝟔𝐐𝟑): $𝟑𝟏 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Profit before depreciation and one-offs in Performance Products rose 6.9% from a year ago, slowing from 15.6% growth in the second quarter. Revenue grew 5.7% to $260 million as a 7% price increase offset a 1% drop in sales volume. Higher prices covered rising raw material and shipping expenses.
𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐬 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞 𝐚𝐧𝐝 𝐢𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 (𝟐𝟔𝐐𝟑): $𝟏,𝟕𝟕𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Combined customer bills owed to Huntsman ($870 million) and inventory ($905 million) fell $40 million from June as the seasonal summer build began to unwind. However, the total remains up 10.7% from a year ago and up $280 million since December, which explains why nine-month operating cash flow is only $2 million.
𝐀𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐞𝐟𝐟𝐞𝐜𝐭𝐢𝐯𝐞 𝐭𝐚𝐱 𝐫𝐚𝐭𝐞 (𝟐𝟔𝐐𝟑): 𝟓𝟔% ⇘ decelerating
The tax rate excluding one-offs eased from 61% in the second quarter to 56%, though it stayed above last year's 40%. High tax rates in countries where the chemical group earns money, paired with losses where it cannot claim tax credits, took $25 million of its $45 million pre-tax profit.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟔 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐄𝐱𝐩𝐞𝐧𝐝𝐢𝐭𝐮𝐫𝐞𝐬: ~$𝟏𝟔𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠇 cut from ~$170 million
Cut. The manufacturer trimmed its full-year capital spending plan by $10 million, to about 7.5% below 2025 levels. It is the second trim this year after starting at $173 million. Having spent $101 million in the first nine months, the outlook leaves $59 million for the fourth quarter by our math, nearly double the third quarter's $33 million spend.
𝐘𝐞𝐚𝐫-𝐄𝐧𝐝 𝟐𝟎𝟐𝟔 𝐍𝐞𝐭 𝐃𝐞𝐛𝐭 𝐋𝐞𝐯𝐞𝐫𝐚𝐠𝐞: ~𝟒.𝟎𝐱 ⇘ decelerating
🠆 unchanged from ~4.0x
Unchanged. Chief executive Peter Huntsman kept the target for net debt at about 4 times annual adjusted EBITDA by December. By our math, the ratio dropped from 6.1 times in March and 5.4 times in June to 4.7 times in September. Hitting 4.0 times requires another fourth-quarter profit increase over last year's depressed $35 million and a year-end cash inflow.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐃𝐢𝐝 𝐄𝐮𝐫𝐨𝐩𝐞𝐚𝐧 𝐏𝐨𝐥𝐲𝐮𝐫𝐞𝐭𝐡𝐚𝐧𝐞𝐬 𝐭𝐮𝐫𝐧 𝐚 𝐩𝐫𝐨𝐟𝐢𝐭 𝐢𝐧 𝐐𝟑?
Last quarter management expected its European insulation business to reach positive adjusted EBITDA in the third quarter despite a spike in natural gas prices. The release notes higher European prices and volumes but gives no regional profit figure.
𝐖𝐡𝐚𝐭 𝐢𝐬 𝐭𝐡𝐞 𝐟𝐨𝐮𝐫𝐭𝐡-𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐚𝐝𝐣𝐮𝐬𝐭𝐞𝐝 𝐄𝐁𝐈𝐓𝐃𝐀 𝐨𝐮𝐭𝐥𝐨𝐨𝐤?
The earnings release did not include a fourth-quarter profit range, which management usually shares on the conference call. That number determines how much working capital cash Huntsman must release to hit its 4 times debt target.
𝐃𝐢𝐝 𝐬𝐞𝐠𝐦𝐞𝐧𝐭 𝐟𝐢𝐱𝐞𝐝 𝐜𝐨𝐬𝐭𝐬 𝐟𝐚𝐥𝐥 𝐛𝐞𝐥𝐨𝐰 $𝟒𝟎𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧?
Adjusted fixed costs across divisions were flat at $399 million last quarter despite a $110 million annual cost-saving programme. Investors need the quarterly filing's expense table to see if savings are finally beating inflation.
𝐖𝐡𝐲 𝐝𝐢𝐝 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞 𝐟𝐢𝐧𝐚𝐧𝐜𝐢𝐧𝐠 𝐫𝐢𝐬𝐞 𝐝𝐮𝐫𝐢𝐧𝐠 𝐚 𝐩𝐨𝐬𝐢𝐭𝐢𝐯𝐞 𝐜𝐚𝐬𝐡 𝐪𝐮𝐚𝐫𝐭𝐞𝐫?
Huntsman generated $82 million in free cash flow, yet borrowings under its accounts receivable programmes increased by $18 million to $235 million. Management has not explained why short-term bill financing keeps climbing.

$OGS Q3 2026 earnings: ONE Gas raises its profit outlook, while operating costs stabilize
ONE Gas, a natural gas utility in Oklahoma, Kansas and Texas, earned higher profit as regulator-approved rate increases took effect and operating costs stopped climbing. Third-quarter profit per share excluding one-offs grew 13%, while revenue after gas costs rose 5% by our math, above what the company's own plan pointed to. Chief executive Robert S. McAnnally raised the full-year outlook for a second time, though by our math the plan leaves per-share profit growth slowing to 2% in the fourth quarter.
• Revenue after gas costs: $𝟑𝟏𝟕.𝟓𝐌 (+5.0% from a year ago)
• Profit per share, excluding one-offs: $𝟎.𝟓𝟑 (+12.8% from a year ago)
• Operations and maintenance costs: $𝟏𝟑𝟕.𝟏𝐌 (-0.1% from a year ago)
• Full-year profit per share outlook: 𝐑𝐚𝐢𝐬𝐞𝐝 $𝟎.𝟎𝟔 (middle of the range: 11.2% growth)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🟢 Bullish
The story got better because day-to-day operating costs held steady after five quarters of overruns and regulators approved new rate increases across all three states. The utility also finished its 2026 bond sales and paid off a maturing loan. One caution: the new $29 million Oklahoma rate order was appealed to the state Supreme Court, and rising non-cash accounting credits did not stop operating cash flow from falling 5% over nine months.
The question now is whether fourth-quarter results keep operating cost growth below the 4% long-term target and protect the contested Oklahoma rates. If costs stay low and the court upholds the order, the higher rate base flows into 2027 profit; if costs rebound or the court forces a refund, earnings give back part of this year's gain. Fourth-quarter expenses and the upcoming 2027 plan will tell.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐍𝐞𝐰 𝐑𝐚𝐭𝐞 𝐀𝐩𝐩𝐫𝐨𝐯𝐚𝐥𝐬 𝐃𝐫𝐢𝐯𝐞 𝐭𝐡𝐞 𝐒𝐞𝐜𝐨𝐧𝐝 𝐎𝐮𝐭𝐥𝐨𝐨𝐤 𝐑𝐚𝐢𝐬𝐞
ONE Gas, a regulated natural gas utility in Oklahoma, Kansas and Texas, earns more when state regulators let it raise customer rates to pay for new pipes. Chief executive Robert S. McAnnally said the utility could "for the second time this year, raise our 2026 financial outlook" as he sees "diverse large-load demand" from big industrial and power users.
• Third-quarter revenue from new rates: up $13.5 million from a year ago ($57.2 million over nine months)
• Texas infrastructure rate increase: $36.9 million a year, in effect since July 2026
• Kansas reliability surcharge: $14.3 million a year, approved in September and in effect since October 2026
• Revenue after gas costs: $317.5 million, up 5.0% from a year ago by our math
Because the Kansas law expanded what projects qualify, that state's surcharge nearly doubled from last year's $7.2 million. These approved increases beat the utility's second-half pace by 3% by our math, so they carry the higher full-year plan even before new industrial projects add meaningful sales.
What to watch: the 2027 financial plan and five-year targets due with fourth-quarter results. A higher multi-year growth target would show that larger rate recoveries and industrial contracts are lifting long-term profit.
🟢 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐄𝐱𝐩𝐞𝐧𝐬𝐞𝐬 𝐒𝐭𝐨𝐩𝐩𝐞𝐝 𝐆𝐫𝐨𝐰𝐢𝐧𝐠 𝐢𝐧 𝐭𝐡𝐞 𝐓𝐡𝐢𝐫𝐝 𝐐𝐮𝐚𝐫𝐭𝐞𝐫
Operations and maintenance expense — the day-to-day cost of running and repairing gas lines — had grown faster than the utility's 3% to 4% long-term target for five straight quarters. Management promised that growth would step down in the second half as it brought pipeline monitoring work in-house.
In the third quarter, operations and maintenance costs were $137.1 million, down 0.1% from a year ago by our math and down 1.2 percentage points as a share of revenue. Employee costs rose only $1.0 million, so operating margin expanded 2.5 percentage points to 19.8%. One quarter does not settle a five-quarter overrun, because nine-month operating costs are still up 5.0%.
What to watch: fourth-quarter operations and maintenance expense. Another quarter below 4% growth from a year ago would confirm that bringing contractors' work in-house is holding costs down.
🟢 𝐃𝐞𝐛𝐭 𝐈𝐬𝐬𝐮𝐚𝐧𝐜𝐞 𝐂𝐨𝐦𝐩𝐥𝐞𝐭𝐞𝐬 𝐭𝐡𝐞 𝟐𝟎𝟐𝟔 𝐅𝐢𝐧𝐚𝐧𝐜𝐢𝐧𝐠 𝐏𝐥𝐚𝐧
Entering the quarter, ONE Gas carried about $1 billion in short-term debt exposed to floating interest rates, including a $250 million loan due in September. "Our 2026 financing plan is complete," McAnnally said, after the utility issued $375 million of 5.45% ten-year notes in August and paid off the maturing loan.
The refinancing locked in long-term funding, but it raised third-quarter net interest expense (excluding Kansas securitized bonds) by $1.6 million. The utility still holds $789.8 million in short-term notes payable on its balance sheet, up from $737.4 million in December, so short-term rate exposure has eased rather than disappeared.
What to watch: net interest expense and short-term notes payable at year-end. A drop in short-term borrowings would limit the drag from the 5.45% bond coupon.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐎𝐤𝐥𝐚𝐡𝐨𝐦𝐚 𝐑𝐚𝐭𝐞 𝐈𝐧𝐜𝐫𝐞𝐚𝐬𝐞 𝐅𝐚𝐜𝐞𝐬 𝐚 𝐒𝐮𝐩𝐫𝐞𝐦𝐞 𝐂𝐨𝐮𝐫𝐭 𝐀𝐩𝐩𝐞𝐚𝐥
Oklahoma Natural Gas, the company's largest division, filed in February for a $28.7 million annual base rate increase under its yearly performance-based rate rule. The utility began collecting those higher rates on an interim basis in late June.
On October 14, the Oklahoma Corporation Commission approved the request, but ONE Gas disclosed that "That order has been since appealed to the Oklahoma Supreme Court." Because "Interim rates subject to refund were implemented on June 26, 2026," every dollar collected under the new Oklahoma tariff remains at legal risk. That $28.7 million increase is more than one-third of all new rate money approved across its three states this year.
What to watch: filings and rulings at the Oklahoma Supreme Court on the October rate order. An adverse ruling would force ONE Gas to refund the interim revenue it has booked since June.
🔴 𝐍𝐨𝐧-𝐂𝐚𝐬𝐡 𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐢𝐧𝐠 𝐂𝐫𝐞𝐝𝐢𝐭𝐬 𝐎𝐮𝐭𝐩𝐚𝐜𝐞 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐂𝐚𝐬𝐡 𝐅𝐥𝐨𝐰
Since late last year, ONE Gas has steered investors to profit excluding one-offs, which adds back deferred carrying costs — an accounting credit under Texas House Bill 4384 for returns on new Texas pipes before customers start paying for them. Management says this measure gives a fuller view of its regulated economics.
• Nine-month profit excluding one-offs: up $37.6 million from a year ago, to $218.9 million
• Nine-month Texas accounting credit: $12.2 million, up from $3.4 million a year ago (full-year plan: $15.7 million)
• Total regulatory assets on the balance sheet: $384.4 million, up 25.7% since December by our math
• Nine-month operating cash flow: $507.8 million, down 5.2% from a year ago by our math
The accounting credit is non-cash until future rate filings put it onto customer bills, so cash from operations fell $28.0 million even as reported profit climbed. Meanwhile, the release gave no update on when industrial projects start paying cash or on pending federal safety rules.
What to watch: full-year operating cash flow against the $15.7 million full-year accounting credit. A wider gap would mean the utility must borrow more to fund its $800 million construction budget.
🔴 𝐍𝐞𝐰 𝐒𝐡𝐚𝐫𝐞𝐬 𝐂𝐮𝐭 𝐎𝐧𝐞-𝐓𝐡𝐢𝐫𝐝 𝐨𝐟 𝐏𝐞𝐫-𝐒𝐡𝐚𝐫𝐞 𝐏𝐫𝐨𝐟𝐢𝐭 𝐆𝐫𝐨𝐰𝐭𝐡
Because ONE Gas spends more on pipeline construction and dividends than it generates in operating cash, it sells new common stock to keep its balance sheet balanced. Those share sales spread the utility's profit across more owners.
In the third quarter, diluted shares rose 4.3% from a year ago to 63.2 million, after the company settled forward share contracts in December. As a result, third-quarter profit excluding one-offs rose 17.2% to $33.5 million, but profit per share rose only 12.8% to $0.53. The full-year plan expects 63.25 million diluted shares, so dilution will keep trimming per-share growth by about 4 percentage points.
What to watch: fourth-quarter settlement of remaining forward share sales and any new stock offerings for 2027. Issuing more shares will keep per-share profit growth behind total profit growth.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐂𝐡𝐞𝐚𝐩𝐞𝐫 𝐍𝐚𝐭𝐮𝐫𝐚𝐥 𝐆𝐚𝐬 𝐊𝐞𝐞𝐩𝐬 𝐂𝐮𝐬𝐭𝐨𝐦𝐞𝐫 𝐁𝐢𝐥𝐥𝐬 𝐒𝐭𝐞𝐚𝐝𝐲
ONE Gas passes the wholesale cost of natural gas directly to its customers without a markup, and weather rules smooth out warm winters. Nine-month weather was 23% warmer than normal, so the cost of gas fell 21% to $557.7 million. That savings offset the $57.2 million of rate increases, letting McAnnally say "we expect our average 2026 customer bills to remain flat to last year."
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐞𝐱𝐩𝐞𝐧𝐝𝐢𝐭𝐮𝐫𝐞𝐬 𝐚𝐧𝐝 𝐚𝐬𝐬𝐞𝐭 𝐫𝐞𝐦𝐨𝐯𝐚𝐥 (𝟐𝟔𝐐𝟑): $𝟐𝟐𝟗.𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Spending on pipeline safety and new customer hookups rose 10.3% from a year ago in the third quarter, after dipping 4.6% in the first quarter and 0.9% in the second. Nine-month capital spending reached $586.9 million, up 2.0% from last year, which leaves $213.1 million for the fourth quarter to hit the $800 million annual budget.
𝐀𝐯𝐞𝐫𝐚𝐠𝐞 𝐭𝐨𝐭𝐚𝐥 𝐜𝐮𝐬𝐭𝐨𝐦𝐞𝐫𝐬 (𝟐𝟔𝐐𝟑): 𝟐,𝟐𝟗𝟓 𝐭𝐡𝐨𝐮𝐬𝐚𝐧𝐝 ⇒ stable
The utility added 11,000 average customers from a year ago, a 0.5% increase that matches the pace of the past three quarters. Texas added 6,000 customers, Kansas added 3,000 and Oklahoma added 2,000, lifting third-quarter residential sales revenue by $3.3 million.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟔 𝐏𝐫𝐨𝐟𝐢𝐭 𝐩𝐞𝐫 𝐬𝐡𝐚𝐫𝐞, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: $𝟒.𝟗𝟓–𝟓.𝟎𝟏 ⇘ decelerating
🠅 raised from $4.89–4.95
Raised. The middle of the full-year range moved up $0.06 to $4.98, or 11.2% growth from last year. By our math, that leaves $1.51 for the fourth quarter, or 2.0% growth vs 12.8% in the third quarter, because Texas accounting credits are smaller in the fourth quarter and share count is 4.5% higher. This is the second raise this year: +$0.03 in Q2, +$0.06 in Q3.
𝐅𝐘𝟐𝟔 𝐍𝐞𝐭 𝐢𝐧𝐜𝐨𝐦𝐞, 𝐞𝐱𝐜𝐥𝐮𝐝𝐢𝐧𝐠 𝐨𝐧𝐞-𝐨𝐟𝐟𝐬: $𝟑𝟏𝟑–𝟑𝟏𝟕 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠅 raised from $310–314 million
Raised. Management lifted the middle of the range by $3 million to $315 million, which is 16.2% growth for the year. By our math, that implies $96.1 million in the fourth quarter, up 7.1% from a year ago vs 17.2% in the third quarter. It is the second raise this year: +$2M in Q2, +$3M in Q3.
𝐅𝐘𝟐𝟔 𝐆𝐀𝐀𝐏 𝐩𝐫𝐨𝐟𝐢𝐭 𝐩𝐞𝐫 𝐬𝐡𝐚𝐫𝐞: $𝟒.𝟕𝟎–𝟒.𝟕𝟔 ⇘ decelerating
🠅 raised from $4.65–4.77
Raised. ONE Gas narrowed the range and lifted the middle by $0.02 to $4.73, or 8.2% growth for the year. By our math, that leaves $1.46 for the fourth quarter, up 2.8% from a year ago vs 11.4% in the third quarter. The $0.02 GAAP raise is smaller than the $0.06 raise excluding one-offs because Texas accounting credits rose faster than previously planned.
𝐅𝐘𝟐𝟔 𝐆𝐀𝐀𝐏 𝐧𝐞𝐭 𝐢𝐧𝐜𝐨𝐦𝐞: $𝟐𝟗𝟕.𝟓–𝟑𝟎𝟏.𝟏 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
🠅 raised from $294–302 million
Raised. The middle of the range rose $1.3 million to $299.3 million, or 13.3% growth from 2025. By our math, that leaves $92.6 million for the fourth quarter, up 7.3% from a year ago vs 18.0% in the third quarter.
𝐅𝐘𝟐𝟔 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐢𝐧𝐯𝐞𝐬𝐭𝐦𝐞𝐧𝐭𝐬: ~$𝟖𝟎𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠆 unchanged from ~$800 million
Unchanged. The utility still plans to spend about $800 million on pipeline replacements and expansions, with $230 million of that going to connect new customers. By our math, that leaves $213.1 million for the fourth quarter, up 15.8% from a year ago after 10.3% growth in the third quarter.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐨 𝐚𝐩𝐩𝐞𝐚𝐥𝐞𝐝 𝐭𝐡𝐞 𝐎𝐤𝐥𝐚𝐡𝐨𝐦𝐚 𝐫𝐚𝐭𝐞 𝐨𝐫𝐝𝐞𝐫 𝐚𝐧𝐝 𝐰𝐡𝐲?
The Oklahoma Corporation Commission approved the $28.7 million rate increase on October 14, and an appeal went to the Oklahoma Supreme Court. Investors need to know which provisions are contested and whether any revenue is reserved for refund.
𝐖𝐞𝐫𝐞 𝐭𝐡𝐞 𝐭𝐰𝐨 𝐢𝐧𝐝𝐮𝐬𝐭𝐫𝐢𝐚𝐥 𝐩𝐫𝐨𝐣𝐞𝐜𝐭𝐬 𝐩𝐥𝐚𝐜𝐞𝐝 𝐢𝐧 𝐬𝐞𝐫𝐯𝐢𝐜𝐞?
Last quarter, management said the El Paso manufacturing project and the Oklahoma data center project would go into service in the third quarter. The earnings release did not mention whether either project is now operating.
𝐇𝐚𝐯𝐞 𝐚𝐧𝐲 𝐥𝐚𝐭𝐞-𝐬𝐭𝐚𝐠𝐞 𝐢𝐧𝐝𝐮𝐬𝐭𝐫𝐢𝐚𝐥 𝐩𝐫𝐨𝐣𝐞𝐜𝐭𝐬 𝐬𝐢𝐠𝐧𝐞𝐝 𝐜𝐨𝐧𝐭𝐫𝐚𝐜𝐭𝐬?
The utility had five late-stage power and industrial projects in its pipeline last quarter and said some could sign before year-end. Converting them into signed contracts is key to the upcoming five-year capital plan.
𝐖𝐡𝐲 𝐝𝐢𝐝 𝐟𝐮𝐥𝐥-𝐲𝐞𝐚𝐫 𝐓𝐞𝐱𝐚𝐬 𝐚𝐜𝐜𝐨𝐮𝐧𝐭𝐢𝐧𝐠 𝐜𝐫𝐞𝐝𝐢𝐭𝐬 𝐣𝐮𝐦𝐩 𝐭𝐨 $𝟏𝟓.𝟕𝐌?
Management initially estimated about $12 million of non-GAAP Texas carrying-cost credits for 2026, but the new outlook table shows $15.7 million at the middle of the range even as eligible third-quarter plant additions fell.

$AAPL Q4 2026 earnings: Apple's phone sales beat its plan, but underlying margins slip
Apple sold more phones and laptops than its supply-constrained plan called for, while rising memory costs and research spending squeezed underlying profit margins. Fourth-quarter revenue rose 12% to $114.5 billion, beating the 9% to 11% outlook as chief executive John Ternus launched the iPhone Duo and touch-screen Macs. However, excluding a 1 percentage point boost from customs tariff refunds, gross margin fell 1.2 points from last quarter to 46.9% by our math.
• Revenue: $𝟏𝟏𝟒.𝟓𝐁 (+12% from a year ago (planned 9–11%))
• Gross margin excluding tariff refunds: 𝟒𝟔.𝟗% (-1.2 percentage points from last quarter by our math)
• iPhone revenue: $𝟓𝟕.𝟔𝐁 (+17.5% from a year ago (planned mid-teens))
• Quarterly dividend outlook: 𝐔𝐧𝐜𝐡𝐚𝐧𝐠𝐞𝐝 ($0.27 per share; Q1 sales plan awaits the call)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: ⚪ Neutral
The story is unchanged because strong hardware demand and worsening component inflation offset each other, and the release contains no holiday-quarter outlook. Beating the September sales plan shows the prior forecast was cautious, while Services growth slowed below 10% and operating margin dipped as artificial-intelligence engineering costs rose 32%.
The question now is whether buyers will pay enough for new hardware to cover soaring memory-chip prices once Apple uses up its older component stockpiles. Either the iPhone Duo and touch-screen Macs lift prices and margins, or memory inflation and slower Services growth push profitability down in fiscal 2027. The December-quarter gross margin outlook on the conference call and the inventory footnote in the annual report will tell.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐢𝐏𝐡𝐨𝐧𝐞 𝐚𝐧𝐝 𝐂𝐡𝐢𝐧𝐚 𝐂𝐚𝐫𝐫𝐢𝐞𝐝 𝐭𝐡𝐞 𝐐𝐮𝐚𝐫𝐭𝐞𝐫 𝐏𝐚𝐬𝐭 𝐒𝐮𝐩𝐩𝐥𝐲 𝐋𝐢𝐦𝐢𝐭𝐬
Three months ago Apple warned that chip shortages would cap September sales and hold total growth to between 9% and 11%. Instead, chief executive John Ternus introduced the iPhone Duo, calling it the "most transformational iPhone since the original", alongside the iPhone 18 Pro lineup, and total revenue rose 11.7% to $114.5 billion.
• iPhone sales: $57.6 billion, up 17.5% from a year ago against a mid-teens plan
• Greater China sales: $17.5 billion, up 21.0% after falling 3.6% a year ago
• iPad and Wearables sales: down 10.4% and 7.9%, absorbing the chip shortage
The numbers show that the consumer tech giant prioritised its flagship phones and Asian buyers when allocating scarce processor chips. Beating the outlook proves the previous forecast was cautious, but it does not prove the chip shortage is over because iPad and accessory sales shrank.
What to watch: holiday-quarter revenue outlook on the conference call. A growth target in the double digits against last year's 16% iPhone 17 jump would show that supply can now meet demand.
🟢 𝐌𝐚𝐜 𝐆𝐫𝐞𝐰 𝟐𝟒% 𝐀𝐠𝐚𝐢𝐧𝐬𝐭 𝐚 𝐓𝐨𝐮𝐠𝐡 𝐂𝐨𝐦𝐩𝐚𝐫𝐢𝐬𝐨𝐧 𝐚𝐧𝐝 𝐇𝐢𝐠𝐡𝐞𝐫 𝐏𝐫𝐢𝐜𝐞𝐬
Apple raised prices on Mac and iPad last quarter to offset dearer memory chips, leaving open whether buyers would balk or had merely bought early ahead of the hike. In the fourth quarter, Ternus said the group "brought Touch to Mac for the first time", and Mac revenue rose 23.7% to $10.8 billion on top of 12.7% growth a year ago.
That result rules out a one-quarter pull-forward on laptops, whereas iPad sales fell 10.4% to $6.2 billion under the same price rises and supply limits. Customers paid more for Macs with touchscreen features and on-device artificial intelligence, while tablet buyers waited.
What to watch: December-quarter Mac sales against last year's 6.7% drop. Sustained double-digit growth during the holiday season would confirm that corporate and touch-screen upgrades outweigh higher prices.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐌𝐞𝐦𝐨𝐫𝐲 𝐂𝐨𝐬𝐭𝐬 𝐚𝐧𝐝 𝐀𝐈 𝐒𝐩𝐞𝐧𝐝𝐢𝐧𝐠 𝐒𝐪𝐮𝐞𝐞𝐳𝐞𝐝 𝐎𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐌𝐚𝐫𝐠𝐢𝐧
Finance chief Kevan Parekh highlighted September records for net income and earnings per share, and reported gross margin rose 0.7 percentage points from a year ago to 47.9%. However, the release notes this included a "favorable impact of approximately 1 percentage point from tariff refunds" worth $0.05 per share, down from 2 points and $0.11 last quarter.
• Gross margin excluding tariff refunds: 46.9% by our math, down 1.2 percentage points from last quarter and 0.3 points from a year ago
• Research and development (engineering and AI costs): 10.2% of revenue, up 1.6 percentage points from a year ago
• Operating margin: 31.1%, down 0.5 percentage points from a year ago
Stripping out the temporary customs refunds shows that rising memory-chip prices are already hurting hardware profitability. At the same time, research spending rose 32.3% to $11.7 billion, so operating profit grew slower than sales and a lower 15.0% tax rate provided $0.04 of the earnings beat.
What to watch: first-quarter gross margin outlook on the call. A target below 47% without tariff refunds would show that older, cheaper component stockpiles are running out while memory prices keep rising.
🔴 𝐒𝐞𝐫𝐯𝐢𝐜𝐞𝐬 𝐆𝐫𝐨𝐰𝐭𝐡 𝐃𝐫𝐨𝐩𝐩𝐞𝐝 𝐁𝐞𝐥𝐨𝐰 𝟏𝟎% 𝐚𝐬 𝐃𝐞𝐟𝐞𝐫𝐫𝐞𝐝 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐋𝐚𝐠𝐠𝐞𝐝
Services — which includes the App Store, iCloud storage, search licensing and Apple TV — carries a 76.0% gross margin, roughly double the 37.2% margin on hardware devices. Parekh noted that Services revenue reached an all-time high of $31.6 billion and that the "installed base of active devices reached a new all-time high across all major product categories and geographic segments".
Even so, Services growth slowed to 9.8% from a year ago, down from 12.1% last quarter and 15.1% a year earlier. Current deferred revenue — cash collected from customers for subscriptions and services not yet delivered — rose only 6.4% to $9.6 billion, trailing both hardware and software sales.
Because Services grew slower than Products (up 12.5%), its share of total revenue dipped to 27.6% from 28.1% a year ago, depriving the group of its usual margin boost. Currency swings explain part of the slowdown, but slower growth in upfront subscription balances points to softer App Store and gaming spending.
What to watch: total deferred revenue in Note 2 of the annual report (Form 10-K). Growth staying in the single digits would mean new Siri AI features are not yet lifting paid iCloud subscriptions.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
The earnings release consists only of financial tables and brief quotes, leaving four standing risks and commitments without an update until the conference call and annual report.
• Component inventory buffer: total inventory jumped 31.1% from last quarter to $14.5 billion, and Note 5 of the 10-K will show whether raw memory stockpiles rose above June's $7.6 billion or shifted into finished phones.
• AI licensing and intangibles: net intangible assets (acquired rights and licences) stayed high at $20.3 billion, up 82.8% from a year ago, and the 10-K footnotes will test whether this reflects capitalised third-party AI model deals.
• Siri AI in Europe and China: the release mentions the all-new Siri AI for the holiday season without stating whether regulators in the European Union and China have approved it.
• US manufacturing commitment: no update on the $600 billion four-year US spending plan or when the Houston facility will begin assembling Mac mini computers.
👓 𝐎𝐭𝐡𝐞𝐫 𝐓𝐡𝐞𝐦𝐞𝐬
𝐍𝐞𝐰 𝐇𝐚𝐫𝐝𝐰𝐚𝐫𝐞 𝐂𝐚𝐭𝐞𝐠𝐨𝐫𝐢𝐞𝐬 𝐌𝐚𝐫𝐤 𝐉𝐨𝐡𝐧 𝐓𝐞𝐫𝐧𝐮𝐬'𝐬 𝐅𝐢𝐫𝐬𝐭 𝐐𝐮𝐚𝐫𝐭𝐞𝐫
September was the first reporting period under chief executive John Ternus, who succeeded Tim Cook on September 1. Ternus highlighted "a whole new generation of hardware for the home" alongside the iPhone Duo and touch-screen Macs. None of these new lines are broken out separately in the category table yet, where Wearables, Home and Accessories fell 7.9% to $8.3 billion.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐓𝐨𝐭𝐚𝐥 𝐢𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐢𝐞𝐬 (𝟐𝟔𝐐𝟒): $𝟏𝟒,𝟓𝟒𝟏 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Stockpiles on the balance sheet rose 154.3% from a year ago and 31.1% ($3.4 billion) from the June quarter. In the first nine months of the year, Apple built up raw components to shield margins from memory-chip inflation; the jump at year-end also reflects finished iPhone 18 and iPhone Duo units shipping for the holiday quarter.
𝐂𝐚𝐩𝐢𝐭𝐚𝐥 𝐞𝐱𝐩𝐞𝐧𝐝𝐢𝐭𝐮𝐫𝐞𝐬 (𝐅𝐘𝟐𝟔): $𝟗,𝟎𝟒𝟏 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Payments for property, plant and equipment fell 28.9% in fiscal 2026 to 1.9% of revenue, and dropped 30.9% in the fourth quarter to $2.2 billion by our math. While factory and data-centre spending shrank, net intangible assets on the balance sheet rose 82.8% over the year to $20.3 billion, reflecting off-balance-sheet or licensed capacity.
𝐒𝐡𝐚𝐫𝐞 𝐫𝐞𝐩𝐮𝐫𝐜𝐡𝐚𝐬𝐞𝐬 (𝐅𝐘𝟐𝟔): $𝟖𝟔,𝟑𝟗𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
The iPhone maker spent $24.3 billion buying back its own shares in the fourth quarter by our math, bringing full-year repurchases to $86.4 billion, down 4.8% from fiscal 2025. Combined with $12.4 billion of term-debt repayments, buybacks lowered the diluted share count by 1.6% from a year ago to 14.63 billion.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐐𝟏 𝐂𝐚𝐬𝐡 𝐝𝐢𝐯𝐢𝐝𝐞𝐧𝐝: $𝟎.𝟐𝟕 𝐩𝐞𝐫 𝐬𝐡𝐚𝐫𝐞 ⇒ stable
🠆 unchanged from $0.27 per share
Unchanged. The board declared a quarterly cash dividend of $0.27 per share, payable on November 16, matching the rate set after the 4% increase in the second quarter. Apple does not include revenue or margin targets in its press release, reserving its holiday-quarter financial outlook for the conference call.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐖𝐡𝐚𝐭 𝐢𝐬 𝐭𝐡𝐞 𝐡𝐨𝐥𝐢𝐝𝐚𝐲-𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐨𝐮𝐭𝐥𝐨𝐨𝐤 𝐟𝐨𝐫 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐚𝐧𝐝 𝐠𝐫𝐨𝐬𝐬 𝐦𝐚𝐫𝐠𝐢𝐧?
Apple gives its quarterly targets on the earnings call rather than in the release. Investors need the December gross-margin range to see how fast rising memory costs are hitting profits as tariff refunds fade.
𝐃𝐢𝐝 𝐭𝐡𝐞 $𝟏𝟒.𝟓 𝐛𝐢𝐥𝐥𝐢𝐨𝐧 𝐢𝐧𝐯𝐞𝐧𝐭𝐨𝐫𝐲 𝐛𝐮𝐢𝐥𝐝 𝐠𝐨 𝐢𝐧𝐭𝐨 𝐜𝐨𝐦𝐩𝐨𝐧𝐞𝐧𝐭𝐬 𝐨𝐫 𝐟𝐢𝐧𝐢𝐬𝐡𝐞𝐝 𝐩𝐡𝐨𝐧𝐞𝐬?
Total inventory jumped $3.4 billion in the quarter and $8.8 billion over the year. Only the Note 5 breakdown in the 10-K will show whether the pre-inflation memory buffer is shrinking or growing.
𝐖𝐡𝐚𝐭 𝐜𝐚𝐮𝐬𝐞𝐝 𝐧𝐞𝐭 𝐢𝐧𝐭𝐚𝐧𝐠𝐢𝐛𝐥𝐞 𝐚𝐬𝐬𝐞𝐭𝐬 𝐭𝐨 𝐧𝐞𝐚𝐫𝐥𝐲 𝐝𝐨𝐮𝐛𝐥𝐞 𝐭𝐨 $𝟐𝟎.𝟑 𝐛𝐢𝐥𝐥𝐢𝐨𝐧?
Net intangibles rose $9.2 billion over fiscal 2026 while capital expenditures fell 29%. Management has not said whether this balance capitalises third-party AI model licensing such as the Google partnership.
𝐖𝐡𝐞𝐧 𝐰𝐢𝐥𝐥 𝐒𝐢𝐫𝐢 𝐀𝐈 𝐥𝐚𝐮𝐧𝐜𝐡 𝐢𝐧 𝐭𝐡𝐞 𝐄𝐮𝐫𝐨𝐩𝐞𝐚𝐧 𝐔𝐧𝐢𝐨𝐧 𝐚𝐧𝐝 𝐂𝐡𝐢𝐧𝐚?
Chief executive John Ternus touted the all-new Siri AI for the holiday season, but Europe and Greater China represent 43% of sales and faced regulatory blocks last quarter.

$MSA Q3 2026 earnings: MSA Safety underlying sales double, but acquisition costs cut profit
MSA Safety, a maker of firefighter breathing gear, gas detectors and hard hats, revived its underlying sales growth while acquisition bills and factory costs squeezed profit margins. Sales from businesses owned a year ago rose 6%, twice the first-half pace, as delayed US firefighter grants finally turned into shipments. Closing the $563 million purchase of Norwegian fire-safety firm Autronica lifted total sales faster, yet deal fees, higher interest expenses and costlier materials cut net profit.
• Sales from businesses owned a year ago: +𝟔% (up from +3% in Q2)
• Total revenue: $𝟓𝟑𝟔.𝟒𝐌 (+15% from a year ago)
• Profit per share, excluding one-offs: $𝟐.𝟎𝟗 (+8% from a year ago)
• Full-year revenue outlook: 𝐔𝐧𝐜𝐡𝐚𝐧𝐠𝐞𝐝 (low-double-digit total growth (~11%))
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🟢 Bullish
The story got better because the four-quarter logjam in firefighter equipment orders finally broke. A 9% underlying rebound in Fire Service puts the second-half sales step-up on track without relying solely on European military helmets. One caution: operating margin excluding one-offs slipped 0.7 percentage points as Middle East supply-chain inflation flowed through inventory, and finance chief Julie Beck reaffirmed the total sales outlook without mentioning the underlying sales target.
The question now is whether third-quarter Fire Service shipments mark the start of a multi-year replacement cycle or just a one-time catch-up on delayed 2025 government grants. If a broader replacement wave has started, underlying growth stays above 5%; if it was only backlog clearance, growth slows once those grants ship. Fourth-quarter Fire Service orders and underlying sales will tell.
Full article with charts - link in bio
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐅𝐢𝐫𝐞𝐟𝐢𝐠𝐡𝐭𝐞𝐫 𝐆𝐞𝐚𝐫 𝐑𝐞𝐛𝐨𝐮𝐧𝐝𝐬 𝐚𝐧𝐝 𝐋𝐢𝐟𝐭𝐬 𝐔𝐧𝐝𝐞𝐫𝐥𝐲𝐢𝐧𝐠 𝐒𝐚𝐥𝐞𝐬
For four quarters, MSA Safety blamed weak firefighter equipment sales on delayed US government grants and slow safety-standard approvals. Those delays held sales from businesses it owned a year ago to 3% growth in the first half. In the third quarter, the logjam broke and underlying sales rose 6%, doubling the first-half pace. The company also continued "launching the G1 City Edition SCBA", its breathing apparatus for firefighters.
• Fire Service underlying sales: up 9% from a year ago, after falling 2% in Q2 and 21% in Q4
• Americas Fire Service underlying sales: up 9%, rebounding from a 3% decline last quarter
• International Fire Service underlying sales: up 10%, compared with flat results in Q2
The rebound matters because the full-year plan needed second-half underlying sales growth of about 5% to 9% by our math. Reaching 6% in Q3 puts the safety equipment maker back on track, though one quarter only fades the delay concern because chief financial officer Julie Beck did not explicitly repeat the full-year underlying sales target in the release.
What to watch: fourth-quarter Fire Service underlying sales. Another gain against last year's 21% drop would confirm that delayed US firefighter grants have finally turned into steady shipments.
🟢 𝐇𝐚𝐫𝐝 𝐇𝐚𝐭𝐬 𝐚𝐧𝐝 𝐅𝐚𝐥𝐥 𝐆𝐞𝐚𝐫 𝐊𝐞𝐞𝐩 𝐆𝐫𝐨𝐰𝐢𝐧𝐠
Investors worried that a second-quarter jump in Industrial PPE — hard hats, fall-protection harnesses and ballistic helmets — was a one-off wave of European military orders. In the third quarter, the division's underlying sales grew 7% from a year ago to $129.3 million, even against a 7% gain in the prior year.
Furthermore, the growth shifted back to North America. Americas Industrial PPE underlying sales rose 9%, while International slowed from 27% in Q2 to 3% in Q3. Because US industrial demand carried the division when overseas helmet shipments cooled, the recovery looks broader than a single defense contract.
What to watch: Americas Industrial PPE underlying growth in the fourth quarter. Holding above 5% would show that everyday factory and construction demand is strong enough to replace lumpy military orders.
🟢 𝐀𝐮𝐭𝐫𝐨𝐧𝐢𝐜𝐚 𝐋𝐢𝐟𝐭𝐬 𝐈𝐧𝐭𝐞𝐫𝐧𝐚𝐭𝐢𝐨𝐧𝐚𝐥 𝐒𝐚𝐥𝐞𝐬 𝐚𝐧𝐝 𝐇𝐨𝐥𝐝𝐬 𝐌𝐚𝐫𝐠𝐢𝐧𝐬
MSA Safety is reshaping itself around gas and flame detection through acquisitions and connected hardware. In July it spent $563 million to close the purchase of Autronica Fire and Security, a Norwegian maker of fire and gas safety systems. While the deal's $555 million price tag and lower initial profit margins raised dilution concerns, the first quarter of ownership went smoothly.
Acquisitions added 20 percentage points to Detection growth — about $38 million of sales by our math — and lifted International revenue 28% to $198.2 million. Even with Autronica folded in, International operating margin excluding one-offs rose 0.1 percentage points to 16.1%. Chief executive Steve Blanco also noted "an ALTAIR io 6 order that marked our largest MSA+ order to date" for its subscription-linked portable gas detectors.
What to watch: the third-quarter 10-Q acquisition footnote and call remarks. They will show Autronica's exact sales contribution, whether cost savings have started, and whether connected MSA+ devices stayed above 14% of portable sales.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐇𝐢𝐠𝐡𝐞𝐫 𝐅𝐚𝐜𝐭𝐨𝐫𝐲 𝐚𝐧𝐝 𝐎𝐯𝐞𝐫𝐡𝐞𝐚𝐝 𝐂𝐨𝐬𝐭𝐬 𝐂𝐮𝐭 𝐌𝐚𝐫𝐠𝐢𝐧𝐬
"The MSA team continued to advance our Accelerate strategy in the third quarter, delivering 15% sales growth," chief executive Steve Blanco said. Yet that top-line expansion did not lift profitability, ending a multi-quarter streak of margin gains as both factory costs and deal bills rose.
• Operating margin: down 3.7 percentage points from a year ago to 16.4%
• Operating margin excluding one-offs: down 0.7 percentage points to 21.4%, after rising 2.7 points in Q2
• Cost of making products: up 0.9 percentage points of sales to 54.5%
• Selling and administrative overhead: up 2.7 percentage points of sales to 24.7%, driven by $15.0 million in deal and digital fees
Even stripping out acquisition write-offs, gross margin fell by our math to 47.0% from 50.2% in Q2. That drop shows that shipping delays and raw-material inflation from the Middle East conflict, which sat in inventory during the spring, are now flowing through the income statement.
What to watch: fourth-quarter gross margin excluding acquisition write-offs. A drop below 46.2% would mean input-cost inflation and Autronica's mix are hurting profitability more than the full-year plan allowed.
🔴 𝐈𝐧𝐭𝐞𝐫𝐧𝐚𝐭𝐢𝐨𝐧𝐚𝐥 𝐆𝐚𝐬 𝐃𝐞𝐭𝐞𝐜𝐭𝐢𝐨𝐧 𝐊𝐞𝐞𝐩𝐬 𝐒𝐡𝐫𝐢𝐧𝐤𝐢𝐧𝐠 𝐖𝐢𝐭𝐡𝐨𝐮𝐭 𝐀𝐜𝐪𝐮𝐢𝐬𝐢𝐭𝐢𝐨𝐧𝐬
Headline Detection sales jumped 22% to $233.9 million, making gas and flame detectors 44% of the company. That number includes both Autronica and one month of M&C TechGroup, a German equipment maker bought in May 2025. Stripping out acquisitions and currency shifts, total Detection sales grew only 2%.
The weak spot remains overseas. International Detection underlying sales fell 4% in the third quarter and are down 10% over the first nine months, hurt by slower European economic growth and Middle East project delays. Because M&C TechGroup entered the underlying sales calculation in May, even that 2% consolidated gain had help from last year's deal.
What to watch: International Detection underlying sales in the fourth quarter. A fourth straight quarterly drop would show that overseas industrial and energy customers are still holding back on gas-monitoring projects.
🔴 𝐍𝐞𝐰 𝐃𝐞𝐛𝐭 𝐚𝐧𝐝 𝐃𝐞𝐚𝐥 𝐁𝐢𝐥𝐥𝐬 𝐂𝐮𝐭 𝐂𝐚𝐬𝐡
"With net leverage within our target range, we remain well positioned to pursue strategic growth opportunities," finance chief Julie Beck said. Borrowing to buy Autronica pushed total debt above $1.12 billion and lifted net debt to $934.0 million, or 1.7 times annual cash profit (Adjusted EBITDA). That higher debt load is already taking a larger share of quarterly earnings and cash.
Quarterly interest expense jumped 63% from a year ago to $13.8 million, while free cash flow fell 32% to $68.2 million as working capital provided less cash and capital spending rose. Consequently, the manufacturer cut share buybacks in half from last quarter to $12.7 million. Two other balance-sheet risks — electronics inventory buffers and 1,222 Globe firefighter-gear chemical lawsuits — await the 10-Q filing for new numbers.
What to watch: fourth-quarter interest expense and debt repayment. If interest costs top $13.5 million next quarter, full-year interest will exceed the $40 million to $43 million range set in August.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐓𝐫𝐚𝐝𝐞 𝐫𝐞𝐜𝐞𝐢𝐯𝐚𝐛𝐥𝐞𝐬 (𝟐𝟔𝐐𝟑): $𝟑𝟕𝟒.𝟐 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Uncollected customer bills rose 21.9% from a year ago and 7.6% from last quarter, outpacing the 14.5% rise in third-quarter revenue. Folding in Autronica's customer accounts and shipping a burst of firefighter gear late in the quarter tied up more cash in working capital.
𝐃𝐢𝐥𝐮𝐭𝐞𝐝 𝐬𝐡𝐚𝐫𝐞 𝐜𝐨𝐮𝐧𝐭 (𝟐𝟔𝐐𝟑): 𝟑𝟖.𝟔𝟓 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
The diluted share count fell 1.6% from 39.28 million a year ago after the Pittsburgh group spent $88.8 million on buybacks over the first nine months. That smaller share count added nearly 2 percentage points to per-share profit growth, though buybacks slowed to $12.7 million in Q3.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐅𝐘𝟐𝟔 𝐓𝐨𝐭𝐚𝐥 𝐑𝐞𝐯𝐞𝐧𝐮𝐞 𝐆𝐫𝐨𝐰𝐭𝐡: 𝐋𝐨𝐰-𝐝𝐨𝐮𝐛𝐥𝐞-𝐝𝐢𝐠𝐢𝐭 (𝟏𝟎–𝟏𝟐%) ⇘ decelerating
🠆 unchanged from Low-double-digit (10–12%)
Unchanged. Finance chief Julie Beck kept the full-year plan at low-double-digit total sales growth, or 11% at the middle of the range. With sales up 10.2% over the first nine months, the plan leaves about 13.1% growth for the fourth quarter by our math, down from 14.5% in Q3. Autronica supplies roughly 8 percentage points of that fourth-quarter gain, making the target achievable.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐃𝐢𝐝 𝐌𝐒𝐀 𝐒𝐚𝐟𝐞𝐭𝐲 𝐤𝐞𝐞𝐩 𝐢𝐭𝐬 𝐦𝐢𝐝-𝐬𝐢𝐧𝐠𝐥𝐞-𝐝𝐢𝐠𝐢𝐭 𝐮𝐧𝐝𝐞𝐫𝐥𝐲𝐢𝐧𝐠 𝐬𝐚𝐥𝐞𝐬 𝐭𝐚𝐫𝐠𝐞𝐭?
The release repeated the low-double-digit total sales plan, which includes Autronica, but dropped any mention of the mid-single-digit underlying sales target. Investors need to know whether fourth-quarter underlying sales are still expected to grow the 7.7% required to hit 5% for the year.
𝐖𝐡𝐚𝐭 𝐝𝐢𝐝 𝐭𝐡𝐞 𝐫𝐞𝐜𝐨𝐫𝐝 𝐀𝐋𝐓𝐀𝐈𝐑 𝐨𝐫𝐝𝐞𝐫 𝐚𝐝𝐝 𝐢𝐧 𝐫𝐞𝐜𝐮𝐫𝐫𝐢𝐧𝐠 𝐫𝐞𝐯𝐞𝐧𝐮𝐞?
Management highlighted its largest-ever MSA+ connected gas-detector order, yet the release did not update the share of portable sales coming from connected devices (14% in Q2) or disclose software subscription revenue.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐝𝐢𝐝 𝐀𝐮𝐭𝐫𝐨𝐧𝐢𝐜𝐚 𝐚𝐧𝐝 𝐭𝐚𝐫𝐢𝐟𝐟𝐬 𝐡𝐮𝐫𝐭 𝐐𝟑 𝐠𝐫𝐨𝐬𝐬 𝐦𝐚𝐫𝐠𝐢𝐧?
Gross margin excluding acquisition write-offs dropped by our math from 50.2% in Q2 to 47.0% in Q3. Management has not split that 3.2-point drop between Autronica's lower-margin mix, Middle East freight and materials inflation, and the absence of Q2's $4 million tariff refund.
𝐇𝐚𝐬 𝐌𝐒𝐀 𝐒𝐚𝐟𝐞𝐭𝐲 𝐬𝐞𝐭 𝐚𝐬𝐢𝐝𝐞 𝐦𝐨𝐧𝐞𝐲 𝐟𝐨𝐫 𝐆𝐥𝐨𝐛𝐞 𝐏𝐅𝐀𝐒 𝐥𝐚𝐰𝐬𝐮𝐢𝐭𝐬?
As of July, the company faced 1,222 lawsuits over firefighter-apparel chemicals with no disclosed financial reserve or insurance recovery estimate. The upcoming 10-Q filing must show whether legal costs or claim counts accelerated.
