

Strategic Transaction Advisory. $200MM + in Value Add For Our Clients. https://xitter.gq/t.co/kAFPNqYaaE
USA
Joined June 2024
- Tweets61
- Following13
- Followers66
- Likes126



Pinned Tweet
🔥🔥🔥
You’re unable to view this Post because this account owner limits who can view their Posts. Learn more
4
611
Semiconductor Series Part III: Chip Designers and Hyperscalers
The final part of the semiconductor series, Part III, is going to be about the designers behind the world’s advanced microchip ecosystem and their hyperscaler customers.
Some notable chip designers are: Intel, AMD, Apple, Qualcomm, and, of course, Nvidia just to name a few. The engineers at these companies use software from EDA providers like Synopsys and Cadence to design the chips that go into smartphones, computers, and datacenters.
On the datacenter side, hyperscalers like Microsoft, Amazon, Google, and Facebook cumulatively invest hundreds of billions of dollars of capex every year into outfitting their datacenters with the latest CPUs and GPUs.
Most of the world’s chips are designed by so-called fabless chip companies. Companies like Nvidia, AMD, and Qualcomm don’t own or operate the factories that produce their products.
This allows them to focus solely on designing the fastest and most efficient chips while also letting them remain asset-light. As such, companies like Nvidia sports an eye watering-ly low debt/equity ratio of just 13%. On the other hand, IDMs like Intel have more of a dual track mind, where their survival relies on their ability to maintain market leadership in both foundry and design capabilities.
A company like Intel must always bet on itself and take on substantial risk to finance new hundred billion dollar CapEx initiatives, while also designing attractive products to keep production lines running at full capacity.
The rise of the fabless, and the death of Intel
10 years ago, AMD and Nvidia were far from household names, but now both companies dwarf the historical chip king Intel in market cap. The rise of these two companies is equally a tale of disruptive innovation but also Intel’s C-suite hubris.
The downfall of Intel can be attributed to many different mistakes, but perhaps the biggest misstep the company took was their aversion to EUV lithography. TSMC had already made the costly transition to EUV technology on their 7nm node, and while the cost of these new EUV machines was in the low 9 figure range, it afforded Intel-rival AMD a technological advantage over them for the first time in decades. Intel was averse to EUV adoption because the company believed it could save money and extend the useful life of their DUV machines.
Former Intel CEO Bob Swan stated the company’s technological woes were “somewhat a function of what we've been able to do in the past, which in essence was defying the odds. At a time when it was getting harder and harder, we set a more and more aggressive goal. From that, it just took us longer.”
Upper management believed that its past history of innovation was an indicator of its future capabilities, and that easy node innovations would always be there. This was a false pretense, and it was one that killed the company. Intel, whose design team could only use their internal fabrication plants, were structurally handicapped.
Intel was first to 14nm by a full year, yet by the time the company got to their Intel 7 node, they were already two years behind TSMC. The difference? TSMC had fully adopted EUV by this time, while Intel-out of pure hubris- still thought that they could continue to print smaller and smaller features while maintaining acceptable yield levels using DUV multipatterning.
The x86 chip market is a commoditized duopoly between Intel and AMD. Both companies’ products are functionally equivalent, and thus each company must distinguish themselves by innovating on the raw performance of their chips.
This makes for extremely low switching costs and enables customers to use Intel for one datacenter, but then migrate to a more performant AMD system for the next. As such, AMD, whose talented designers could use TSMC’s superior technology, began to win back share in the PC and datacenter CPU market.
Nvidia’s Rise
Nvidia benefits from a fabless business model, but primarily, it operates within a different market segment than Intel. When a company chooses to buy an AMD CPU, it is a direct loss for Intel. The CPU market is a zero sum game, where TAM growth lifts all parties. On the other hand, Nvidia’s primary market is the GPU market. GPUs were mostly used in consumer gaming PCs, professional creative work, and the occasional supercomputer.
An Nvidia GPU was always the go-to choice for machine learning workloads as well, but this TAM was relatively small until ChatGPT hit the market. This was one of the biggest “a-ha!” moments for the market in years and is why the phrase “XYZ is having its ChatGPT Moment” was coined. The product thoroughly impressed the public with its natural language capabilities and showed investors that AI R&D payoff could come far sooner than expected.
All of a sudden, Nvidia became the picks and shovels of the AI boom. Transformer scaling laws dictate that the more compute and the more data you throw at a model, the better it gets; and as the primary supplier of compute, they held the gateway to greater model performance. As the ones who had a first-mover advantage in machine learning software infrastructure, in addition to their developer ecosystem network effect moat, Nvidia was in prime position to be the sole supplier of compute for all datacenters in the foreseeable future. This is exactly how it played out.
Since 2022, Nvidia, a hardware company, has increased gross profits by more than 500%. In 2023, alone, the company more than doubled its revenue solely on the back of price increases, which of course, went straight to the bottom line. In CY23, Nvidia had an 85% incremental EBITDA margin. These margins are absolutely unheard of for any company selling a physical product, and they’re akin to post operating-leverage realization SaaS levels of profitability.
Hyperscalers:
The big 3 hyperscalers in the US are Amazon, Google, and Microsoft. These companies operate huge cloud businesses where they rent out access to compute. Beyond these 3, there are other large hyperscalers players like Meta, Oracle, Tesla, Apple, and Alibaba, who are also chomping at the bit to buy more Nvidia GPUs. These hyperscalers all have unique and different strategies for the AI game.
Microsoft
Microsoft, for example, has a tight partnership with OpenAI, and although they do have an internal AI research team, the company relies heavily on OpenAI’s state of the art models for use in their own products like Copilot. Microsoft’s strength is in distribution. They have billions of devices on the windows platform, and billions more using services that run on Azure.
The company can’t justify investing tens of billions of dollars and shifting corporate focus onto internal AI research because they view that space as inevitably commoditized. Instead, a partnership with OpenAI gives them access to state of the art models, while reducing the financial and executional risk of an internal effort. The company has made slight efforts to develop its own AI accelerators, but their datacenters remain filled with an overwhelming majority of Nvidia GPUs.
Google
Google, on the other hand, has gone for a more vertically integrated approach. Google has historically been a leader of AI, and always invested heavily in AI development with projects like Waymo and DeepMind. Google is unique in that it has had an ongoing Tensor Processing Unit (TPU) development project since 2015.
These TPUs have been designed from the ground up for doing the simple matrix multiplication math required for AI, and are a direct substitute for Nvidia’s pricey GPUs. That said, many of these AI accelerator projects are difficult to pull off.
The actual hardware itself can be optimized for those simple matrix equations, but it has proven difficult to port over existing machine learning libraries, and make cutting edge training & inference work reliably at scale. This is where companies like Cerebras, Groq, Etched, and dare I say AMD find themselves right now. They have great hardware on paper that can do machine learning workloads faster than an Nvidia chip, but it has been difficult to commercialize the product given the lack of robust software support.
Google is the exception in this; they invested in TPU early, and it has proven to be capable of state of the art model training today. Not only do they have their chip situation sorted, we also cannot ignore the brilliant AI researchers that work at Google. Their natural language models like Gemini are nothing to scoff at, and the company’s image and video models, Imagen 3 and Veo 2, are head and shoulders above anything else on the market.
Lastly, in addition to internally developed chips and some of the best AI talent, Google also has the distribution network to back it up. They have billions of devices running Android and billions of devices that run services hosted on Google Cloud, analogous to Microsoft’s distribution capabilities.
Amazon
While Microsoft has gone for the horizontal partnership approach and Google has gone for the vertical integration approach, Amazon has found themselves somewhere in the middle.
Amazon’s internal AI research team isn’t particularly strong, but it does have a formidable chip design team, and another very strong distribution network. Amazon’s internal chip design team has been making great strides, and their recent Trainium 2 chip has been able to pick up certain design wins.
Apple is evaluating Trainium 2 for use, and Anthropic is due to receive a supercluster of 400k Tranium 2’s by the end of the year. This would make Amazon the 4th company whose AI accelerators will be deployed at scale: the first being Nvidia, the second being AMD, and the third being Google. Amazon’s partnership with Anthropic also runs quite deep; they’ve been stuffing Tranium 2’s down Anthropic’s throat- forcing the company to train and inference their future models on Amazon’s own chips.
This will help create a better field tested software ecosystem for Amazon’s AI accelerator platform and will serve as an on ramp towards greater commercialization of its internally developed chips in the future. Amazon’s other strength is their distribution network. AWS is the largest public cloud provider, estimates point to a 10 percentage point market share lead on Azure.
These clients, whose applications are stuck in AWS, will necessarily have to run their new AI enabled apps on AWS as well. You also cannot forget about Amazon's physical distribution capabilities. Their massive warehouse and shipping infrastructure around the world position Amazon as a large benefactor of physical AI products like humanoid robots and autonomous vehicles.


7Alder retweeted
Semiconductor Series, Part II : Foundries
Refer back to Part I: Raw Materials and Wafer Fabrication Equipment (WFE) for a quick refresher on the players at the very beginning of the semiconductor food chain. Part II of the semiconductor series is going to be about the companies and the factories that make them.
In the olden days, those who designed the chips were also the ones who made them: the fabled IDM model. Since then, industry titans like AMD have either sold or spun-off their foundries, and other players like Texas Instruments and NXP have elected to go with “fab-lite” models. The foundry and chip designer spectrum is largely divided into 3 sections: pure-play foundry, fab-lite, and fabless. Some quick housekeeping, the word foundry and fab-short for fabrication plant- are largely interchangeable, and the word IDM stands for Integrated Device Manufacturer, meaning a company that designs and fabs their own chips.
Starting from the left hand-side with pure-play foundry companies, Taiwan Semiconductor Manufacturing Company (TMSC) is the objective leader of the pack. 90% of the world’s advanced chips come out of TSMC. The chips that go into phones, laptops, VR headsets, datacenters, supercomputers etc. are likely made in a TSMC fab. These fabs are composed of the latest and greatest wafer fabrication equipment (WFE) made by the big 5: Applied Materials, ASML, KLA-Tencor, Lam Research and Tokyo Electron. The job of the foundry, TSMC, is to combine that magical WFE into a functioning assembly line that can churn out the latest chips.
This is an extremely challenging process that even the equipment suppliers themselves do not know how to handle. The foundry is like the structural engineer of a 100+ story skyscraper and the conductor of a 1000 piece orchestra. It must find out how to architect transistors and interconnects such that speed, efficiency, and thermals are optimized, while also tuning every piece of equipment precisely so it operates within a tolerance measured by nanometers.
This is why the job of the foundry is so vital to both its customers, and the nations upon which its facilities lie upon. There are currently only 3 countries with foundries considered bleeding-edge operated by domestic players: Taiwan, Korea, and the United States. Taiwan has TSMC, Korea has Samsung, and America has Intel. These 3 companies all have the capability to manufacture what would be considered the most advanced chips.
Each generation, or “node,” is marked with a name defined in nanometers. The latest node to enter mass production has been the 3nm node. 3nm doesn’t actually mean each transistor is 3nm large, it is just the name of a single generation of node. Similar to how the iPhone goes from iPhone 14 to 15, nodes will jump from 5nm to 3nm and aren’t an indication of transistor size.
Aside from the big 3 foundries TSMC, Samsung, and Intel, the manufacturing capability of competitors drops drastically. The 4th most competitive foundry is China’s SMIC, Semiconductor Manufacturing International Corporation, which is technologically years behind the frontier. To put it into perspective, SMIC’s 7nm generation node is their latest actual node to enter mass production. Meanwhile, TSMC’s 7nm node entered mass production nearly 6 years earlier. To quantify that in terms of performance, we can compare the performance of smartphone chips. Apple’s most recent iPhone chip on TSMC’s 3nm process is >2x as fast as their last iPhone chip on 7nm.
Smartphone CPU performance is likely to be a more accurate representation of performance improvements solely attributable to process node improvements, as smartphone chip design is in a far more mature state than GPU design-where architectural and algorithmic improvements are increasing performance 2x every few months. That being said, using the smartphone chip benchmark, a given chip based on TSMC 3nm is likely to be either twice as fast, or twice as power efficient as a given chip produced from the latest SMIC fab.
At a datacenter level, TSMC process node customers can build out twice the compute capability for the same price, power envelope, and real estate footprint. This advantage is absolutely crucial in a time where the artificial intelligence industry is being driven by logarithmic scaling laws, and where the size of datacenters is being capped by local power draw limitations.
This means that you must increase compute resources exponentially for linear increases in model performance, but you only have a finite allotment of power your datacenter can draw. In the age of AI, power efficiency doesn’t just matter from a TCO point of view, but it is now the main driving force behind how much compute we can throw into training a model. These power limitations imposed by the local utility are the reason why big tech companies have opted to go the private route and invest in or partner with small modular nuclear reactor companies-another topic we have covered in the past!
Shifting back to foundry, it is evident that there is a large difference between a great foundry and a good one. Major supply chains like that of the iPhone or a Hopper GPU are entirely reliant on fabs in Taiwan for manufacturing their chips. Being a country with cutting edge fabs on your territory is crucial from a national security perspective because it insulates your domestic innovation from global conflicts. If Taiwan’s facilities are compromised by an earthquake or a military operation, US chip designers like Nvidia can still turn to TSMC’s USA facilities, or even Intel to continue to pump out competitive chips.
Moving onto fab-lite, there are companies like Texas Instruments (now less so), NXP Semi, and Infineon that employ this business model. Keeping on the bleeding edge of semiconductor fabrication is challenging from both a human and financial capital lens.
Developing the next generation of process node is getting increasingly expensive as TSMC’s 5nm node cost twice as much to develop as their 7nm node did. Without mentioning R&D, the CapEx bill can get into the $20-30 billion mark for just one facility. This is why, for companies whose core business does not revolve around cutting edge nodes, it makes sense to go fab-lite. These companies can still be considered IDMs because they still design and manufacture some of their own chips to an extent. But, any chip they sell that is designed on an advanced node will be manufactured by a third party like TSMC.
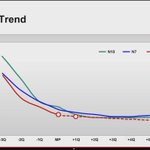
The fundamental reason this operating model works is due to how process nodes age. The bulk of Texas Instruments’ products are manufactured on process nodes in the 45nm-130nm node, process nodes that initially entered mass production 2 decades ago. Even though the next generations of process nodes are getting more expensive to develop, those same process nodes will eventually drop in price and will be able to be made more economically. Over time, fabs can always figure out how to decrease the defect density on a wafer. Here is how it generally trends overtime:
As you can see, fabs consistently improve at mitigating manufacturing defects, which increases yield per wafer, and improves the cost basis. Not only this, but WFE based on previous gen technology is far cheaper to buy off equipment suppliers than when they were cutting edge. This means that for a given node, the cost for building a fab, and subsequently producing that node gets cheaper with time.
A great example of the fab-lite business model is with Texas Instruments’ purchase of Micron’s Lehi Fab, which produces 65nm and 45nm chips. They bought the fab for just $900 million in 2021, while it likely cost roughly ~$4 billion to build. This $4 billion figure comes from the plant’s initial $2.5 billion construction, plus an additional $1.5 billion investment in the early 2010s. This is why IDMs whose products do not need to be manufactured on the latest process node prefer the fab-lite model. With fab-lite companies, it’s not mission critical to be on the latest node.
They can save themselves the capex and outsource to TSMC while they wait for the technology to inevitably become cheap enough to invest in.
This fab-lite model is the strategy that Texas Instruments, NXP Semi, Infineon, STMicro, and many others have committed to. Their products are not in the latest smartphones or the newest Nvidia GPUs, but instead inside your cars, scooters, internet routers, refrigerators, laundry machines, and electrical equipment. These applications don’t need the most power efficient or speedy chip on the market! When was the last time you felt the user interface on your microwave wasn’t snappy enough?
Truth be told, Texas Instruments has generally pivoted away from the fab-lite strategy, but at some point the company was outsourcing production of some 40-50% of chips. There are likely several factors that the management at Texas Instruments has taken into consideration when moving away from fab-lite back to true IDM.
The main reason likely stems from geopolitics and its effect on the semiconductor supply chain. If Texas Instruments fully relied on a foundry like TSMC or UMC, and say Taiwan were to be compromised, then Texas Instruments would likely go down with it.
The US government understands this issue and is certainly front of mind for many in congress which is why they’ve passed a massive subsidy package for domestic semiconductor manufacturing with the US CHIPS act in 2022.
Texas Instruments has already received $1.6 billion in direct funding from the CHIPS Act. The derisking from Taiwan in addition to the government support for domestic fabs are likely two factors influencing the higher ups at Texas Instruments to invest heavily in reshoring semiconductor manufacturing back onto US soil. They actually recently announced an $11 billion upgrade to the Lehi fab they bought from Micron, and have committed another $30 billion to spring up 4 new fabs in Sherman, TX.
So much for fab-lite!


Semiconductor Series, Part II : Foundries
Refer back to Part I: Raw Materials and Wafer Fabrication Equipment (WFE) for a quick refresher on the players at the very beginning of the semiconductor food chain. Part II of the semiconductor series is going to be about the companies and the factories that make them.
In the olden days, those who designed the chips were also the ones who made them: the fabled IDM model. Since then, industry titans like AMD have either sold or spun-off their foundries, and other players like Texas Instruments and NXP have elected to go with “fab-lite” models. The foundry and chip designer spectrum is largely divided into 3 sections: pure-play foundry, fab-lite, and fabless. Some quick housekeeping, the word foundry and fab-short for fabrication plant- are largely interchangeable, and the word IDM stands for Integrated Device Manufacturer, meaning a company that designs and fabs their own chips.
Starting from the left hand-side with pure-play foundry companies, Taiwan Semiconductor Manufacturing Company (TMSC) is the objective leader of the pack. 90% of the world’s advanced chips come out of TSMC. The chips that go into phones, laptops, VR headsets, datacenters, supercomputers etc. are likely made in a TSMC fab. These fabs are composed of the latest and greatest wafer fabrication equipment (WFE) made by the big 5: Applied Materials, ASML, KLA-Tencor, Lam Research and Tokyo Electron. The job of the foundry, TSMC, is to combine that magical WFE into a functioning assembly line that can churn out the latest chips.
This is an extremely challenging process that even the equipment suppliers themselves do not know how to handle. The foundry is like the structural engineer of a 100+ story skyscraper and the conductor of a 1000 piece orchestra. It must find out how to architect transistors and interconnects such that speed, efficiency, and thermals are optimized, while also tuning every piece of equipment precisely so it operates within a tolerance measured by nanometers.
This is why the job of the foundry is so vital to both its customers, and the nations upon which its facilities lie upon. There are currently only 3 countries with foundries considered bleeding-edge operated by domestic players: Taiwan, Korea, and the United States. Taiwan has TSMC, Korea has Samsung, and America has Intel. These 3 companies all have the capability to manufacture what would be considered the most advanced chips.
Each generation, or “node,” is marked with a name defined in nanometers. The latest node to enter mass production has been the 3nm node. 3nm doesn’t actually mean each transistor is 3nm large, it is just the name of a single generation of node. Similar to how the iPhone goes from iPhone 14 to 15, nodes will jump from 5nm to 3nm and aren’t an indication of transistor size.
Aside from the big 3 foundries TSMC, Samsung, and Intel, the manufacturing capability of competitors drops drastically. The 4th most competitive foundry is China’s SMIC, Semiconductor Manufacturing International Corporation, which is technologically years behind the frontier. To put it into perspective, SMIC’s 7nm generation node is their latest actual node to enter mass production. Meanwhile, TSMC’s 7nm node entered mass production nearly 6 years earlier. To quantify that in terms of performance, we can compare the performance of smartphone chips. Apple’s most recent iPhone chip on TSMC’s 3nm process is >2x as fast as their last iPhone chip on 7nm.
Smartphone CPU performance is likely to be a more accurate representation of performance improvements solely attributable to process node improvements, as smartphone chip design is in a far more mature state than GPU design-where architectural and algorithmic improvements are increasing performance 2x every few months. That being said, using the smartphone chip benchmark, a given chip based on TSMC 3nm is likely to be either twice as fast, or twice as power efficient as a given chip produced from the latest SMIC fab.
At a datacenter level, TSMC process node customers can build out twice the compute capability for the same price, power envelope, and real estate footprint. This advantage is absolutely crucial in a time where the artificial intelligence industry is being driven by logarithmic scaling laws, and where the size of datacenters is being capped by local power draw limitations.
This means that you must increase compute resources exponentially for linear increases in model performance, but you only have a finite allotment of power your datacenter can draw. In the age of AI, power efficiency doesn’t just matter from a TCO point of view, but it is now the main driving force behind how much compute we can throw into training a model. These power limitations imposed by the local utility are the reason why big tech companies have opted to go the private route and invest in or partner with small modular nuclear reactor companies-another topic we have covered in the past!
Shifting back to foundry, it is evident that there is a large difference between a great foundry and a good one. Major supply chains like that of the iPhone or a Hopper GPU are entirely reliant on fabs in Taiwan for manufacturing their chips. Being a country with cutting edge fabs on your territory is crucial from a national security perspective because it insulates your domestic innovation from global conflicts. If Taiwan’s facilities are compromised by an earthquake or a military operation, US chip designers like Nvidia can still turn to TSMC’s USA facilities, or even Intel to continue to pump out competitive chips.
Moving onto fab-lite, there are companies like Texas Instruments (now less so), NXP Semi, and Infineon that employ this business model. Keeping on the bleeding edge of semiconductor fabrication is challenging from both a human and financial capital lens.
Developing the next generation of process node is getting increasingly expensive as TSMC’s 5nm node cost twice as much to develop as their 7nm node did. Without mentioning R&D, the CapEx bill can get into the $20-30 billion mark for just one facility. This is why, for companies whose core business does not revolve around cutting edge nodes, it makes sense to go fab-lite. These companies can still be considered IDMs because they still design and manufacture some of their own chips to an extent. But, any chip they sell that is designed on an advanced node will be manufactured by a third party like TSMC.
The fundamental reason this operating model works is due to how process nodes age. The bulk of Texas Instruments’ products are manufactured on process nodes in the 45nm-130nm node, process nodes that initially entered mass production 2 decades ago. Even though the next generations of process nodes are getting more expensive to develop, those same process nodes will eventually drop in price and will be able to be made more economically. Over time, fabs can always figure out how to decrease the defect density on a wafer. Here is how it generally trends overtime:
As you can see, fabs consistently improve at mitigating manufacturing defects, which increases yield per wafer, and improves the cost basis. Not only this, but WFE based on previous gen technology is far cheaper to buy off equipment suppliers than when they were cutting edge. This means that for a given node, the cost for building a fab, and subsequently producing that node gets cheaper with time.
A great example of the fab-lite business model is with Texas Instruments’ purchase of Micron’s Lehi Fab, which produces 65nm and 45nm chips. They bought the fab for just $900 million in 2021, while it likely cost roughly ~$4 billion to build. This $4 billion figure comes from the plant’s initial $2.5 billion construction, plus an additional $1.5 billion investment in the early 2010s. This is why IDMs whose products do not need to be manufactured on the latest process node prefer the fab-lite model. With fab-lite companies, it’s not mission critical to be on the latest node.
They can save themselves the capex and outsource to TSMC while they wait for the technology to inevitably become cheap enough to invest in.
This fab-lite model is the strategy that Texas Instruments, NXP Semi, Infineon, STMicro, and many others have committed to. Their products are not in the latest smartphones or the newest Nvidia GPUs, but instead inside your cars, scooters, internet routers, refrigerators, laundry machines, and electrical equipment. These applications don’t need the most power efficient or speedy chip on the market! When was the last time you felt the user interface on your microwave wasn’t snappy enough?
Truth be told, Texas Instruments has generally pivoted away from the fab-lite strategy, but at some point the company was outsourcing production of some 40-50% of chips. There are likely several factors that the management at Texas Instruments has taken into consideration when moving away from fab-lite back to true IDM.
The main reason likely stems from geopolitics and its effect on the semiconductor supply chain. If Texas Instruments fully relied on a foundry like TSMC or UMC, and say Taiwan were to be compromised, then Texas Instruments would likely go down with it.
The US government understands this issue and is certainly front of mind for many in congress which is why they’ve passed a massive subsidy package for domestic semiconductor manufacturing with the US CHIPS act in 2022.
Texas Instruments has already received $1.6 billion in direct funding from the CHIPS Act. The derisking from Taiwan in addition to the government support for domestic fabs are likely two factors influencing the higher ups at Texas Instruments to invest heavily in reshoring semiconductor manufacturing back onto US soil. They actually recently announced an $11 billion upgrade to the Lehi fab they bought from Micron, and have committed another $30 billion to spring up 4 new fabs in Sherman, TX.
So much for fab-lite!
Semiconductor Series, Part I : Raw Materials and Wafer Fabrication Equipment (WFE)
There are many different kinds of chips: wood chips, potato chips, poker chips etc. but perhaps the most important variety of chip is the computer microchip. These types of chips are a culmination of human scientific progress, and continue to push the boundaries of physics with every new generation. They act as the brains that power our everyday lives, from household items like smartphones and microwaves to the massive supercomputers that we use to predict the weather. Today, chips are not just a gadget that provides us with the personal convenience of Google, but they have evolved to become a topic worth discussing at a geopolitical and anthropological scale.
The semiconductor industry is one of the fastest developing and geopolitically important industries on earth. Understanding the semiconductor industry serves its purpose not only by satiating one’s own curiosity, but it also provides a new angle for evaluating the international relations between China, Taiwan, and the United States. This 3 part semiconductor series will be an industry overview of the semiconductor space, starting with Part I: Raw Materials and Equipment Manufacturers.
The most important raw material in the semiconductor industry is the semiconducting element itself, Silicon. This element can be doped with other elements, and then controlled using an electric field to determine its conductivity. Humans leveraged this quality of Silicon to build out logical circuits that can do all sorts of operations. The other element you’ll find abundantly in a chip is Copper. These make up the local roads, highways, interstates, freeways, and elevators that carry data around the chips. You also can’t forget about the Metal-Oxide based photoresists. This material acts as the paper in which chip designs are stenciled onto, and needs to be layered onto the same chip up to 100 separate times throughout the chipmaking process.
Let’s examine exactly how these materials are used in the process. Each computer chip originally started off as sand, silica sand to be specific. The silica sand will then be melted into molten silicon, then a small silicon crystal will be dipped into the molten silicon, acting as the base crystalline structure for the molten silicon to attach onto. In this way, a solid round silicon ingot is pulled from the molten liquid, and then sliced into half millimeter thick circular wafers. Each individual wafer is like a canvas, for tens if not hundreds of chips to be imprinted into. Here is a graphic of the chipmaking process made by Branch Education:
The first step in the process is doping the silicon. In order to do this, a layer of silicon dioxide is added to the entire wafer using a deposition machine likely made by Applied Materials. A photoresist is then added on top using a machine from Tokyo Electron. The Metal-Oxide based photoresist reacts with UV light, either strengthening or weakening depending on the specific material.
This photo-resist covered wafer is then put into a photolithography machine built by ASML. This machine essentially uses what is called a photomask to imprint a design onto the photoresist. It is merely using a stencil and UV light to print a design onto the photoresist, altering the properties of part of the photoresist in an intricate way.
After stenciling a design in, the weak part of the photoresist is then dissolved using a developer made by Tokyo Electron
The newly exposed base layer of silicon dioxide is etched away in the stenciled design by an etcher made by Lam Research, Tokyo Electron, or Applied Materials.
The now exposed raw silicon is doped through a process called ion implantation, where the silicon wafer is bombarded with either Boron, arsenic, phosphorus, and occasionally gallium. The ion implantation machine, made by Applied Materials, literally shoots these elements at the silicon wafer.
A deposition machine is then used to deposit a new layer of silicon into the crevices of the photoresist.
The photoresist is then fully removed, and we are left with a silicon wafer that has been doped in a certain pattern. A planarization machine will then smoothen out the surface of the wafer, ensuring its uniformity for when the next layer is added.
This initial process will repeat for about 10-20 layers, and will create all the transistors on the chip, finishing the FEOL-front-end of line- process for chipmaking.
After the initial 10-20 layers, it is now time to build the data highways in the BEOL-back-end of line- process. How can one part of the chip relay information to another? It has 3 options depending on where it needs to send data, a local, regional, and global road system. These road systems are built through a similar process. The wafer will receive a deposition of silicon dioxide, then a photomask, then it will be weakened by lithography, which will allow the developer to remove the weakened portions. This is where the process changes. The exposed parts of the silicon dioxide layer will still be etched away, but in its place, will be newly deposited copper traces. This process will continue for another 100+ layers, there are a ton of interconnects
Next steps for the industry, and where opportunity might lie ahead:
The semiconductor industry moves fast, and equipment that was cutting edge a few years ago, can seem archaic today. The next big move in the semiconductor industry from a raw material and equipment manufacturing standpoint is the shift away from FinFET to Gaa-FET, short for gate-all-around field effect transistor. Here is the visual difference:
Without going into the technicalities of why Gaa-FET is advantageous from a performance standpoint, one can just visibly see that Gaa-FET’s will require a more intricate build out along the vertical axis. For the same transistor, there now exists two more protruding fins in comparison to FinFET. These protruding fins are also oriented orthogonal with respect to the vertical axis, meaning that each fin necessitates its own layer, and by extension will pass through all those machines in the FEOL process another time. With additional layers, and more intricate transistors, the raw material suppliers that are likely to win are the photoresist and cleaning chemical suppliers. Each layer will require its own photoresist, and multiple rounds of cleaning.
On the WFE side, the increase in layers is likely to be a rising tide for equipment manufacturers, as now there is more work to be done for the same chip. That being said, the one corner of the WFE market that should be poised to shine even brighter is metrology/inspection. FinFET was already quite intricate to manufacture, but Gaa-FET is a new beast all around. Put simply, we can use Murphy’s law, “Anything that can go wrong, will go wrong”. With the new structural complexity introduced by Gaa-FET, there will definitely be far more defects per unit area on the wafer. As such, metrology/inspection tools will take on an increasingly important role in the production line.
Who makes these machines, and how to get involved as an investor:
Now that you are familiar with the process, let’s examine the businesses behind each of these steps. To do this, we can try to piece together a case study for TSMC’s cutting edge fabs. The company gracefully provides a list of raw materials suppliers, so the only speculation will come from the WFE suppliers (Wafer Fabrication Equipment suppliers), which are concentrated around 5 big firms: ASML, Applied Materials, Lam Research, Tokyo Electron, and KLA-Tencor.
Starting off with the raw materials, we can see that for the raw silicon wafers, TSMC is supplied by:
F.K.S. (Formosa Komatsu Silicon)
SunEdison (Formerly Known as MEMC, Monsanto Electronic Materials Company)
Shin-Etsu Handotai
Siltronic
Sumco
TSMC lists their chemicals suppliers as:
BASF
Mitsubishi Chemical
These chemicals these companies supply TSMC are likely the cleaning chemicals like the pure ammonia water used to clean the wafers at each step.
TSMC’s photoresist suppliers are:
Merck (by way of AZ acquisition)
Shin-Etsu Chemical
Sumitomo
T.O.K. (Tokyo Ohka Kogyo)
TSMC’s gas suppliers are:
Air Liquide
Air Products
BOC (British Oxygen Company)
Taiyo Nippon Sanso
These gases are likely used in processes like the oxidation, vapor deposition, and vapor etching steps.
Among the raw material suppliers, Shin-Etsu Handotai is owned by Shin-Etsu chemical, so those count as one entity, and Sumco is a joint venture between Sumitomo and Mitsubishi.
As for WFE suppliers, we can only speculate as to whose equipment lines the cutting edge fabs of TSMC. Here is a quick graphic that represents the market share of each of the big 5 in each chipmaking process.
For the sake of our simplified model, let’s assume that TSMC uses the highest market share provider of equipment in every individual process-In reality, deposition and etching have many different processes, and one company might make the machine for chemical vapour deposition, and another one might make the machine for physical vapour deposition. Each company’s abbreviation will be substituted for their full name.
At a simplified level, that would mean a common process would look like this:
In order,
For FEOL (transistor layers):
TEL Oxidation Machine
TEL Coater
ASML Photolithography Machine
TEL Developer
LAM Etching Machine
AMAT Ion Implantation Machine
AMAT Deposition Machine
AMAT Planarization Machine.
For BEOL (interconnect layers):
AMAT Deposition Machine
TEL Coater
ASML Photolithography Machine
TEL Developer
LAM Etching Machine
AMAT Deposition Machine
AMAT Planarization Machine
You might have noticed KLA-Tencor is not listed in either process. KLA-Tencor offers metrology machines that inspect the chip at nearly every step in the process. After every step, there will be an inspection to ensure that everything went accordingly, and that there are no defects. In addition, another piece of equipment that was left out was cleaning machines. These machines also intercept the wafer at every step, ensuring that no dust particles or other alien matter is on the wafer. Companies like Screen, Tokyo Electron, Lam Research, and Applied Materials are the major players within the wafer cleaning equipment segment.
From a public equities investor perspective, you can easily become a shareholder of semicap titans like Applied Materials, Lam Research, ASML, and KLA Tencor. Many of the Japanese names listed above don’t trade on US stock exchanges. If you want to make a secular bet on certain subvertical within the WFE space like Gas or Chemicals, you can sometimes find something that trades on the US stock exchange. For Gas, you have Air Products (NYSE: APD), and for photoresists you can buy Merck (NYSE: MRK). That said, there doesn’t seem to be any WFE chemicals or silicon wafer supplier companies listed on an American stock exchange. If your broker has access to the OTCMKTS, then you’ll be able to pick up most of these stocks.
From a private markets perspective, staying in the semiconductor industry requires a lot of operational complexity and risky R&D, which is why there isn’t too much private market activity within the space. The opportunity for private market investors to get involved usually comes in the form of project specific financing. For example, Brookfield invested $15B in Intel’s Ocotillo campus in 2022, for a 49% stake in the fabs that were being built there. This is essentially an infrastructure investment, and can allow a private market player to reap the upside of a single project’s stable cash flows while avoiding the operational complexity of leading a semiconductor company. Whether you are a large player that can help finance big projects all by yourself, or a smaller player that is willing to be a part of a broadly syndicated package, you can make a bet on the semiconductor industry in the form of project specific financings.
Now, you are equipped with the knowledge of what raw materials are used, what equipment is used, who the suppliers are, and where the industry is going. Stay tuned to learn more about foundries and chip designers in Part II of the semiconductor series: Foundries


The veterinary services market has experienced steady growth, driven by increasing pet ownership and heightened consumer spending on pet healthcare. The U.S. market is valued at approximately $11.9 billion in 2022 with a CAGR of 9.7% from 2023 to 2030.
According to the American Veterinary Medical Association, mean annual expenditures on veterinary visits increased from $224 in 2020 to $362 in 2022 for households with dogs and increased from $189 in 2020 and $321 in 2022 for households with cats. However, veterinary visits declined by 2% annually for 11 consecutive quarters from 2022 to 2024. This decline may be due to a 6.4% rise in veterinary costs in 2023, outpacing overall U.S. inflation and leading some owners to defer non-essential visits. The industry also faces a veterinarian shortage, with only 76% of projected demand expected to be met, increasing workloads of veterinarians and straining clinics.
Despite some of these concerns, the veterinary sector has attracted interest from private equity in recent years. Since 2017, total PE deal volume in the U.S. veterinary sector has surpassed $45 billion, with acquisition multiples ranging from 10-18x EBITDA. Private equity firms are drawn to veterinary clinics because of their recession-resilient nature, cash-based operations, and most importantly, their opportunities for consolidation due to the fragmented ownership landscape.
The buy-and-build strategy is the main strategy private equity firms use to approach the veterinary industry. Multiple clinics are acquired and integrated to form consolidated, larger entities to leverage synergies and increase market power. Several clinics have adopted this approach, reshaping the veterinary landscape.
VetCor, one of the most prominent veterinary consolidators, grew from 41 clinics in 2010 to over 850 across the United States and Canada today. Cressey & Company initially gained control over VetCor in 2010 and implemented a buy-and-build strategy to consolidate independent veterinary practices, many of which were owned by veterinarians nearing retirement. These smaller businesses could be acquired for a mid-single-digit EBITDA multiple versus a mid-teens multiple.
Under ownership, VetCor optimized operations by standardizing management, training, and administrative functions while allowing individual clinics to maintain their local identities. This balance between corporate efficiency and local autonomy made VetCor attractive for investors. The buy-and-build strategy proved successful as VetCor expanded under new investor interest from Harvest Partners, Oak Hill Capital, and TPG Capital.
From the seller’s perspective, the VetCor strategy allows these independent clinics to maintain operational autonomy while benefitting from shared resources and economies of scale. Veterinary clinic owners are further incentivized to sell their business to private equity firms because it provides them with liquidity.
Over the past decade, VetCor has achieved an annual EBITDA growth rate of 15% and VetCor continues to acquire two to three clinics each month.
Despite its success, consolidation in the veterinary sector presents challenges. As more investors enter the space, competition for acquisitions intensifies, driving up valuations and limiting the availability of attractive targets.
In December 2017, KKR acquired PetVet Care Centers (another reputable network of veterinary hospitals) from previous owners Ontario Teachers’ Pension Plan and L Catteron. At the time of acquisition, PetVet operated 125 globally branded hospitals across 22 states. KKR’s investment aimed to support PetVet’s growth strategy by focusing on acquiring and operating general practice and specialty veterinary hospitals to diversify its existing clinics. In October 2023, KKR secured a $2.3 billion private loan from a group of lenders led by Blue Owl Capital to recapitalize PetVet, aiming to pay off over $3 billion in outstanding debt set to mature throughout 2025. Under KKR’s ownership, PetVet has grown to operate over 450 clinics across the United States.
The National Veterinary Associates (NVA) has also expanded into multiple segments, operating over 1,400 veterinary hospitals and pet resorts across North America, Europe, and Australia. NVA was acquired by Summit Partners in 2007, then Ares Management in 2014, and finally JAB Holding Company in 2019 in a $5 billion deal. NVA generates more than $3.5 billion in annual revenue, with an estimated EBITDA of $650 million in 2023.
To supplement the buy-and-build strategy, competitors are leveraging pricing strategies to increase market share. Thrive Pet Healthcare has pursued a different strategy by focusing on affordability and subscription-based preventative care after backing from Morgan Stanley Capital Partners and later TSG Consumer Partners.
In 2022, Thrive rebranded and introduced Thrive Plus, a membership program offering free exams and discounted services that the company claims to save subscribers approximately $300 per year. By 2023, the program had more than 200,000 active members, generating over $120 million in recurring revenue. Thrive has also invested strongly in telemedicine and AI-driven diagnostics to enhance efficiency. In 2023, its revenue reached approximately $1.1 billion, with an estimated EBITDA of $180 million and a valuation of around $2.5 billion in 2022.
Overall, the buy-and-build method has offered a clear path to value generation at a time when the veterinary services industry is experiencing record-level deal multiples. GPs are currently under pressure to build asset value in ways that do not rely on traditional strategies like falling interest rates and stable GDP growth. That is, this strategy is appealing for GPs who see opportunities to build additional asset value in the veterinary sector through smaller add-ons that can be acquired for lower multiples. Ultimately, this brings down the average cost of acquisition through multiple arbitrage.


From Waste Management to WM: How an Industry Giant Came to Be
In 1893, Dutch immigrant Harm Huizenga collected trash in Chicago for $1.25 per wagon. In 1968, Huizenga’s grandson and two other investors were inspired by his hard work and humility, founding Waste Management (now rebranded as WM) to serve the community. In 2025, that same company is worth $91.4 billion.
Its revenue is segmented by collection, transfer, landfill, and recycling. Collection is WM’s main driver (55% of revenue) and spans commercial, industrial, and residential services. WM’s competitive advantage in collection is its ownership of landfills: about 70% of collected waste is disposed of in WM’s 263 landfills, resulting in higher consolidated margins and operating cash flows because WM does not have to outsource most of its disposal services.
For the full year 2024, WM delivered 11% growth in adjusted operating EBITDA and achieved a record 30% corresponding operating EBITDA margin, with guidance for continued double-digit growth in 2025. The company reported $22.1 billion in revenue, representing 8.0% growth from the previous year and surpassing competitors Republic Services ($16.9 billion) and Clean Harbors ($5.8 billion).
WM attributed this growth primarily to a 6.7% increase in core price, a performance metric used by management to evaluate the effectiveness of pricing strategies. Core price is not derived from financial statements and relies on historical assumptions to ensure comparability between reporting periods. Approximately 40% of WM collection contracts are tied to index-based pricing, while the remaining 60% adjust incrementally with market conditions.
From the beginning, WM’s strategy has been developing long-lasting client relationships. This is evidenced by their annual churn rate of 9% for commercial and industrial customers, which suggests that the average customer stays with WM for over 10 years.
In line with listening to customers, WM has taken up sustainability initiatives in recent years based on three pillars: repurposed material, renewable energy, and thriving communities. In 2023, WM reported repurposing 15.2 million tons of material and using 43% of its captured landfill gas for beneficial use applications, which leverage methane to generate renewable natural gas, a lower-carbon energy source. WM also made $18.7 million in charitable contributions in 2023.
WM opened eight recycling facilities in 2023, raising their total number to 102, with the goal of increasing safety, speed, and sorting capabilities. WM also added nine organics processing facilities, raising their total number to 49. Two of these organics processing facilities were FOG2Fuel facilities, which divert waste away from landfills by converting fats, oils, and grease into feedstock for biodiesel production. This process reduces landfill holding costs while providing a new revenue stream. The remaining organics processing facilities transform food scraps and yard waste into high-quality compost.
WM’s new sustainability strategy primarily lies in its renewable energy efforts, including $3 billion in planned investments in its sustainable businesses between 2022 and 2026. $1.6 billion of those investments are allocated towards the construction of 20 plants that capture natural gas at its landfills to fuel power generation and its natural-gas-vehicle fleet. The remaining investment is allocated towards its recycling plants. Its sustainability investments also position it favorably in the market compared to competitors like Republic Services who invested $683 million in sustainability in 2023.
WM’s active landfills not only have landfill gas collection systems to capture gas that can be turned into renewable energy but also have cover systems that minimize emissions, odors, fires, pests, dust, litter, and precipitation infiltration. Final capping systems are also placed over landfills finished with accepting waste to minimize stormwater infiltration in order to maximize landfill gas capture.
“You might not think of us as an energy company, but it’s a very important product of our business and a focus area for us,” Chief Executive Jim Fish told the Wall Street Journal.
In 2023, WM converted 66% of their diesel-powered collection fleet to alternative fuel vehicles with lower-emissions natural gas, making its 12,000 natural gas trucks the largest alternative-fuel fleet in the waste management industry. WM has achieved operational cost savings of $1 billion, primarily due to the adoption of these alternative fuel vehicles, alongside a reduction of over 3.5 million metric tons in carbon emissions. WM is also exploring other alternatives, such as electric and hydrogen-powered vehicles.
Moving into 2025, renewable energy remains one of WM’s top priorities. They are currently in the process of integrating its recent acquisition Stericycle, a medical waste disposal company. WM acquired Stericycle in November 2024 with an enterprise value of $7.2 billion, making the deal WM’s largest acquisition. The acquisition is expected to generate over $125 million in annual run-rate synergies, leveraging WM’s expertise in logistics, technology-enabled cost optimization, and its extensive waste disposal network.
This strategic acquisition advances WM’s sustainability initiative and expands into a new vertical of healthcare waste management. The acquisition has led to the formation of the WM Healthcare Solutions division, which integrates Stericycle’s medical waste and secure information destruction services.
The US medical waste management was valued at $2.88 billion in 2024 and is projected to grow at a CAGR of 7.9% from 2025 to 2034. WM’s entry into the medical waste sector through their acquisition of Stericycle positions the company to capitalize on this growing market by offering sustainable waste management solutions to healthcare providers.
Overall, WM maintains a strong outlook, demonstrating resilience to economic cycles due to the essential nature of waste management services. While industrial and commercial waste collection fluctuates with manufacturing and construction activity, and landfill gas revenue is influenced by volatile energy prices, residential waste collection remains a necessity, ensuring stable demand regardless of market conditions. This consistent demand supports recession-resistant revenue and strong, steady cash flow.
WM mitigates risks through service diversification, long-term contracts, and operational efficiencies. Its beta coefficient of 0.78 reflects low volatility, and its stable cash flows enable balanced capital allocation, including a 6% CAGR in dividends over the past five years.
Since its founding in 1968, WM has driven growth through sustainability, strategic expansion, and disciplined financial management. With a focus on acquisitions and operational efficiency, the company is well-positioned for long-term success.

