

Award-winning options asset manager. Ivy League. $1Billion in options strategies, $750M in options cash flow. (NOT advice)
$750M in options cash flow
Joined January 2023
- Tweets10K
- Following670
- Followers10.3K
- Likes12.4K

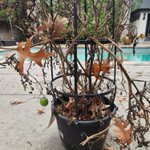




I shit you not, look at this little tomato in my friend's backyard. Frikin superstar.
Guys, trading isnt easy, but don't give up. Be the tomato.

OptionHans retweeted
That was a Doozy. In Trader63 we were long puts in QQQ, NBIS, CRWV, so we had a bit of fun this past week. But the selloff that just tore through the market has a different character than the dips of the past couple of years. This is a genuine flush- the kind of indiscriminate, position-clearing decline that does not come along often, and it has reset a lot of crowded trades in a hurry.
Underneath it, the story driving the biggest names has not actually broken. The market is still rewarding anything with compute capacity. Owning compute right now is close to owning gold: it is scarce, it is in demand, and it commands a premium (Elon knew this with shorter term contracts) even though meeting that demand means building more capacity at steadily higher costs.
For the hyperscalers, that math works not bad. They carry the balance sheets and the low borrowing costs to keep building through a more expensive environment, so rising build costs are an inconvenience rather than an existential threat.
The picture is far less forgiving for the neocloud operators. Their model leans on heavy borrowing, and credit conditions are tightening at exactly the wrong moment. People crapped on my 2 weeks ago for talking about it, but when financing begins to freeze, the companies that depend on cheap, abundant capital feel it first. Capital - not chips, and not power alone, is increasingly the binding constraint, and that constraint is now visibly separating the players who can fund the buildout from the ones who merely want to.
Permitting and power add another layer. Tighter rules around new compute construction and grid hookups slow the pace of expansion and push costs higher still, which again favors the operators with the deepest resources and the longest runway.
There is a political dimension worth watching as well. The cost of living, and the blame directed at data-center expansion, became central themes heading into the election. With the vote now settled, the pressure that fueled that negative narrative may begin to ease. Whether the conversation pivots toward the jobs and economic benefits of the buildout - and how quickly,remains an open question, but any thaw in the rhetoric would remove an overhang that has weighed on sentiment.
For now, the setup rewards discipline. Respect the flush rather than fighting it, recognize that the compute theme itself remains intact at the top of the quality ladder, and stay mindful that the financing squeeze is doing real work beneath the surface. The names best positioned to come out ahead are the ones that can keep funding the buildout while weaker balance sheets are forced to the sidelines.
Things like memory? Not much has changed, and they sell to builders wherever they may be.
The flush clears the weak hands. I know it hurt a lot of folks but that's what comes with manias...
Have a great weekend all.
Trader63.com

That was a Doozy. In Trader63 we were long puts in QQQ, NBIS, CRWV, so we had a bit of fun this past week. But the selloff that just tore through the market has a different character than the dips of the past couple of years. This is a genuine flush- the kind of indiscriminate, position-clearing decline that does not come along often, and it has reset a lot of crowded trades in a hurry.
Underneath it, the story driving the biggest names has not actually broken. The market is still rewarding anything with compute capacity. Owning compute right now is close to owning gold: it is scarce, it is in demand, and it commands a premium (Elon knew this with shorter term contracts) even though meeting that demand means building more capacity at steadily higher costs.
For the hyperscalers, that math works not bad. They carry the balance sheets and the low borrowing costs to keep building through a more expensive environment, so rising build costs are an inconvenience rather than an existential threat.
The picture is far less forgiving for the neocloud operators. Their model leans on heavy borrowing, and credit conditions are tightening at exactly the wrong moment. People crapped on my 2 weeks ago for talking about it, but when financing begins to freeze, the companies that depend on cheap, abundant capital feel it first. Capital - not chips, and not power alone, is increasingly the binding constraint, and that constraint is now visibly separating the players who can fund the buildout from the ones who merely want to.
Permitting and power add another layer. Tighter rules around new compute construction and grid hookups slow the pace of expansion and push costs higher still, which again favors the operators with the deepest resources and the longest runway.
There is a political dimension worth watching as well. The cost of living, and the blame directed at data-center expansion, became central themes heading into the election. With the vote now settled, the pressure that fueled that negative narrative may begin to ease. Whether the conversation pivots toward the jobs and economic benefits of the buildout - and how quickly,remains an open question, but any thaw in the rhetoric would remove an overhang that has weighed on sentiment.
For now, the setup rewards discipline. Respect the flush rather than fighting it, recognize that the compute theme itself remains intact at the top of the quality ladder, and stay mindful that the financing squeeze is doing real work beneath the surface. The names best positioned to come out ahead are the ones that can keep funding the buildout while weaker balance sheets are forced to the sidelines.
Things like memory? Not much has changed, and they sell to builders wherever they may be.
The flush clears the weak hands. I know it hurt a lot of folks but that's what comes with manias...
Have a great weekend all.
Trader63.com
OptionHans retweeted
If I had to start selling options from scratch, these are the mistakes I would skip entirely.
(Nearly $1B managed in covered-call income and downside protect strategies. Lipper Award for income fund. Ivy League.)
Mistake 1: Treating premium like a cheap shot.
Premium is the price of volatility. If you don't know whether that price is cheap or expensive, you're guessing. And no, rank won't do. A VIX 25 can be cheap and a VIX 16 expensive. Yes you read that right.
Mistake 2: Selling puts on names you wouldn't own.
Cash-secured puts mean you can cover the shares if assigned. If you cannot cover assignment in cash, the size was wrong. Cliché? Ignore this and you'll be finding a new hobby sooner or later.
Mistake 3: Selling aggressively into a steeply rising VIX and or plunging stock chart.
That's running into a burning house and calling it income. Wait for the rollover. More consistent wins, less coin flipping
Mistake 4: Selling the covered call below your cost only because it "pays more." You might not be giving it enough room.There are other reasons to sell below cost, but that's not a great one. I usually sell calls above my cost and roll when I need to defend but sometimes, believe it or not, the goal is losing less and forgetting perfection.
Mistake 5: Over-buying LEAPS with fresh capital before the paycheck is banked.
Premium/income selling helps fund the LEAPS. House money only. 365 days minimum.
Skip those five and you're already ahead of most people who start selling options.
Want the free Paycheck Playbook?
playbook.trader63.com/
In a tech washout, ask who has customers and cash flow—not just a great story.
Existing compute still matters. The question is who can turn it into cash.
Want smarter income, real hedges, and out-of-the-box thinking from a 30-year pro? That's what we do all day long at trader63.com
OptionHans retweeted

Gold!

If I had to start selling options from scratch, these are the mistakes I would skip entirely.
(Nearly $1B managed in covered-call income and downside protect strategies. Lipper Award for income fund. Ivy League.)
Mistake 1: Treating premium like a cheap shot.
Premium is the price of volatility. If you don't know whether that price is cheap or expensive, you're guessing. And no, rank won't do. A VIX 25 can be cheap and a VIX 16 expensive. Yes you read that right.
Mistake 2: Selling puts on names you wouldn't own.
Cash-secured puts mean you can cover the shares if assigned. If you cannot cover assignment in cash, the size was wrong. Cliché? Ignore this and you'll be finding a new hobby sooner or later.
Mistake 3: Selling aggressively into a steeply rising VIX and or plunging stock chart.
That's running into a burning house and calling it income. Wait for the rollover. More consistent wins, less coin flipping
Mistake 4: Selling the covered call below your cost only because it "pays more." You might not be giving it enough room.There are other reasons to sell below cost, but that's not a great one. I usually sell calls above my cost and roll when I need to defend but sometimes, believe it or not, the goal is losing less and forgetting perfection.
Mistake 5: Over-buying LEAPS with fresh capital before the paycheck is banked.
Premium/income selling helps fund the LEAPS. House money only. 365 days minimum.
Skip those five and you're already ahead of most people who start selling options.
Want the free Paycheck Playbook?
playbook.trader63.com/
Long calls can lose 80–90% without a margin call.
The Leopold fund rumors aren't confirmed. But the risk lesson is real: skipping borrowed money doesn't remove the leverage inside an option.
Want smarter income, real hedges, and out-of-the-box thinking from a 30-year pro? That's what we do all day long at trader63.com
Options and LEAPS players. Sometimes the right play is no option because you’re not forcing an uncomfortable amount of capital usage into your account. Case in point:
I love $LLY. Health, aging, and AI showing up in the same company is the best of all worlds. It’s one of the great consolidations of AI + real world that you’ll find (on top of autonomous driving which can reduce road deaths by literally millions per year).
And LLY doesn’t rent the AI theme. They built the factory. LillyPod went live this year: 1,016 NVIDIA Blackwell Ultra GPUs inside a DGX SuperPOD. TuneLab lets other biotechs use models trained on Lilly data that cost more than $1 billion to generate.
Then the medicines. Foundayo (orforglipron) is the FDA-approved GLP-1 pill. Retatrutide is still in Phase 3, with a filing planned for early 2027. Those kinds of things will pay the heating bill, but the exciting mind-blowing stuff is still to come.
This is the AI application, not another chip trade. A century of experiments, the wins and the failures, sitting next to a longevity pipeline. Gonna be insane and I want to be a part of it (already am, full disclosure).
One January 2028 $1,000 strike call is still about $47,200. That is not a small-account tool. A LEAP is still a 100-share contract.
But you don’t have to force it here. Buying the stock in just the right amount, $500 or $1500…, lets you participate and not feel the pressure. Then let it happen.
Again, sometimes the trade is… no option.
Hans
Trader63.com
Options with Hans Tale of the Tape Finish Line: quantum ran the table today. QUANTUM #1 +18.41% 6/6 (IONQ +23.42%), was #7 early and #1 from midday on. SPACE #2 +11.21% 11/11 (SPCX +8.62%). NUCLEAR #3 +10.38% (OKLO +22.66%). BTC MINERS #4 +9.53%. NEOCLOUD led 7am/8:45, closed #5 +9.06% (IREN +20.02%).
builders got smoked again, last at -2.71% 0/10. CONS DISC -1.93% (DKNG -21.30%). AMD +11.04%, NVDA +2.78%, TEAM -16.15%, MCHP -10.02%. NQ +1.37%, ES +0.33%, VIX -9.05%. 20 of 31 green.
Top stories driving the board:
1. IonQ beat and raise sealed it: Q3 revenue $173.8M (+336% YoY), FY26 guide lifted to $505-515M, backlog $1.2B. QUANTUM closes #1 +18.41% 6/6, IONQ +23.42%.
2. Firefly and AST SpaceMobile inked a more than $1.3B Miranda/Vira engine deal for AST's Blacklift rocket. SPACE finishes #2 +11.21% 11/11, SPCX +8.62%.
3. Oklo's narrower Q3 loss ($0.22 vs ~$0.27) and revenue beat kept the nuclear bid alive. NUCLEAR #3 +10.38%, OKLO +22.66%.
4. chips bounced hard off thursdays rout. AMD +11.04%, NVDA +2.78%, NEOCLOUD holds #5 (IREN +20.02% on the sales beat). MCHP was the skunk at the picnic, -10.02% on a soft Dec-qtr guide and 64-65% margin outlook.
5. hot jobs left yields sticky, so BUILDERS closed last -2.71% 0/10. DKNG still -21.30% on the Predictions guide cut, TEAM -16.15% on the soft ARR outlook.
Trade with us at Trader63.com

If I had to start selling options from scratch, these are the mistakes I would skip entirely.
(Nearly $1B managed in covered-call income and downside protect strategies. Lipper Award for income fund. Ivy League.)
Mistake 1: Treating premium like a cheap shot.
Premium is the price of volatility. If you don't know whether that price is cheap or expensive, you're guessing. And no, rank won't do. A VIX 25 can be cheap and a VIX 16 expensive. Yes you read that right.
Mistake 2: Selling puts on names you wouldn't own.
Cash-secured puts mean you can cover the shares if assigned. If you cannot cover assignment in cash, the size was wrong. Cliché? Ignore this and you'll be finding a new hobby sooner or later.
Mistake 3: Selling aggressively into a steeply rising VIX and or plunging stock chart.
That's running into a burning house and calling it income. Wait for the rollover. More consistent wins, less coin flipping
Mistake 4: Selling the covered call below your cost only because it "pays more." You might not be giving it enough room.There are other reasons to sell below cost, but that's not a great one. I usually sell calls above my cost and roll when I need to defend but sometimes, believe it or not, the goal is losing less and forgetting perfection.
Mistake 5: Over-buying LEAPS with fresh capital before the paycheck is banked.
Premium/income selling helps fund the LEAPS. House money only. 365 days minimum.
Skip those five and you're already ahead of most people who start selling options.
Want the free Paycheck Playbook?
playbook.trader63.com/
A cash-secured put is a limit order that pays you to wait.
Until the stock gaps through your strike. A limit order gets a better fill in a crash. A put still buys at the strike.
Only sell puts on stocks you would buy at that price today.
Options with Hans Tale of the Tape 1351 mid-afternoon: QUANTUM still #1 +15.91% 6/6 (IONQ +18.09%, ARQQ +27.85%), NUCLEAR #2 +10.50% 9/9 (OKLO +24.06%), SPACE #3 +9.79% 11/11 (SPCX +6.87%). BTC MINERS #4 +8.77%, NEOCLOUD #5 +7.48% 12/12 (IREN +18.37%).
NVDA +3.08%, AMD +9.23%, NET +11.41%, SERV +37.94% on beat/raise. Laggards: BUILDERS last -1.87% 0/10, CONS DISC -1.64% (DKNG -23.53%), INSURANCE -1.30%; TEAM -15.24%. NQ +1.48%, ES +0.60%, VIX -12.61%, 21/31 green.
Top stories driving the board:
1. Serve Robotics crushed Q3 — revenue ~$2.84M (+313% YoY) vs ~$1.65M est, FY26 guide hiked to $12M from $9–10M; SERV +37.94%.
2. Quantum spillover: ARQQ +27.85% as peers chase IonQ/Quantinuum beats; QUANTUM #1 +15.91% 6/6. BTC MINERS #4 +8.77% as BTC reclaims ~$76K after Thursday's rout.
3. Hot jobs keep yields firm — BUILDERS last -1.87% 0/10. TEAM still -15.24% on soft ARR outlook; DKNG -23.53% keeps CONS DISC near the bottom.
Is this the bottom? My take:
VIX 25 means anything can happen day to day, but yesterday felt very flushy. A lot of stocks are down 50%. I don't think it's over for AI. Hyperscalers aren't going to stop building data centers or hunting for compute, and that takes a lot of bits and pieces.
Financing worries aren't over, but that market freezing up is the market finding balance, and yields are relaxing a bit. Earnings are great. Broadening plays look good to me, and there's a big world of companies that benefit from cheap AI. I won't rush back into pure AI, but there are names I have to own.
Nobody knows if that was the bottom. Maybe we do a little more downside probing, and on rallies I'll probably beef up hedges again. A more serious washout introduces bad things. It's a trader's market, leverage is still unwinding, there's a lot of damage, and this won't be a V bounce.
But MU from 1100 to 650 is an opportunity going into Santa season and December earnings. Maybe not, but I'm willing to accept some risk. That's what we do!
Trade with us at Trader63.com

The market is going to reward the right story and punish the wrong story again and again. Apple's still hitting highs while other Mags spend.
Want smarter income, real hedges, and out-of-the-box thinking from a 30-year pro? That's what we do all day long at trader63.com
Options with Hans Tale of the Tape 0845 pre-open: chips bounce after the rout. NEOCLOUD #1 +10.05% 12/12 (IREN +16.58%), RACK #2 +7.50%, MEMORY #3 +7.42% 9/9 (SNDK +10.48%). NVDA +4.42%, SPCX +5.57% with SPACE 11/11, NET +20.18% on its beat.
Laggards: CONS DISC last -2.28% (DKNG -26.45%), CONS DEF -2.04% 0/10, HEALTH -1.56% 0/10; TEAM -15.81%. Jobs +165K vs 59K est, 4.1% jobless. NQ +1.29%, ES +0.14%, 19/31 baskets green.
Top stories driving the board:
1. Hot October jobs: payrolls +165K vs Dow Jones 59K est, unemployment 4.1% (was 4.2%); Aug/Sep revised +84K combined. Yields jump, but NQ still +1.29% into the open.
2. AI hardware bounce holds through the print: NEOCLOUD #1 +10.05% 12/12 (IREN +16.58% on the sales beat), RACK +7.50%, MEMORY +7.42% 9/9 (SNDK +10.48%), NVDA +4.42%.
3. DraftKings deepens to -26.45% on the Predictions EBITDA guide cut ($175–275M from $700–900M), dragging CONS DISC last -2.28%. NET +20.18% still the top single-name bounce.
Trade with us at Trader63.com

Options with Hans Tale of the Tape 0800 early premarket: chip bounce ahead of jobs. NEOCLOUD #1 +8.96% 12/12 (IREN +15.75% on beat), RACK #2 +6.64% 7/7, OPTICAL #3 +6.52%, MEMORY +6.46% (SNDK +9.60%). NVDA +4.13%, SPCX +4.52% in SPACE, NET +18.63%.
Laggards: CONS DISC last -2.08% (DKNG -24.20% guide cut), CONS DEF -2.03% 0/10, HEALTH -1.54%; TEAM -15.39%. NQ +1.30%, ES +0.07%, 18/31 green.
Top stories driving the board:
1. AI hardware snaps back after Thursday's wipeout: NEOCLOUD #1 on IREN's sales beat ($228M vs ~$221M est.); RACK, OPTICAL and MEMORY all up 6%+.
2. Cloudflare crushed Q3: revenue $782.5M (+39% YoY, fastest in ~4 years) and raised its 2026 outlook; NET +18.63%.
3. DraftKings slashed its FY26 adj. EBITDA guide to $175–275M from $700–900M; DKNG -24.20% drags CONS DISC last. TEAM -15.39% on a softer subscription outlook.
Trade with us at Trader63.com
