
Equity Analyst researching high-quality companies at Best Anchor Stocks and Invirtiendo en Calidad. Spanish account: @InvEnCalidad
Madrid, Spain
Joined November 2020
- Tweets32.7K
- Following998
- Followers58.4K
- Likes47.6K





Pinned Tweet
In-depth reports I have published on S*stack so far...
- Deere $DE (free)
- FRP Holdings $FRPH
- Five Below $FIVE
- Diageo $DEO
- Hermès $HESAY
- Atlas Copco $ATCO.B
- Stevanato $STVN (free)
- Keysight $KEYS
- Zoetis $ZTS
- Judges Scientific $JDG.L
- Medpace $MEDP
- Trupanion $TRUP
- AAON $AAON
- BBB Foods $TBBB
- Eurofins $ERF
- Sabre $SABR
- Rosebank Industries $ROSE
- Undisclosed position
- Wide variety of in-depth industry reports
Currently looking into several other opportunities that might see the light soon.
The library will keep getting longer!
Subscribe: bestanchorstocks.com


Copart $CPRT new CEO pay package looks on the surface like textbook alignment, but there are some caveats.
The structure is basically...
- Jay Adair takes a $1 salary, no bonus and no new equity for 10 years.
- He gets instead one 20M-share option in four tranches, with strikes at $26.27, $35.03, $43.78 and $52.54. The option has a 5-year cliff, a clawback if he leaves early, and his gains are locked up until year 10.
So basically...
- Stock flat → he earns $0.
- Stock 2x → he earns ~$263M.
My "concern" is the timing of the option issue, which evidently impacts the existing holders more than it does the recent holders.
Jay Adair came back as CEO on July 31, with the stock near multi-year lows around $28, down from ~$52 in mid-2025. The strikes are anchored to the depressed price in which he (opportunistically?) became CEO.
This ultimately means that...
- Tranche 1 pays on any rebound, so many shareholders might still be underwater while he makes millions (this has no simple solution as setting the bar at ATH would also not be fair)
- The “ambitious” top strike of $52.54 is roughly where the stock already traded in 2025...
- “Doubling the stock” mostly means getting back to where it was without any new value creation
- Over 10 years, a 2x is roughly ~7% a year
Now, a founder-family CEO taking $1 and betting everything on the stock is rare and definitely better than nothing, but the design matters too and reality is more nuanced than it appears.
As designed, Jay Adair could earn hundreds of millions simply by returning Copart to where it was before he came back.
Still subject to shareholder approval!

To those claiming that what has happened to the stock in the past in not Jay Adair's fault and therefore that info shouldn't be taken into account...
I somewhat agree yes, I wrote it down in the post as well. Also worth considering he was in the board all throughout and therefore not entirely isolated from the business
All that said, this comp ultimately means that if the stock compounds at a 7% clip for a decade, he gets around $250 million. That's around $25 million per year and now it's up for anyone to judge whether that's reasonable or not for a 7% CAGR
Don't know what hurts more when owning a cyclical biz...
1. Seeing the stock continue to drop while fundamentals continue to do poorly
2. Seeing the stock start to peak while fundamentals continue to do great
😅

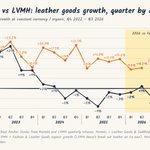
Pretty decent earnings from Hermès considering the circumstances, to be honest
- Q3 organic growth +4.3%
- 9M organic growth +5.5%
- Middle east, China, and France a bit challenged
The most impressive number imho is leather, +10% organic in an environment where "peers" are struggling. Seems relevant because it's the metier the company controls the most and probably the "core" of the thesis
Before anyone says...
"You are paying (insert valuation metric here) for 4% growth"
I actually think this portrays what you are paying for. You are ultimately paying for MSD growth when very few in the industry are growing (+ obviously a bit less upside when things start booming)
$HERM.NE $RMS.PA


Currently looking at a company whose CEO said that they must set ambitious targets for employees to remain motivated (“shoot for the moon and even if you miss you’ll land in the stars”)
Has worked well for them (25% CAGR over 15 years) but dangerous game in financial markets. You can always set internal goals that are different to those shared with the market but are employees going to be equally motivated?
Tough to answer but the strategy has historically worked for Elon and one can’t deny that his companies likely would not have achieved what they achieved without this strategy
$SPCX $TSLA


Okay so interesting I am being called out publicly (never a fan of a reply being quoted to show off) by someone who doesn’t really understand what Judges does
A good chunk of Judges’ EBIT is unrelated to healthcare and the drivers of its sales are very different to those of Bruker, TMO etc. A good portion of the business is related to scientific discovery (which DHR, TMO et al have been quoting as pretty weak due to funding cuts) so one can’t say that the company is losing share just be comparing these businesses apples to apples.
Then you also have the problems with the Geotek coring contract, which are non-healthcare (surprise)
You can like or not like Judges but claiming that “sales will be down by 15% in 2026” while clearly not understanding the business is not a great look. It’s a cyclical biz that has suffered plenty of headwinds, it’s not a healthcare biz losing share to peers that have little in common with it

You're so far off @Invesquotes. I hope this isn't one of your holdings.
Sales will be down 15% in 2026. No recovery in sight.
Its performance is much worse than that of its peers (H1 organic sales: -13% vs Bruker, Thermo Fisher, Agilent, and Waters all much better). Management has also talked about businesses experiencing product-specific challenges. AKA loosing market share.
There's a reason why the stock is down.
Judges Scientific focuses on laboratory, materials testing, and vacuum engineering systems. Most funds classify it under healthcare due to the large portion related to Life Sciences Tools & Services. It may be classified officially under tech or general industrials, but its end markets are mostly healthcare.
That's how it is done in the industry, sell-sides pitching me the stock or my investment team had it in healthcare...


Leandro retweeted

Nintendo says Zelda: Ocarina of Time is "a global phenomenon" with sell-outs "absolutely everywhere," did "extremely well" in the U.S., talks 40th Anniversary Edition Switch 2 restock nintendoeverything.com/ninte…
