If my Bitcoin has to outlast me, I take a smaller withdrawal.
In the Observatory's study, over 100 years with spending rising 7% a year, the 99%-reliable withdrawal from 1 BTC started in a bear fell to $16k a year.
Longer horizon, smaller draw.
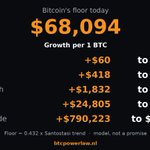
Bitcoin's floor is $68,094 today. Growth per 1 BTC:
Next day: +$60, to $68,154
Next week: +$418, to $68,512
Next month: +$1,832, to $69,926
Next year: +$24,805, to $92,899
Next decade: +$790,223, to $858,317
Floor is 0.432 x the Santostasi trend. Model, not a promise.
The test used daily closes and liquidation at 80% LTV, and the floor isn't guaranteed. Borrowing has real risk. Borrow small.
btcpowerlaw.nl/research/1-6x…
The Observatory's 1.6x rule ties it to the floor. At 40% loan-to-value, you can start a loan with price up to 2.00x the floor. At 50%, up to 1.60x. At 60%, only 1.33x.
Say a bear market hits, you need $8,000 to live on, and you'd rather borrow against your coins than sell them cheap.
How big a loan?
It isn't smooth. Some years the low fell. And growth from one cycle bottom to the next has been slowing.
Say you buy $50 of Bitcoin every week and the only price you care about is the worst one you pay each year.
If you buy 1 bitcoin today at 80K you can be pissed off that it’s only worth 460K 8 years from now.
Minimum.
My good friend Monte Carlo and I ran Bitcoin out to 2034. 5,000 times 🎲
Not one run ended below today's $80K.
The median finish: $1.48M 🚀
- - -
Each line on the chart is one run, and the pink curve on the right shows the final distribution in 2034. Even the bottom 5% finish around $464K, almost 6x from here.
He's very optimistic, and honestly so am I 😄
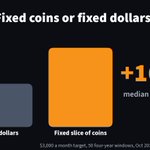
Say you need $3,000 a month in retirement and must choose: sell a fixed dollar amount each month, or a fixed slice of your coins.
Fixed dollars force you to sell more coins when price is low. A fixed slice sells the same coins in a crash as in a boom.
Part of the gap is fixed-dollar stacks running out early.
The trade-off: income swings month to month, and the fixed slice spends the whole stack over 4 years, by design.
satsplanner.com/retire/
At my budget, I don't hold cash back for dips.
At $1,000 a month, none of the Observatory's smarter strategies showed a statistically solid edge over plain DCA. One's range ran from -60% to +219%.
Idle cash costs more than bad entries.
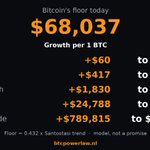
Bitcoin's floor is $68,037 today. Growth per 1 BTC:
Next day: +$60, to $68,096
Next week: +$417, to $68,454
Next month: +$1,830, to $69,867
Next year: +$24,788, to $92,825
Next decade: +$789,815, to $857,852
Floor is 0.432 x the Santostasi trend. Model, not a promise.
I don't need the floor to be exactly right.
The Observatory's floor page says that even if the floor sits 20% lower than measured, the growth rate is what matters for long-term planning.
So I size my plan as if it were 20% lower. If it isn't, I'm ahead.
btcpowerlaw.nl/floor/