

DeFi Researcher | Dune Wizard 🧙
Singapore
Joined November 2022
- Tweets3.9K
- Following569
- Followers2.5K
- Likes3.5K




Pinned Tweet
1.61% Bitcoin yield could be worth more than a 10% headline APY.
A recent report from Pareto highlights a good example of this.
One Bitcoin yield strategy reached around 10% APY, largely driven by temporary token incentives. Once those incentives end, the headline yield can drop sharply.
That's the problem with strategies that rely heavily on incentives. APYs can look attractive in the short term, but those returns can change quickly once the subsidies run out.
Now look at @paretocredit x @Two_Prime Axiom WBTC Vault, it currently offers around 1.61% net APY, paid directly in WBTC.
The key difference is where the yield comes from.
Institutions borrow Bitcoin for trading, financing, and liquidity management. They pay interest on those loans, and part of that revenue flows back to lenders through the vault.
There's also a credit structure behind that yield.
Two Prime puts up 150 WBTC of its own capital as first-loss protection, alongside monthly lending cycles and a Credit Agreement covering lender rights and recovery procedures.
Of course, credit yield still comes with default risk, and the 1.61% APY isn't guaranteed.
But for long-term Bitcoin holders, I think this is a different way to look at yield.
If your goal is to accumulate more Bitcoin over the years, how sustainable that yield is matters just as much as the headline APY.
Rather than chasing the highest number, I'd pay more attention to three things:
Who's actually paying the yield?
How long can that borrowing demand last?
What protects lenders' capital when losses occur?
That's why I think the Axiom WBTC Vault is worth a closer look.


Mahone Defi retweeted

ngl, this report gave me a much deeper understanding of tokenized stocks onchain.
There are plenty of valuable findings, but a few insights from @redstone_defi really stood out to me:
1. Perps are still where stocks actually trade
One of the biggest takeaways from RedStone's report is how much equity perp trading dominates the market.
Equity perp volume is roughly 9.9x higher than tokenized stock spot volume.
Even with tokenized stocks surpassing $3B, most onchain trading activity still happens through derivatives rather than spot tokens.
For now, traders seem to value the leverage and liquidity of perps more than holding tokenized shares.
2. After-hours trading is a clear advantage
Around 55% of tokenized stock trading volume happens outside traditional market hours.
Even more impressive, Sunday evening perp prices correctly predicted the direction of Monday's market open around 65% of the time in RedStone's sample.
This is one of the clearest examples of the real utility crypto infrastructure brings to tokenized equities.
3. The defi gap remains huge
Only 2.6% of tokenized stocks are actually being used in DeFi, despite 42% of the supply being technically eligible as collateral.
Most of the collateral usage comes from a handful of smaller markets, while assets from larger issuers barely see meaningful borrowing activity.
This suggests there's still a massive gap between making tokenized stocks available in DeFi and generating real demand for them as collateral.
4. Liquidity and actual ownership are highly fragmented
There are roughly 4.04M holders, but the average balance is only around $780.
Most positions are small, retail-sized holdings concentrated across a limited number of venues.
Meanwhile, many large balances sit in issuer wallets and exchange hot wallets rather than individual investor wallets.
Another detail worth noting: the three largest issuers, accounting for roughly 70% of the market, don't provide direct equity ownership.
Instead, holders typically receive indirect economic exposure or claims backed by underlying shares.
---
The full report goes much deeper into market structure, trading behavior, liquidity fragmentation, and the DeFi adoption gap that RedStone has identified.
If you want to explore the full data and analysis, I'd recommend checking out the report below.


Tokenized stocks total $3.17B+ in onchain value.
Only 2.6% of that is used in DeFi.
Read our latest report with @FourPillarsFP and @AleaResearch, revealed at @TokenizeThisNYC Singapore edition, to learn why.
Features insights from: @Securitize, @DinariGlobal, @SuperstateInc, @extendedapp, @lista_dao, @JupiterExchange, @CredoraNetwork.
Mahone Defi retweeted
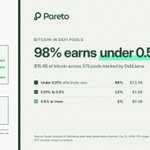
imo, one of the most valuable insights from @paretocredit's article is that most real Bitcoin borrowing demand sits in the OTC market, where hedge funds, prime brokers, and financial institutions borrow Bitcoin to support their operations.
Onchain, Bitcoin is mostly used as collateral, leaving lending rates close to zero.
This gap is exactly what credit products like Pareto x Two Prime aim to address, bringing offchain institutional borrowing demand onchain through a more structured credit model.
So what makes this Bitcoin Credit product different from traditional OTC lending and existing onchain markets?
1. Yield backed by institutional credit demand
The vault currently offers around 1.61% net APY, paid in $WBTC.
That's significantly higher than most onchain Bitcoin lending pools, where limited borrowing demand keeps rates near zero.
More importantly, the yield comes from interest paid by institutional borrowers rather than relying on token incentives.
2. Credit structure designed for institutional lending
Rather than operating as a typical lending pool, Pareto structures the vault as a credit facility with defined risk controls.
@Two_Prime puts up 150 WBTC of its own capital as first-loss protection, absorbing credit losses before they reach lenders.
The vault also has monthly redemption cycles and a Credit Agreement outlining lender rights and recovery procedures.
This follows the hybrid onchain + offchain model that Pareto has already demonstrated across its previous Credit Vaults.
3. A new access channel for institutional Bitcoin credit
The product opens institutional Bitcoin credit exposure to eligible lenders holding capital onchain.
Previously, accessing OTC lending opportunities often required direct institutional relationships, with limited flexibility around participation.
By bringing this exposure onchain, Pareto creates another channel for capital allocation beyond traditional OTC relationships.
4. The composability potential of $pAXIOMBTC
For me, this is the strongest advantage of bringing Bitcoin credit onchain.
Unlike traditional OTC positions, the vault's receipt token can potentially be integrated into secondary markets, money markets, or more complex structured DeFi products.
That opens the door for the same Bitcoin credit exposure to gain additional liquidity, distribution, and utility across DeFi.

Mahone Defi retweeted
11 Aave markets ended Q3 with $1.3B+ in deposits and $417M borrowed.
Across V3 and V4, @aave expanded into new chains, consumer credit, and different lending structures.
A few things stood out to me 🧵


Mahone Defi retweeted
My take on the partnership between @redstone_defi and @Brickken:
1. T+0 settlements via Settle could bring the most value to Brickken's ecosystem.
Price feeds and credit ratings are offered by multiple providers, but turning T+N settlement into T+0 liquidity addresses one of RWA's biggest pain points.
Brickken has supported over $660M in tokenized assets, spanning equity, real estate, and energy. Many of these asset classes are traditionally illiquid, with lengthy redemption cycles.
RedStone Settle uses solvers to provide immediate liquidity, while solvers take over the positions and handle redemption.
If executed well, this could unlock more Brickken assets as collateral in defi lending markets.
2. Expanding agent-ready RWAs on Brickken
Brickken already offers APIs, an MCP server, and SDKs that allow AI agents to interact with tokenized assets.
RedStone adds three key infrastructure components:
- Pricing to determine asset valuations.
- @CredoraNetwork to assess credit risk.
- Settle to support exits and liquidations.
Together, these components could help AI agents move beyond executing transactions toward managing RWA positions autonomously.
3. An institutional moat is taking shape
RedStone is expanding vertically across pricing, risk, and settlement rather than competing solely as an oracle provider.
Through Brickken, RedStone gains an opportunity to integrate all three layers with asset issuers from the tokenization stage.
As issuers and lending markets adopt the full stack, switching costs could rise, making the infrastructure harder to replace.
imo, that's where RedStone's long-term institutional moat could emerge, with Settle as its strongest differentiator.

NEW: @Brickken, a tokenization platform with 150+ clients and $660M in tokenized assets, has selected RedStone as its data infrastructure partner.
Brickken-issued assets can now access the full RedStone stack: feeds, T+0 settlement via Settle, and @CredoraNetwork risk ratings, the data layer to enable work in DeFi for RWA's.

Mahone Defi retweeted
Tokenized stocks on @base are finding more use cases in DeFi.
3% USDC incentives to boost tokenized stock deposits on @aave V4
$1.2M in collateral from @superformxyz, bringing automated carry trade strategies to retail users.
🧵,


Aave DAO has approved incentives for the Coinbase Tokenized Stocks market on @base.
Tokenized stocks are only available in eligible jurisdictions outside of the U.S.

Mahone Defi retweeted

By March 2026, tokenized RWAs had grown more than 5x in a year, with private credit alone at ~$4.6B.
Yet only ~$2.8B of the ~$28.6B market was deployed in DeFi.
New research from @LaserDigital_ points to four structural risks behind that gap.
🧵⬇️

Only around $2.8bn of a roughly $28.6bn tokenised RWA market is deployed in DeFi. Our new research on what institutional fixed income needs on-chain: laserdigital.com/latest-insi…
Professional and institutional investors only. Capital at risk. laserdigital.com/marketing-d…


Mahone Defi retweeted

Pretty comprehensive report dropped by @redstone_defi x @FourPillarsFP x @AleaResearch at @TokenizeThisNYC SG around the current state of tokenised stocks.
Beyond the headline figures, the report dives into the evolving market structures, issuer dynamics + the growing role of DeFi in shaping onchain equity markets.
Here are some key takeaways I found particularly interesting 🧵

Tokenized stocks total $3.17B+ in onchain value.
Only 2.6% of that is used in DeFi.
Read our latest report with @FourPillarsFP and @AleaResearch, revealed at @TokenizeThisNYC Singapore edition, to learn why.
Features insights from: @Securitize, @DinariGlobal, @SuperstateInc, @extendedapp, @lista_dao, @JupiterExchange, @CredoraNetwork.

Mahone Defi retweeted
ngl, keeping up with hundreds of sanctions lists is a headache for defi teams.
so @redstone_defi built a Sanctions Oracle that lets protocols screen wallet addresses against 463 sources covering OFAC, UN, EU, and other sanctions lists through a single onchain check.
protocols can query the oracle during a transaction and revert if an address is flagged, embedding sanctions screening directly into the execution flow.
updates are pushed onchain weekly with a timestamp, so protocols can set limits on how old the screening data can be.
the contract also uses the same interface as Chainalysis’ sanctions oracle, simplifying integration for protocols already using that interface.
potential use cases include:
- stablecoin issuers
- tokenized funds
- lending protocols
- permissioned pools
imo, the key shift is making sanctions screening part of how a protocol operates.
for institutional, that means access rules can be enforced directly by smart contracts at execution time.


Mahone Defi retweeted
Downside protection matters, especially when institutional bitcoin is earning yield.
In the Two Prime Credit Vault on Pareto, 150 WBTC of @Two_Prime's own capital sits in first loss.
Backed by a clean record across 3,000+ BTC lent.
app.pareto.credit/vault/0xD1…


Mahone Defi retweeted
Aave V4 is starting to look like a market factory.
$1.38B in deposits and nearly $420M in active loans are impressive, but the more important story is V4's expansion into different types of credit markets.
🧵,

Mahone Defi retweeted
I think the Pendle Effect is one of the few patterns in DeFi that actually keeps repeating.
Every time a stable or yield-bearing asset gets a PT/YT market, demand doesn’t just tick up, it concentrates.
- Ethena had roughly half its TVL sitting on @pendle_fi at the peak.
- USDG went from zero to Pendle being the largest holder on Ethereum in under two months.
- On Monad, Pendle accounted for more than 78% of AUSD supply.That’s not a marketing line.
Issuers get distribution, users get a fixed rate, and the token gets a second life as collateral.


Mahone Defi retweeted
Serotonin’s article is one of the better deep dives into how @paretocredit is building an onchain credit marketplace for institutions.
Here are a few insights from the piece that still hold up today:
1. Pareto is filling a gap that Aave and Morpho don’t really address
Most major money markets are built around over-collateralized lending.
Institutions like prime brokers, prop trading firms, and crypto funds often need under-collateralized credit lines with customized terms.
Pareto’s Credit Vaults are designed for exactly that.
The smart contract acts more like a credit facility, with predefined lending cycles, interest rates, and redemption windows.
It is closer to "real credit" than a typical DeFi lending pool.
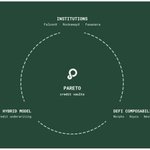
2. The hybrid onchain + offchain model is actually practical
Onchain: vaults, lending cycles, redemption windows, and callbacks for early exits when the borrower agrees.
Offchain: due diligence, loan structuring, monitoring, and reporting.
For example, the @FalconXGlobal vault has M11 Credit handling much of the credit underwriting and operational side.
That structure makes it possible to onboard names like FalconX, @RockawayX, and @FasanaraDigital instead of limiting the market to retail DeFi borrowers.
3. DeFi composability is an important part of the thesis
The FalconX vault receipt token, AA_FalconXUSDC, is already being used as collateral in Morpho markets curated by Gauntlet to build leveraged credit strategies.
The same exposure is now being risk-tranched through @roycoprotocol and also serves as a core underlying asset for nALPHA on @NestCredit x Plume.
If this thesis keeps expanding, Pareto’s moat may come from becoming the infrastructure layer that connects institutional credit with the rest of DeFi.


Mahone Defi retweeted
.@MahoneDeFi breaks down @serotonin_hq's take on Pareto

Serotonin’s article is one of the better deep dives into how @paretocredit is building an onchain credit marketplace for institutions.
Here are a few insights from the piece that still hold up today:
1. Pareto is filling a gap that Aave and Morpho don’t really address
Most major money markets are built around over-collateralized lending.
Institutions like prime brokers, prop trading firms, and crypto funds often need under-collateralized credit lines with customized terms.
Pareto’s Credit Vaults are designed for exactly that.
The smart contract acts more like a credit facility, with predefined lending cycles, interest rates, and redemption windows.
It is closer to "real credit" than a typical DeFi lending pool.
2. The hybrid onchain + offchain model is actually practical
Onchain: vaults, lending cycles, redemption windows, and callbacks for early exits when the borrower agrees.
Offchain: due diligence, loan structuring, monitoring, and reporting.
For example, the @FalconXGlobal vault has M11 Credit handling much of the credit underwriting and operational side.
That structure makes it possible to onboard names like FalconX, @RockawayX, and @FasanaraDigital instead of limiting the market to retail DeFi borrowers.
3. DeFi composability is an important part of the thesis
The FalconX vault receipt token, AA_FalconXUSDC, is already being used as collateral in Morpho markets curated by Gauntlet to build leveraged credit strategies.
The same exposure is now being risk-tranched through @roycoprotocol and also serves as a core underlying asset for nALPHA on @NestCredit x Plume.
If this thesis keeps expanding, Pareto’s moat may come from becoming the infrastructure layer that connects institutional credit with the rest of DeFi.
Mahone Defi retweeted
OTC Desk on Pareto | Potential use case #2
Up to $1B in daily liquidity - that's @grovedotfinance Basin, bridging settlement gaps for tokenized RWAs.
Capital at that scale deserves to earn even while on standby.
OTC Desk on Pareto makes it possible.
🧵⬇️

Mahone Defi retweeted
imo the framing makes sense.
@symbioticfi Liquid Lane’s idle USDC between exits is usually parked in Aave, Morpho, or 3F.
Allocating a portion to @paretocredit’s OTC Desk to buy Credit Vault positions at a discount is a way to earn additional yield.
As long as the allocation stays small enough that the next withdrawal doesn’t depend on finding another buyer.
DeFi 🤝 RWA

OTC Desk on Pareto | Potential use case #1
@symbioticfi Liquid Lane gives RWA holders instant USDC exit, paid out of Symbiotic vaults.
Between exits, that capital earns yield in lending markets.
OTC Desk on Pareto takes it to the next level to maximize returns.
🧵⬇️
