






All $SIVE holders like this post to convince @aleabitoreddit and @SiversSemicond to take Serenity on Sivers board.

Bro you said in past management is doing fine so you don’t need to be on board
But now it seems the right time.
Your joining Sivers alone will be highly bullish for $SIVE
YOU ALL AGREE? Please like this post to convince @aleabitoreddit and @SiversSemicond
Sivers holders are you still bullish
Let the bears know
I am still bullish for 2027
$SIVE will break the previous record
Hands up $SIVE holders
Where are all the $SIVE holders?
When I used to post, I was getting way more impressions. Now the market is down and everyone seems to have disappeared.
Are you still here?
Patience will pay.
We need more activity on X now. The market sentiment is already starting to turn, #Anthropic IPO is coming, and bullish news could be just around the corner.
$SIVE can get back to where it was before - even €10+.
Don’t blink.
AI stocks aren’t going anywhere.
A new bill is coming to FAST-TRACK AI data centre expansion.
No more bans can stop AI.
Fasten your seatbelts for another 5x to 10x move in $SIVE from these levels.
Any major laser contracts from Sivers will quieten the noise.
$SIVE $AAOI $LITE $MRVL $AXTI

Here is retail logic
$AXTI at $140 …..what’s next $AXTI
$AXTI at $38 …… Market is getting dumped SELL
$SIVE at $10 usd ….. what’s next $SIVE
$SIVE at $1.5 usd …. SELL
$SIVE is the next $SIVE and next $LITE
I’ll wait for this moonshot to run to $50 USD
Retail logic: buy at $10 and sell at $1.50
Buy high sell low
Everyone’s a long term investor for 2027, 2028, or 2029 onward
Until their portfolio experiences volatility months in. I still think:
- $RKLB could end up the next $SPCX
- $NBIS has the potential to be the next hyperscaler
- $SIVE has moonshot potential to be the next $LITE
- 1-3x P/E memory companies and $AXTI substrate bottlenecks are more durable than markets think
And that it’s stupid to sell single digit fwd P/E AI companies or promising longs.
And rotate that into 5% growth towel resellers at 47x P/E. Or 180x cyber companies, just because they’re going up.
I’ve seen $AMD go from the $3 valley of doom to $400 as people thought it could be the next $INTC / $NVDA.
And been through the Bitcoin $1000 -> $18,000 -> $3000 -> $100,000 cycle.
Not advice on how to position or trade, but anyone on extreme leverage during those times got wiped out.
While the underlying assets sharply recovered later.
I do think AI, Space, and Physical AI are the future.
So, I’m remaining long, and using this time to maximize exposure to the winners
According to TrendForce’s latest report, the 2027 CPO mass-production bottleneck is photonic packaging.
CPO and NPO optical-engine shipments are forecast to reach 62.86 million units in 2028, approximately 18x the 2027 level.
This is bullish for the entire optical supply chain, particularly InP laser manufacturers.
More optical engines mean greater potential demand for reliable, high-performance laser sources.
$SIVE is developing capacity for 100M lasers annually, targeting Q4 2027.
If TrendForce’s forecast materialises, the timing could be significant for Sivers.

Sivers Semiconductors is exhibiting at MWC Barcelona 2027, taking place from 1–4 March 2027.
You can find Sivers at Stand 5E1.
MWC is one of the world’s leading connectivity and technology events, bringing together major global companies across AI, telecoms, networking and digital infrastructure.
The 2027 sponsor lineup includes major names such as KPMG, Infosys, Palo Alto Networks, Accenture and Tech Mahindra.
A great opportunity for Sivers to showcase its technology and connect with the global technology ecosystem.
#MWC27 $SIVE


Do these Democrats have any idea what they are talking about?
It sounds like they are illiterate, with no knowledge of AI. AI wasn’t invented by Trump, he just gave it a new name Artificial Superintelligence.
If the US slows down or bans AI, China won’t slow down, and the US will be left further behind the rest of the world.
@JensenHuang Democrats need a lecture about AI from you, $NVDA $GOOG and all Hyperscalers didn’t spend trillions on AI to get it I banned
$SIVE $NVDA $AAOI $LITE $AXTI $MRVL

Casino or stock market investment?
It makes me laugh. Is it the stock market or a casino?
$SIVE went from under $1 USD to $10 USD with just $JBL and $GFS partnership news.
@SiversSemicond is expanding its foundry with capacity for 100M lasers in Q4, and the stock is down from $10 USD to under $2 USD.
What if $SIVE announces tomorrow that its 100M lasers are sold out for $1B USD?
Will $SIVE hit 50 cents or $20 USD?
If it is an investment, I expect $20 USD. If it is a casino, then 50 cents, like it is happening now.

Laser demand is accelerating as AI data centres, optical networks and high-speed connectivity scale
Demand outstripping supply is creating a powerful opportunity for $SIVE and $AAOI
🤖 Made with AI

For companies like $SIVE / $AAOI, the demand imbalance for lasers are so severe
That even a 20-30% overall demand reduction from a hypothetical DC slowdown would likely not eliminate the shortage.
We're seeing this before the next architectural shifts, where $NVDA Jensen Huang expects 15x optical volume for CPO scale-up.
And as more hyperscalers commit to NPO as seen with $LITE new $5B UHP laser contracts.
I'd argue this is more nuanced since I can't say the same for finished 800G/1.6T pluggables or lower end 70mW-100mW laser ranges that are currently bottlenecks.
But this argument is more toward higher spec lasers.
$AAOI is vertically integrated and has 300-400 mW capabilities, so they have the capability to shift attention to merchant lasers over supplying end-to-end optical transceivers.
$SIVE is more pure play on this laser bottleneck, but they have the capabilities for 200mW + higher margin multiwavelength NPO/CPO lasers.
I'd argue this is specifically the case for bottlenecks where demand imbalances are so deep (creating higher long term visibility, such as HBM).
Whether it's large body substrates from $ATS that's bottlenecking Marvell + $AMD or lasers from $LITE that are sold out into 2029.
or liquid transformers that have 4-5 year lead times.
They they would still sell out of capacity even if overall demand decreased.
If markets de-risked, it would make sense to hit optical module manufacturing players, maybe server rack assembly, to companies that still require heavy financing like Neoclouds.
And obviously haircut growth valuations (but not to the point where demand collapses to 0).
Yet we're seeing everything in AI trade is getting lumped up together as something that requires heavy financing + not profitable.
This is the best advice if you have conviction. Just $HODL.
Who else is $HODLING with me?
Shoutout to all Siverers or Survivors. lol
I own $SIVE through all this noise and will keep holding until I see all the catalysts.
All semis have been hit hard, from $LITE and $MRVL to $AAOI and $AXTI.
Not worried a bit.
If $SIVE goes back to 4 SEK or 40 cents, don’t you think everyone will start buying like crazy and it will go back to ATH with another wave of hype?
OR
@SiversSemicond announces new partnerships and @Broadcom $AVGO locks in a major laser supply deal with Sivers.
We’ll find out soon what triggers $SIVE back to $10 or $20.
The next move higher will be epic.

When you are bored and want to do @aleabitoreddit research on $SIVE
“IMO, $SIVE ends up as a $10B+ company next year, especially if they follow what $LITE / $COHR did with downstream IP integration to capture more of CPO module BOM.”
$SIVE could become a $10B+ company next year.
At a $10B market cap, that would imply a share price of approximately $30.15 USD
I believe it could have reached that market cap this year, but the broader semiconductor sell-off and macroeconomic headwinds have held back its full potential.
The opportunity in AI optical connectivity and laser supply is still developing. I believe the market could eventually recognise the scale of what Sivers is building.
$LITE $MRVL $SIVE $AAOI $COHR
I'm still laughing how much Swedish hate their own frontier companies so much.
That they write hit pieces every day on $SIVE.
This one was entertaining: Local journalists show up to an empty $SIVE administrative building uninvited.
Because they can't fathom the CEO is in Silicon Valley or design team is working on US Gov CHIPS act dev in the US. And because there weren't many cars parked outside + CFO wouldn't take questions about secretive hyperscaler deal financials.
They wrote a random negative hit piece.
By repeating "There are several who make lasers like these and Sivers are far from alone".
Several like $LITE, $COHR, $60B+ companies.
and reported earlier that "CPO is nothing special, it's been around for years."
While GS projects CPO going from $1B -> $91B TAM over the next two years.
Even put "Plans" in quotation marks because they didn't think Sivers is supplying lasers to $JBL 1.6T LRO.
IMO, $SIVE ends up as a $10B+ company next year, especially if they follow what $LITE / $COHR did with downstream IP integration to capture more of CPO module BOM.
Just don't think Swedish people understand hyperscaler supply chains, concept of forward growth, or the fact that employee count doesn't equate to revenue.
Transfer of control from local Swedish -> West is always appreciated, as this was a majority owned local retail company before.


We could see similar news involving $CRDO and $AVGO securing laser supply through a partnership with $SIVE.
As AI infrastructure scales, securing reliable laser supply ahead of competitors could become a major strategic advantage. No hyperscaler or optical player wants to be left fighting for capacity once the bottleneck tightens.
It would make sense to secure supply in advance rather than wait for another hyperscaler to approach Sivers directly.
@SiversSemicond, we’re waiting for the news. These are the kinds of strategic partnerships the market should be watching for.
@Broadcom
$SIVE $CRDO $AVGO $NVDA $MRVL $LITE


I feel investors will be kicking themselves for not owning laser supply-chain stocks like $SIVE.
Imagine a major pluggable manufacturer or hyperscaler securing a 100M-laser supply agreement with Sivers. That kind of announcement could trigger a massive rerating and potentially send $SIVE past its previous ATH.
$SIVE $AVGO $NVDA $MRVL $LITE $AAOI $COHR
Following the Lumentum / Marvell deal:
My opinion is that independent Western laser players, like $AAOI, $COHR, and $SIVE became a lot more strategically valuable.
$MTSI and $SMTC should get some attention too as emerging laser players in 2027.
If I had to guess:
1. Companies competing against Marvell, or not in the $NVDA ecosystem bandwagon, such as $AMD, are likely going to rethink their relationship with $LITE.
If getting bottlenecked by Nvidia capacity agreements wasn't enough... Incentives around qualifying + bringing up other laser players, seems very necessary now.
Since you generally don't want competitors like Marvell to have influence or visibility over your roadmaps, IP, capacity, pricing, etc. even if there is a "firewall".
2. $MRVL acquiring Lumentum opened pandoras box in a way of acquiring a critical chokepoint all your competitors + buyers use.
$LITE was used by your major hyperscalers and across AI supply chains.
Now, your leaders might wonder if weaponizing capacity agreements might not be as effective.... If someone else can just buy the entire company.
There's only a few major public merchant Western players out there, and I'm also sure many others will want to follow the Marvell / Broadcom route via vertical integration, given I think $MRVL saves around $1B+ in costs/year.
So M&A premiums likely went up.
$SMTC was actively looking to buy laser capacity via M&A so I'm sure they're looking at $SIVE given their 100M CW DFB laser expansion + tiny MC.
$JBL also probably wants to vertically integrate down the road too so $SIVE is also an acquisition target for their 1.6T program.
$AMD was looking for ELSFP + CW capacity given Nvidia bottlenecks, so I'm sure they've looked at $AAOI.
can go on and on about other ASIC players (like in Taiwan) that likely are looking at vertical integration too.
Since multiple players use a small subset of laser suppliers, if competitors just go ahead and buys them...
There's a lot pressure to M&A for their own supply chain defensibility.
TLDR: Independent laser suppliers should capture a material strategic revaluation since $MRVL + $LITE, sets a new precedent + implications.
We'll see what happens.
$MRVL just made a ~$115B bet on the future of AI infrastructure, agreeing to acquire $LITE in an all-stock deal.
Marvell CEO Matt Murphy calls this “an opportunity that comes along once in a generation”.
Copper is reaching its limits as AI datacentres demand ever-increasing bandwidth.
The industry needs optical connectivity, more lasers and greater capacity.
This infrastructure shift could create a huge opportunity for $SIVE. As copper gives way to optics, laser suppliers could become increasingly strategic.
The optical transition may only be getting started.
$SIVE $MRVL $LITE $AVGO $NVDA
Funny how people keep saying “AI is over” when it looks like the AI infrastructure buildout is only just getting started.
Amazon, Google, Meta and Microsoft reportedly spent a record $201.9 billion on CapEx in Q3 2026 alone.
That is more than double the level of a year ago, with another $232 billion in planned Q4 spending.
The money is going into datacentres, computing power, networking and the infrastructure needed to scale AI.
The free cash flow pressure is real, but so is the scale of the investment.
This isn’t the end of the AI story. We’re still in the middle of building the infrastructure that will power it.
And the demand for optical connectivity, bandwidth and lasers could be a major part of what comes next.
$AMZN $GOOGL $META $MSFT $SIVE

AI is burning Big Tech's free cash flow:
The combined CapEx of Amazon, $AMZN, Alphabet, $GOOGL, Meta, $META, and Microsoft, $MSFT, rose +$36.9 billion in Q3 2026, to a record $201.9 billion.
This figure has more than doubled over the last 12 months and is up +356% since Q1 2024.
Big Tech has now spent $1.6 trillion on CapEx over the last 3 years.
Meanwhile, the combined free cash flow of these companies fell -$33.1 billion last quarter, to -$26.4 billion, its lowest on record.
Free cash flow among these firms has dropped -$88.2 billion over the last year.
Only Microsoft reported positive free cash flow in Q3.
Looking ahead, these 4 companies plan to spend another $232 billion on CapEx in Q4, potentially lifting their combined CapEx to a record $740 billion in 2026.
Big Tech is undertaking one of the largest infrastructure buildouts in history.

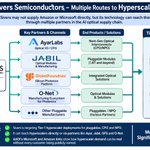
$SIVE Sivers sits upstream in the optical supply chain, supplying CW lasers and laser arrays that can support next-generation optical interconnects.
Its ecosystem includes relationships with Ayar Labs, Jabil, GlobalFoundries, O-Net and other optical manufacturers.
These technologies target pluggables, NPO and CPO, solutions needed as AI datacentres demand more optical bandwidth.
The potential end customers include Tier-1 hyperscalers such as $AMZN, $MSFT, $GOOGL and $META, either through partners or potentially direct engagements.
The important point, Sivers has stated that it engages with hyperscalers directly as well as through partners.
The opportunity is not just one customer or one application. It is multiple routes into the growing AI optical infrastructure market.
🤖 Made with AI

Few things:
- $SIVE is targeting T1 hyperscaler deployments for pluggables, CPO, NPO. Not quite sure what you mean by Tier 2.
They have direct engagements with hyperscalers but currently are more upstream by qualifying with companies like Ayar, $JBL, $GFS, O-Net that eventually likely ends up -> $AMZN / $MSFT for example.
On financing:
- Colo players like $CIFR still need $1B+ of financing for their sites.
- Neoclouds like $CRWV need billions of financing to buy GPUs.
Higher rates + less support for financing makes it more challenging for these players.
$SIVE already raised 700M SEK for their buildout and largely rely on external foundries, so they don't have financing constraints.
There's pressure on players that need currently need financing for capex, but markets group up everyone in AI sector indiscriminately.
The second nuance is whether or not this effects the end customers in terms of demand.
I'd argue optical sector is insulated, even if overall AI capex from hyperscalers decreases, I see optical content still rising and aggregate demand rising.
And this is especially the case with new incoming players going through their first qual cycles.
AIXTRON just delivered another major signal for the $SIVE thesis.
Q3 order intake jumped 122% YoY to €274.9M, with 68% of equipment orders coming from optoelectronics.
The key part:
AIXTRON says demand for InP-based optical components is growing rapidly, with AI data-centre networking driving investments in transceivers and InP manufacturing.
Its backlog has reached €549.4M, giving visibility well into 2027.
This is equipment being ordered to EXPAND laser and optical-component manufacturing capacity.
AI optical demand is accelerating → InP laser manufacturing is expanding → more laser capacity is needed.
And this is exactly the market $SIVE is targeting with its CW-DFB laser expansion.
The laser bottleneck thesis is getting harder to ignore.
Imagine @SiversSemicond announces:
“Major player like $AVGO secures 100M $SIVE lasers per year for 2 years.”
That would mean 200M lasers contracted.
And the timing could be huge before Sivers own 100M+ annual laser capacity comes online in Q4 2027, with external foundry capacity already available.
A deal of this scale could completely change the market’s view of Sivers.
Major customer validation + 200M contracted lasers + additional capacity coming online = a very different $SIVE story.
In that scenario, $SIVE to 200 SEK would no longer sound crazy to me.
Who locks up Sivers laser capacity first?
I feel @Broadcom could secure its $SIVE laser supply before capacity gets locked up by other suppliers. @SiversSemicond
At this stage, selling $SIVE is not ideal for Sivers.
Jabil is approaching Beta builds, while Sivers is investing $30M to expand Glasgow to 100M+ CW lasers annually by Q4 2027, alongside meaningful external foundry capacity already available.
To me, that suggests Sivers is preparing for potentially enormous demand:
100M internal + 200M partner capacity = 300M lasers/year of potential capacity.
As demand materialises, 2027 could be the beginning of something much bigger.