
One nerd’s perspective on the financial planning world… CFP, #LifelongLearner, Entrepreneur-In-Denial, Advisor #FinTech, & publisher of the Nerd’s Eye View blog
Joined October 2008
- Tweets132K
- Following457
- Followers96.5K
- Likes74




Pinned Tweet
Our list of "Best Conferences 2025!", and be sure to take advantage of the discount codes that several have offered to Nerd's Eye View readers!
Best in:
-Overall Planning: @FPANorCal
-Technology: @t3techhub
-Advanced Tax Planning: @AICPA Engage
and more!
bit.ly/4fisUpb

It's live! This Weekend Reading, we discuss a recent survey from KPMG that reveals that human advisors maintain a trust advantage over AI advice tools - and in fact, this gap has expanded, particularly amongst younger investors. Looking at what drives a positive investment advice experience, priorities varied significantly by generation, with a majority of Boomers and Gen Xers citing returns as the most important factor. Only a minority of respondents cited costs and fees as the most important factor, offering potential room for advisors to differentiate themselves on transparency and personalized service.
Plus, read about the newly-finalized rules for a car loan interest deduction, Roth conversion strategies, and more!
kitc.es/4zPJzL8
#advicers

Why The Empty Nest Transition Is Crucial For Retirement Success: The reality that it’s very expensive to raise children – including the ballooning cost of college – arguably this transition into the empty nest phase provides a unique opportunity for households to play “catch-up” for retirement… kitc.es/4x6PWI5
The most crucial phase of retirement saving is not figuring out how to save during the early working years, and instead is about ensuring that the transition into the empty nest phase is used as an opportunity to catch up on retirement savings – after all, just 15 years of saving 30% of income once the kids are out of the house is still enough for an astonishing number of households to stay on track for retirement! #retirementplanning #advicers

“ReFire” Instead Of ‘Just’ Retire: how retirement can be reframed not as an end, but as a beginning – one centered on fulfillment, self-exploration, and purpose. While the core elements of traditional retirement planning remain (e.g., income streams, cash flow, and lifestyle support), ReFirement builds on this foundation to explore evolving values and aspirations, with the goal of living more intentionally. kitc.es/47iJenZ #retirement #reFire
How Trump Accounts (TA) rank in the hierarchy of savings for kids: The best types of accounts for multigenerational giving, choosing the best account, and how Trump Accounts impact giving ➡️ kitc.es/4gx0Y4v
The reality is that despite the potential for significant asset accumulation by the child's eventual retirement age, TAs remain just one of a variety of account types available for intergenerational giving. And because each account type has its own set of tax characteristics and incentives for specific types of savings, the 'best' account for giving depends more on what type of giving best aligns with the parent's philosophy of how to invest in their child's future happiness and wellbeing, rather than which one will result in the highest after-tax dollar figure.
#TrumpAccounts #savings #TA

"I've never had a prospect show up and say, 'I chose you because you're a CFP professional.'" is a not uncommon sentiment in marketing for financial planners. While this may be true, it also may be glossing over a crucial component of how people ACTUALLY make decisions. kitc.es/4yL3z1g
Many advisors get a sense of what prospects want from meetings with them, but only focusing on the questions of prospective clients who are willing to get on a prospecting call can introduce and exacerbate survivorship bias, which is a statistical error that comes from concentrating on only entities that have passed a selection process, while ignoring those that did not, when drawing conclusions about the entire group.
In this article, Senior Financial Planning Nerd Sydney Squires details how prospects actually evaluate financial planners, what information they seek, and how advisors can evaluate the effectiveness of the marketing strategies that they employ (in a way that allows visibility into 'more' prospective clients). #advicers #advisormarketing

Beyond Google Reviews: How can advisors adopt a two-pronged approach to sustainably use online reviews in their marketing... while balancing concerns with compliance requirements: kitc.es/4yOZyZA
In this guest post, Whit Lanier, co-founder of Amplify Reviews (an RIA review-verification and publishing platform), and Kent Keister, founder of Reliant Compliance (an RIA compliance firm), shares that while 'getting involved with' Google reviews can increase compliance complexity, but recommend 3 options and strategies on how to maximize marketing impact while simplifying compliance.

While Roth conversions are often used to transfer Traditional IRA funds into a Roth IRA account, reporting these transactions for income tax purposes can be complicated when the Traditional IRA from which the funds are being transferred include both pre- and post-tax funds. kitc.es/4ddIBPF
By planning around current and expected marginal tax brackets, and by strategizing to isolate the basis of pre-tax dollars in Traditional IRA accounts, advisors can facilitate substantial tax savings for their clients by way of efficient Roth conversions. #advicers #Roth

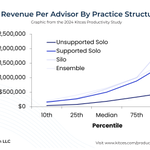
The median unsupported solo advisor generates $182,500 in revenue - 64% less than the $500,000+ revenue median of supported solo advisors.
This stark contrast remains just as true among the highest performers. Unsupported solos at the 75th percentile generate $350,000 in revenue, yet this is still 61% less than supported solo advisors who leverage their time to bring in $900,000. Advisors who do not hire staff support appear to "cap out" at barely one-third of what they can achieve with a support team.
We dive deeper into the impact of leveraging staff support in our latest productivity study available here: kitc.es/4gpB6Ef
#KitcesResearch #advisorproductivity

"Upmarket for us is a strategy, it's a philosophy, and it's an identity. Upmarket isn't the same thing for everyone. It isn't just higher-dollar clients. Sometimes it's more of the clients I already have, and sometimes it's, "I just want to level up in these other areas of my business." kitc.es/4zAj9gd
In this #FASuccess, we chat with Chris Smith, founder of PSBLTY, a brand strategy, design, and implementation firm that works with financial advisors, teams, and firms, who shares how he works with advisors to create a more effective discovery process that closes more clients and helps advisors move upmarket.
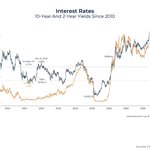
Perhaps the biggest factor that impacted markets in the third quarter was the climb in interest rates to the highest level in more than 20 years. This was due to the latest Fed rate hike, AI trends, oil prices, pressure on government bonds, and more. kitc.es/4i5ApUu
Clients nervous about the markets? For financial advisors, periods of market volatility represent opportunities to share long-term perspectives that build client trust and help them to stay focused on their long-term goals.
James Liu, CEO of Clearnomics, walks through seven charts to help advisors put the quarter's headlines into context for clients, from the historic climb in bond yields, to what resurgent AI-related spending means for corporate earnings and productivity.

Suppose you were objectively the best financial advisor in the world, that delivered more value to clients than anyone else. But because of too many discounts to your fee schedule, you went bankrupt in the next bear market. Who, then, would take care of your clients? kitc.es/4io2YwD
In this guest post, Matthew Jarvis and Micah Shilanski, who now coach advisors through The Perfect RIA platform based on practices they successfully implemented in their own firms, discuss how advisors can measure their true profitability, create a client-by-client revenue report, and determine when it’s time to ‘graduate’ clients who are no longer a good fit (as well as how to approach this difficult conversation).
They share resources on calculating true gross and true net, the red/yelllow/green profitability report on how to identify clients to 'graduate', and why this is a graduation, not firing. #advicers
The Problem With FIRE: Human beings aren't meant to be idle for life. Even as the FIRE movement develops strategies to reach financial independence earlier and earlier, to have a longer time window for that life of leisure… retirement research is finding that even "normal" retirees often aren’t nearly as happy in that retired life of than they expected! kitc.es/4gD1C0o

An analysis of historic asset class performance when bond yields spike suggests that while there tends to be short-term pain for longer-maturity Treasuries, there could be some light at the (unknown) end of the tunnel. (Julien Esnault | Portfolio Terminal)
More on investment planning this #WeekendReading: kitc.es/4i7MKXb

Asking For Referrals: Asking more for referrals equate getting more... or does it? Kitces research shows that increased frequency does NOT translate to more success. kitc.es/4ygRAIl
What really drives referrals then? The emphasis on clients 'feeling' that the advisor provides value – as opposed to simply 'providing value' – is deliberate. What matters for referrals isn't just the work the advisor does, but whether clients recognize its value. What does seem to help is simply making clients aware that referrals are accepted and appreciated, thus keeping the idea top of mind without explicitly asking.

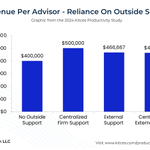
Advisor service teams face the question of whether to provide all services internally by the service team, by a centralized support team affiliated with the team’s firm, or externally by a third party vendor or outsourcing provider
Looking at the relationship between reliance on outside support and productivity (revenue per advisor), service teams that do not outsource a single service earn $400,000 in annual revenue per advisor, compared to $500,000 for those exclusively relying on centralized support, $466,667 for those exclusively relying on external support, and $463,333 for those relying on both.
Of course, this doesn't mean that teams should offload everything or even most things. As we showed elsewhere in the report, many successful teams handle all their core offerings in house and offload "semi-frequent" services (e.g., insurance implementation, estate document preparation, which may only occur 5-10 times per year but are needed for at least some clients every year) to avoid spending excessive time/staff resources in areas outside their primary focus.
We dive deeper into the costs and benefits of outsourcing in our latest productivity study available here: kitc.es/4gpB6Ef
#KitcesResearch #AdvisorProductivity

Inherited An IRA? Why the mechanics of taking RMDs for recently inherited IRAs can differ by custodian and lead to challenges for beneficiaries. (Denise Appleby | Morningstar)
More curated articles on RMDs this #WeekendReading: kitc.es/4i7MKXb

10 common RMD mistakes ❌ (and how financial advisors can help clients avoid them), from challenges in correctly coordinating RMDs across accounts to errors made when leveraging the ‘still working’ exception. (Andy Ives | The Slott Report)
More curated articles on RMDs this #WeekendReading: kitc.es/4i7MKXb
Simplifying Retirement Income Planning Visualization Using The ‘Spending Risk Curve’: kitc.es/4A1okHc
These “Spending Risk Curves” can be far more insightful than a single probability-of-success result, and very useful for an advisor to gain a higher-level understanding of a client’s financial options by visually illustrating the trade-offs between a client’s spending choices and risk in retirement.
At their core, Spending Risk Curves show the trade-off between risk (framed in terms of probability of success or otherwise) and spending in retirement planning (i.e., as annual portfolio withdrawals increase, so does the spending risk level) based on a client’s particular circumstances.

When parents give money to their children to use for a specific purpose, that purpose tends to fall into one of five different 'eras' depending on when during the child's lifetime it's intended to be used: Childhood, Education, Lifestyle, Retirement, or Dynasty Creation. kitc.es/3TYvOKM
In the context of how intergenerational giving has traditionally been treated – with a foundation of small-dollar gifts in childhood, a heavy emphasis on education and lifestyle-supporting gifts in young adulthood, a layer of multigenerational dynasty planning for families that can afford it, and gifts of retirement savings for the younger generation as at most an afterthought – there's been a surprising amount of interest in the new Sec. 530A "Trump Accounts" (TAs) created by the One Big Beautiful Bill Act (OBBBA) and officially launched on July 4, 2026.

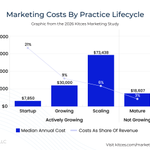
Marketing costs for financial advisory practices (inclusive of both 'hard costs' spent on marketing and 'soft costs' of advisor and staff time) vary depending on their growth stage and revenue objectives. Practices in the ‘startup’ stage of development allocate 21% of revenue toward marketing expenditures, although this equates to only about $7,850 given their relatively limited revenue base at that stage (which both constrains their ability to afford hard-dollar marketing costs, and reduces the cost of their advisor time in soft-dollar expenditures).
Among ‘growing’ and ‘scaling’ practices, marketing expenditures generally range from 6% to 9% of revenue. By contrast, ‘mature’ practices that are not actively pursuing growth allocate just 3% of revenue to marketing.
We look at this in greater detail in NEW Marketing Study, now available entirely for FREE here: kitc.es/3FAmFAC
