




Pinned Tweet
$AMD is easily a $1,200 stock IMO| CPUs TAM 🧵
Not Financial Advice! DYOR!
In this thread, I want to discuss the actual TAM for CPUs data center for just 2026, where many are giving different ranges, where I don't agree with. I will explain in detail why I disagree with these research firms and financial analysts using Math. And this thread should not be treated as Financial Advice. I'm just explaining my research and thought process so we can have a discussion.
In 2024/2025, I gave out $620 PT for FY2026 was too conservative for AMD potential. At the time, It was early and many were just laughing, that PT was unrealistic and the AI world is run on GPUs only. Today, most of these folks are laughing with me. That is ok, I dont offer financial advice, and I do not need everyone to agree with me. I respect other opinions.
If you enjoy this kind of thread, slap the like/repost/bookmark.
If you want to support my work further and gain more in-depth analysis, consider subscribe!
In early 2026, hyperscalers, enterprises, and OEMs are scrambling as Intel and AMD server CPUs are largely sold out for the year, with prices jumping 10–20% and lead times stretching from weeks to months (or longer for certain SKUs). What was once a GPU dominated story has flipped: the shift to explosive Agentic AI with its multi-step reasoning loops, tool calling, multi-agent orchestration, real-time data movement, and reinforcement learning, is dramatically tightening CPU:GPU ratios from the old training-era 1:4–8 all the way to 1:1 to 5:1 or even CPU-heavy configurations. CEOs across NVIDIA, AMD, Intel, Google, Meta, Microsoft, and public companies have been sounding the alarm on CNBC, Bloomberg, and earnings calls. CPUs are “cool again,” and in many agentic deployments they are becoming the new bottleneck alongside (or even ahead of) GPUs and custom ASICs.
In 2025, roughly 12-15m AI GPUs + AI ASICs GPUs shipped, and is expect to be 15-20m units by 2026, where it suggesting Training demand is not going away. The actual TAM is structural, multiplicative demand that has already forced AMD to double its long-term server CPU TAM forecast to >$120 billion by 2030 (>35% CAGR), with Dr. Lisa Su noting Q2 2026 server CPU sales expected to surge 70%+ year-over-year and demand “far exceeding expectations.”
At the same time, AMD’s secured 30–40% share of TSMC’s initial 2nm capacity (behind only Apple’s >50%) positions it to ramp Zen 6-based EPYC Venice exactly when this agentic wave hits hardest but even that aggressive five-fab 2nm expansion (with plans scaling toward 11 total advanced facilities) cannot instantly close the gap in the near-term. Supply constraints on wafers, advanced packaging, and power are compounding the squeeze, just as hyperscalers forward-buy and lock in long-term deals.
1. The actual potential TAM
Various sources and institutions are giving $50-$160-$200B CPUs TAM toward 2030, and i disagree, where supply is severely behind vs Demand by at least 2-3 years or even longer by some estimates.
The actual TAM will probably be 15-20m for FY2026. The typical average selling price from low to high end is $5,000 to $15,000, but due to rising memory, and different inflationary pressures on Semi, it would be more logical to think between $7,000-17,000.
A. CPU:GPU Ratio at 1:1
A basic calucation at mid range
=12,000 x 15-20m CPUs= $180-$240B TAM
B. CPU:GPU Ratio at 5:1
= $12,000 x 75m-100m CPUs= $900B-$1.2T TAM
Of course TSMC cannot even supply 20% of this massive inflection TAM in 2026. But do we think of Demand for TAM or Supply for TAM? Hence we are seeing massive 2nm Ramp from TSMC for $AMD.
IMO, conservatively, I would take down 15-20% on 1:1 or $135-$192B TAM for just 2026. Im not even talking about 2030.
We are just months into this, it is impossible to estimate Cagr atm, but this is 1-5 agents running tasks, I wrote a thread on 24/7 autonomous agents thread, where companies could use 50-250 agents to run tasks for them 24/7. It would require a different structural CPU:GPU to bring down the cost of token as well as handling the Orchestration bottleneck. GPUs would be useless and sit idle waiting for CPU due to highly CPU-intensive nature.
The cost per Million tokens must come down more rapidly for this 50-250 autonomous agents to work, otherwise the token cost would be too enormous.
Helios Rack is estimated to bring inference cost down to $0.0003-$0.0005/M tokens with 18 EPYC Venices along with 72 MI455x and other chips+ Components.
A heavier or CPUs dense rack would bring down inference cost further.
EPYC Verano(2027 gen 7 AI-optimized) is expected to drive inference costs meaningfully lower than the Venice baseline likely to the $0.00002–$0.00025 per million tokens range (or even sub-$0.00015 in highly optimized agentic/batch workloads).
Verano have higher core counts than Venice, LPDDR5X SOCAMM2 memory support, more AI optimized and Next-Gen rack density & efficiency.
2. $AMD secured at least 30-40% of TSMC 2nm capacity and Memory from Samsung through 2028-2030.
2 2nm fabs are entering ramping phase toward 60-65k wafers per months and 5 dedicated 2nm fabs entering mass production/ramp in 2026. Will link sub threads below if you are interest for full detail.
Apple is reported to secure 50%+ 2nm capacity for Iphone 18 and Mac chips and AMD secured at least 30-40% capacity while $NVDA $AVGO $ARM $AMZN $GOOGL and others are on 3nm.
This broader aggressive ramp from TSMC to target up to 11 fabs is to address $AMD massive growth ahead. Where $ARM is facing massive CPUs supply constraints as they have to compete with other Mega Cap players on 3nm allocation. And $INTC is also facing supply constraints for data center CPUs and PC per management with lead times extrended to longer than 12 weeks.
Dr. Su is aiming for higher than 50%+ Market share, and I believe it is achievable in 2026 or 2027 as AMD has the strongest CPUs offerings. Dr. Su did not want to take advantage of the shortage and she said during the Q1 earning call, AMD is prioritizing Units shipped while guiding margin to be inching 60%. If Jensen were in charge, I'm sure margin would be 70-75% in this kind of severe CPUs shortage condition. But that is not how Dr. Su operates for more than a decade. She wants most market share. So we will see it in revenue growth, but as TSMC ramps faster and faster, AMD Operating and FCF margin will massively improve vs prior decade. A significantly higher margin profile than before.
3. How I came up with $1,200 withint 12-18 months?
At $1,200/ share, that would be around $2 Trillion MC.
I expect FY2027 revenue to be $124-$144B where data center revenue dominates overall revenue.
AI GPUs: I will stick to the lowest end so show u that I'm conservative at $18B for each GW vs $NVDA Rubin is $30B+ (most likely Helios Rack in the $20B+ due to memory price rising). We know deals with @OpenAI and @Meta are around 12GW and additional multi-customers at multi-GW scale were hinted and will be revealed as we get to July 22-23 2026 Advancing AI event. For now I will conservatively add a bit more to this model. (3-6GW Helios Rack Range)
EPYC Venice is reported to be in $15,000-$20,000. However large customers will likely to enjoy $10-$12k discount. I expect AMD to be able to ramp 7m EPYC Venice for entire 2026 and 3-4m of EPYC Verano(higher price than Venice). If we take an average selling price of $10,000 to be on the conservative side. Take down another 30% to be even more conservative on projection. I like to be conservative. That would be ~ 7m EPYC CPUs(Venice + Verano) for FY2027 or 583,000 units per month or 15,000 additional 2nm wafers per month which is completely reasonable for current TSMC Ramp, and I may be too conservative here.
EPYC Verano and MI500 series will also be on 2nm.
AI GPUs: 3GW x $18B= $54B
EPYC CPUs: $10k x 7m CPUs= $70B
= Data center revenue alone is $124B
Other segments= probably in the $20-$25B FY 2027.
FY2027 revenue = $124-$149B
At 7m EPYC CPUs for entire 2027, that would be more than 50% market share when we comp it to availability from supply side, not from total Demand. It is possible that TSMC could significantly ramp even more capacity in 2027, so we will see.
Metric Q1 2026 FY2027
Gross Margin 55-56% 60-62%
Operating Margin 25-26% 32-35%
Net Income Margin ~22% 26-30%
FCF Margin 25% 28-30%
At $124-$149B Revenue FY 2027
Net Income would be $32-$44B
EPS would be $20-$27 (GAAP)
Non-GAAP would be $25-$31
At $1,200 a share or $2T valuation that would be:
13.4-16x Price to Sales (P/S)
38-48 P/E
At this kind of growth of AI SuperCycle, I think it is very reasonable valuation.
If we use today at $406/share or $661B MC:
2027 P/S = 4.4x-5.3x
2027 P/E = 13x-16x
Is AMD today expensive or cheap to you?
Above is already a very conservative where I trimmed 20-30% of doable units. Meaning, there could be upside if TSMC is able to ramp meaningfully like they are planning.
Conclusion:
A $1,200 per share valuation IMO for AMD in FY2027 is not expensive at all; it is, in fact, conservative when viewed against the structural explosion in agentic AI demand we have mapped out.
With server CPU TAM potentially scaling into the $100–$200B+ range in just CPU:GPU 1:1 Ratio for just 2026. AMD positioned to capture 50%+ share thanks to its 2nm TSMC allocation advantage and full-stack leadership, the company could realistically deliver $124–149B in total revenue and $25–$31+ non-GAAP EPS. At those levels, $1,200 implies a 2027 P/E = 13x-16x. Entirely reasonable for a company that will have become the clear Inference Queen (and in many workloads the preferred) AI infrastructure provider, with operating margins expanding above 30% and tens of billions in high-margin rack-scale AI revenue.
Dr. Lisa Su was right presciently so about the Agentic AI inflection all the way back to her early 2022–2023 commentary on the coming shift from pure training to inference and orchestration-heavy workloads. While the broader market only fully woke up to this in 2026 when she doubled AMD’s long-term server CPU TAM forecast to >$120B by 2030 (with >35% CAGR), Dr. Su and her team have consistently positioned the company at the center of the CPU renaissance. The explosive demand we are seeing today, sold-out lines, rising ASPs, and hyperscalers forward-buying entire gigawatts of Helios-class systems is exactly the outcome she forecasted years ago.
Not Financial Advice! DYOR!

$AMD $INTC $TSM $ARM TrendForce: Estimates Server CPU Shipments to Grow 31% This Year, Over 40% Next Year
According to TrendForce's latest AI server industry research, as AI service providers actively launch AI Agent-related applications, server CPU demand has been steadily growing since the second half of 2025, with an estimated annual growth rate of 31% in 2026. In 2027, due to the continued growth in demand for AI inference and the increased penetration rate of Agentic AI services, server CPU shipments are expected to increase by more than 40% annually. However, the market landscape dominated by the x86 camp may change.
TrendForce points out that due to the rise of AI Agent services, the proportion of AI inference workloads in cloud data center servers is expected to increase, which will gradually change the CPU and GPU/ASIC ratio inside the server. If we look at the server rack solutions and growth trends of operators, it will develop from the past 1:8 to 1:2 or even 1:1, adding momentum to server CPU shipments.
2025: The x86 camp (Intel and AMD) dominates nearly 90% of the market, with AMD’s share rising; Arm-based just broke 10%.
2026: Both x86 and Arm-based CPUs are shipping actively to capture AI inference opportunities. Intel’s new products face process and packaging challenges with delayed shipments; support comes from Emerald Rapids and Granite Rapids, but tight capacity on its own process limits overall growth, prevents meeting order demand, and causes market share to decline. AMD’s new Venice entered 2nm mass production in 2026, with main shipments still from Genoa and Turin platforms. As TSMC ramping 2nm capacity, AMD’s server CPU share is estimated to grow significantly to around 27% this year. Arm-based (AWS continuing Graviton, NVIDIA Grace demand expanding, Google’s Axion in volume shipments, Microsoft Cobalt 100 .

$AMD The real secret why AMD is going to win long term!
@AMD CPUs GPUs are going to be used for 7-10 years even after end of 5-5.5 yr of depreciation. Naturally, AI Labs, Hyperscalers and Enterprises will prefer owning AMD racks long term.
1. Severe Supply Deficits that is going to last for years as TSMC cannot ramp fast enough.
2. AI labs, Hyperscalers & Enterprises cascade those older AMD processors down to lighter workloads like AI inference, targeted ad algorithms, or basic internal web serving.
3. 5.5 years is better than 7-10 years to boost pre-tax profit
Chiplet Architecture naturally extending lifespan of CPU and GPU.
If a single core degrades or fails over 5 years on an Intel ot NVDA monolithic chip, it can crash the whole processor. With AMD's modular chiplets, if a single core or die suffers severe degradation, hyperscalers can simply disable that specific block via software firmware and keep the other 90%+ of the processor running perfectly.
The Competitor Problem: Historically, Intel changes server and desktop motherboard sockets frequently. If you want to upgrade your CPU or replace a broken motherboard 4 years down the line, you often have to scrap the motherboard, RAM, and processor all at once because the newer chips won't fit the physical slots.
The AMD Strategy: AMD heavily prioritizes keeping the same physical CPU socket (like the enterprise SP3 or SP5 platforms, or consumer AM4/AM5) across multiple chip generations. This allows data centers to keep the underlying infrastructure like motherboards, power delivery systems, and massive cooling rigs operational for nearly a decade while seamlessly swapping or upgrading the CPUs inside them.
In addition, AMD's massive memory envelopes mean their hardware remains capable of running software updates years after competing chips have choked on memory capacity limits.
Not Financial Advice! DYOR!

Dumping 12-25x Fwd PE growing revenue 50-100%+ to buy Fwd 40-50x PE growing revenue at 2-6% is not going to work.

$MSFT @satyanadella on Chasing Frontier Labs, Security, “SI,” & Succession At Microsoft | Future Proof
youtube.com/watch?v=CUgS4y4X…
$TSM has asked equipment suppliers about the feasibility of using rare earth free motors in its highly automated fab equipment to mitigate the risk of supply disruptions from Chinese restrictions.
Industry observers note that discussions remain at an early stage with no large-scale adoption yet, but the move underscores that rare earths have become a material supply-chain risk for the semiconductor sector.
Source Ctee

$AMD Helion (CPU rack) | Agentic Era ✍️
@AMD Helion offers two configurations: a CPU-only rack supporting up to 32,768 sixth-generation EPYC cores and an integrated enterprise design combining EPYC processors with Instinct MI350P accelerators.
The architecture supports independent scaling of CPU-based agent execution and GPU inference resources, potentially improving infrastructure utilization as AI workload demands evolve.
Built around Open Compute Project standards, Helion provides a modular foundation for hardware integration, customization and future upgrades across participating equipment manufacturers.
AMD offers high-density, balanced and high-frequency CPU configurations, allowing system designers to match processor performance and electrical requirements to different agentic AI workloads.
Initial Helion availability is targeted for November 2026, with commercial implementations planned by industry partners. Rack-level power requirements, independent performance benchmarks and deployment economics remain unproven.
"Agentic AI is not a single workload. It spans personal agents, enterprise applications, code execution and complex workflows, each with different compute requirements. To do that takes optimized compute and infrastructure that can adapt to different workloads. With AMD Helion, we are bringing AMD EPYC performance, open software and flexible rack designs together so our partners can build systems around customer needs and make efficient use of available power."

$AMD shareholders just heard from $META CEO wanting to scale 10m @Muse users to billions of users and expand Muse network to millions small and large businesses. It is unimaginable to calculate the total vol of CPUs to service this kind of agentic demand, yet Algos decided to dump @AMD down 4-5%, mostly manipulation in PM. We also saw @OpenAI, @AnthropicAI launched Consumer/Enterprise Agentic as well. $AMZN $MSFT $AAPL $GOOGL are going to join soon. Demand for AMD CPUs IMO is at least 20 to 1 supply in the next 3-5 years.
We are only 8 trading days away from Q3 2026 ER, with biggest Q4 guidance going to be issued. Yet they decided to manipulate it so they can get in cheaper.
8 TRADING DAYS. November 3rd 2026.
Almost all Hyperscalers, AI labs, Enterprises all said demand is way too high and they can't get enough AMD CPUs GPUs through 2028-2030 to service demand, and yet "they" decided to manipulate AMD down.
It is what it is. This isn't the first time they did this.
This is why I dont time the market or hold call option.
Not Financial Advice! DYOR!


$NVDA Jensen Huang Exclusive: AI Financing Fears & Rising GPU Rents | GTC Berlin
youtube.com/watch?v=UYBSBnCV…
$SPCX 8.3% is not bad, but certainly rising unsustainably.

$AMD $TSM | The next SI biggest bottle neck is not
~Power
~Capital
~Advanced Packaging
It is @AMD CPUs to scale Consumer & Enterprise Agentic, where this is actually cheaper to scale vs GPUs and generate far higher revenue vs Training era. It takes time for TSMC to build Fabs and scale 2nm wafers and upcoming 1.4nm to service AMD customers. And yes, this is the most aggressive 2nm RAMP since TSMC scaled 3nm or prior nodes.
Scaling EPYC Venice is far more efficient overall thanks to extreme core density, superior platform (memory/I/O), and far better software/operational simplicity. Fewer, denser, more capable servers often win on total cost of ownership once you factor in networking, management, and software.
I talked about this for nearly 4 years now. Btw When Dr. Su said $220B TAM by 2030 for CPU, that would usually mean it is going to be closer to $500B+ :)).
Most will see it in the numbers.
See you in Nov 3rd 2026 Q3 ER!
Not Financial Advice! DYOR!
$AMD shareholders just heard from $META CEO wanting to scale 10m @Muse users to billions of users and expand Muse network to millions small and large businesses. It is unimaginable to calculate the total vol of CPUs to service this kind of agentic demand, yet Algos decided to dump @AMD down 4-5%, mostly manipulation in PM. We also saw @OpenAI, @AnthropicAI launched Consumer/Enterprise Agentic as well. $AMZN $MSFT $AAPL $GOOGL are going to join soon. Demand for AMD CPUs IMO is at least 20 to 1 supply in the next 3-5 years.
We are only 8 trading days away from Q3 2026 ER, with biggest Q4 guidance going to be issued. Yet they decided to manipulate it so they can get in cheaper.
8 TRADING DAYS. November 3rd 2026.
Almost all Hyperscalers, AI labs, Enterprises all said demand is way too high and they can't get enough AMD CPUs GPUs through 2028-2030 to service demand, and yet "they" decided to manipulate AMD down.
It is what it is. This isn't the first time they did this.
This is why I dont time the market or hold call option.
Not Financial Advice! DYOR!
$AMD CPU vs $ARM based CPU w/ CTO & Chief Architect 👂
Advanced Insights, @AMD CTO and EVP @mpaper2000 Mark Papermaster sits down with Mike Clark, AMD SVP, Corporate Fellow and Chief Architect, to explore the architecture, engineering decisions and culture behind the Zen CPU family.
Agentic AI changes the CPU:GPU balance. Prefill/decode stays GPU heavy, but orchestration, spawning sub-agents, tool calls, context management, sandbox execution, and feeding accelerators run on the CPU. AMD projects the ratio moving toward roughly 1-2:1 (versus ~1:4 in earlier generative-AI setups) and says agents create highly parallel, throughput oriented work that plays to high core/thread counts plus strong per-core performance.
1. Scaling large numbers of agents
AI Labs, Enterprises and Hyperscalers must choose AMD x86 CPU for mmaximum threads per socket, compatibility with existing x86 tools/libraries/enterprise software, mixed workloads, or strong per-core performance alongside density. SMT gives AMD more logical threads per core (typically 2 vs 1 on most ARM server cores), which is a real advantage for some agentic and RL workloads.
2. Training agents with RL
Reinforcement learning for agents usually has two phases that stress different parts of the system:
~Data collection / environment interaction: many parallel rollouts or simulated environments. This is often CPU-bound (or mixed) and benefits from high thread counts and good single-thread performance so you can scale the number of concurrent agents cheaply.
~Policy/value network updates: typically GPU-bound matrix math.
x86/Zen advantages here include SMT for more parallel environments, mature vector extensions, and the fact that many existing simulators, tools, and enterprise applications that agents call are already x86 optimized.
Thread density is a strong AMD selling point for scaling agents and RL rollouts.
Full Video here: youtube.com/watch?v=7sBzosci…
BREAKING $AMD | $META CEO @finkd explained during Q3 2026 Earning Call how both companies are going to thrive short-medium and long term as strategic partner. CPU seems to be the biggest constraint atm to scale Muse quickly.
Dr. Su big bet on EPYC since 2022 to scale Agentic SI is materializing RIGHT NOW! And Meta probably going to be the biggest CPU customer out of all.🐂🐂🐂
Key:
~Biggest constraint is compute intensive service to run Muse (CPUs) so no Global launch yet.
~ Muse grew so fast to 10 million users (6 weeks) with @Meta holding back due to compute shortage ( CPUs) and only in the US and Canada.
~Muse will scale to billions of users as quick as possible to serivce network of Muse, from consumers, small businesses to enterprises. AKA More compute (GPU and CPU)
~Muse is expected to monetize better than families of Apps due to the TAM/Size of Commerce per User
~Mark expects Muse to be very profitable next few years as they get cost down and scale out the compute to serve billions of users/customers
~Muse should be mostly free for most people and businesses/merchants pay a % to $META. People or businesses that want to do more with Muse can subscribe directly to higher token tier
~Increase compute efficiency is very important for operating leverage and increase the value of Muse offers to customers
Not Financial Advice! DYOR!
Source: Meta Q3 2026 Earning Call.


$QQQ $SOXX $SMH $AMD $NVDA $TSM $AVGO
$MSFT $AMZN $META $GOOGL @OpenAI @AnthropicAI
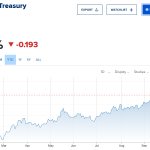
SI Bears are celebrating right now, but the irony, 10y yield collapsing at this pace will only help Hypercalers and AI Labs to build more data center at at lower cost.
Lower Treasury yields directly reduce the cost of capital for the biggest spenders. Hyperscalers (Microsoft, Amazon, Google, Meta...) and pure play AI labs have been issuing massive amounts of debt to fund the data center buildout, hundreds of billions already, with projections for much more.

