

The External Intelligence Company. Outpace your market. Outsmart your competitors. Follow us for daily insights.
Global
Joined February 2024
- Tweets1.5K
- Following284
- Followers766
- Likes107





Pinned Tweet
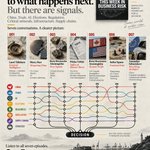
There is no direct line to what happens next. But there are signals.
Seven episodes into This Week in Business Risk, one thing has become increasingly clear: the risks shaping business rarely stay neatly inside the categories we assign to them.
China policy becomes an automotive question. Elections become an infrastructure question. Critical minerals become a trade and industrial-policy question. AI becomes an energy question. Regulation becomes geopolitics. Maritime chokepoints become balance-sheet issues.
Across our first seven episodes, host Rwizi Rweizooba Ainomugisha and his guests have explored these connections from very different angles:
I Lauri Tähtinen — external intelligence, human–machine analysis and strategic chokepoints (@lauritahtinen)
II Mercy Kuo — China risk, Taiwan, AI and corporate wargaming (@mercyakuo)
III Rwizi Rweizooba Ainomugisha — critical minerals, India, Africa and emerging geopolitical signals
IV Pekka Virkki — elections, data centres, maritime chokepoints and post-Finlandization (@Virkki5)
V Rwizi Rweizooba Ainomugisha — the US–Canada trade dispute and its consequences for automotive, steel, electricity, logistics and critical minerals
VI Sethu Nguna — simulations, training and wargaming US–China strategic competition
VII Amandine Schneickert, DSc, CIPT — China's changing global role, European regulation and autonomous vehicles
Different subjects, different perspectives, but a common question:
What does this mean for the decisions businesses have to make next?
If you haven't listened yet, this is a good time to start—or to catch up on all seven!
This Week in Business Risk — A Mission Grey Guild Podcast
Spotify
open.spotify.com/show/033TrD…
Apple Podcasts
podcasts.apple.com/us/podcas…
YouTube
youtube.com/playlist?list=OL…

Resilience has a price. Who ultimately pays it?
The latest Mission Grey Guild Newsletter issue examines the emerging resilience premium—from supply chains and insurance to data centers, infrastructure warfare, and the new geography of global dependence.
Read it here:
missiongrey.com/insights/
🤖 Made with AI

Sanctions, trade restrictions, and security policy are increasingly shaping the operating environment for business.
🎧 Listen to This Week in Business Risk by @Rweizooba!
Spotify:
open.spotify.com/episode/6aV…
Apple:
podcasts.apple.com/us/podcas…
YouTube:
youtube.com/watch?v=8Uf3Sj_6…
🤖 Made with AI

Mission Grey retweeted

Please listen to the @Rweizooba’s latest!

Four critical minerals deals involving the US, EU, Canada, Brazil, Lithuania & Dominican Republic.
But the latest This Week in Business Risk argues they’re not really about rocks.
They’re about trust, strategic alignment and who gets inside the fence.
🎧 Listen to the latest episode:
What these critical minerals deals are really about (US, EU, Canada, Brazil, Lithuania & the DR)
🌳 Spotify
open.spotify.com/episode/6nz…
🍏 Apple Podcasts
podcasts.apple.com/us/podcas…
▶️ YouTube
lnkd.in/dJPU_HTkhttps://www.…

Mission Grey retweeted

If these recent critical minerals deals are not really about critical minerals, then what are they really about?! 🤔
Check out my latest episode of "This Week in Business Risk" powered by @MissionGrey 🤖
youtu.be/xcl8h-4eKA8?si=rozB…

The AI race isn’t just US vs. China.
Taiwan makes advanced chips. Japan and South Korea remain technology powers. India is building AI capacity. Singapore is an AI hub. China combines AI with manufacturing at enormous scale.
For business, the real issue is dependency.
Whose models? Whose cloud? Whose chips? Where is the data? What happens when export controls, regulation or geopolitics change?
In The Diplomat (@Diplomat_APAC), Mission Grey founder and chairman Jouko Ahvenainen (@jahven) argues that technological sovereignty shouldn’t mean isolation.
thediplomat.com/2026/09/the-…
The better objective: strategic optionality.
Know your dependencies. Keep alternatives. Preserve the ability to act when circumstances change.
🤖 Made with AI

Four critical minerals deals involving the US, EU, Canada, Brazil, Lithuania & Dominican Republic.
But the latest This Week in Business Risk argues they’re not really about rocks.
They’re about trust, strategic alignment and who gets inside the fence.
🎧 Listen to the latest episode:
What these critical minerals deals are really about (US, EU, Canada, Brazil, Lithuania & the DR)
🌳 Spotify
open.spotify.com/episode/6nz…
🍏 Apple Podcasts
podcasts.apple.com/us/podcas…
▶️ YouTube
lnkd.in/dJPU_HTkhttps://www.…
🤖 Made with AI
Mission Grey retweeted

How healthy and competitive is a nation really?
We often judge countries through GDP, productivity, employment and debt. But these indicators can look healthy while a nation quietly loses skilled people, healthy working years and institutional knowledge.
Our new @MissionGrey Guild Newsletter, Health of Nations, examines competitiveness from this different perspective. It explores workforce health, ageing, skills, AI’s impact on how future experts are developed, and four alternative futures for national human capacity.
This is not only a public-policy issue. For businesses, the availability, capability, health and adaptability of people can determine whether investments and operations succeed.
“GDP is not capacity. Employment is not readiness. Longevity is not vitality.”
Read more: missiongrey.com/insights/

Mission Grey retweeted
Latest @MissionGrey Monthly Weak-Signal Snapshot looks at what is changing around the workforce: AI adoption, skills and hiring, immigration and talent mobility, regulation, wellbeing and the resilience of critical capabilities.
The interesting part is not any one trend, but how they are starting to interact. One of the clearest signals this month is that adaptation is moving faster than validation.
Read more: missiongrey.com/insights/mis…

Mission Grey retweeted
Rwizi’s podcast episodes are always insightful!
There is no direct line to what happens next. But there are signals.
Seven episodes into This Week in Business Risk, one thing has become increasingly clear: the risks shaping business rarely stay neatly inside the categories we assign to them.
China policy becomes an automotive question. Elections become an infrastructure question. Critical minerals become a trade and industrial-policy question. AI becomes an energy question. Regulation becomes geopolitics. Maritime chokepoints become balance-sheet issues.
Across our first seven episodes, host Rwizi Rweizooba Ainomugisha and his guests have explored these connections from very different angles:
I Lauri Tähtinen — external intelligence, human–machine analysis and strategic chokepoints (@lauritahtinen)
II Mercy Kuo — China risk, Taiwan, AI and corporate wargaming (@mercyakuo)
III Rwizi Rweizooba Ainomugisha — critical minerals, India, Africa and emerging geopolitical signals
IV Pekka Virkki — elections, data centres, maritime chokepoints and post-Finlandization (@Virkki5)
V Rwizi Rweizooba Ainomugisha — the US–Canada trade dispute and its consequences for automotive, steel, electricity, logistics and critical minerals
VI Sethu Nguna — simulations, training and wargaming US–China strategic competition
VII Amandine Schneickert, DSc, CIPT — China's changing global role, European regulation and autonomous vehicles
Different subjects, different perspectives, but a common question:
What does this mean for the decisions businesses have to make next?
If you haven't listened yet, this is a good time to start—or to catch up on all seven!
This Week in Business Risk — A Mission Grey Guild Podcast
Spotify
open.spotify.com/show/033TrD…
Apple Podcasts
podcasts.apple.com/us/podcas…
YouTube
youtube.com/playlist?list=OL…
Mission Grey retweeted
Risk models can look precise while their assumptions are uncertain. Making that visible takes serious mathematics.
Our @MissionGrey CRO Jani Kinnunen coauthored research on this, now selected as Editor’s Choice in MDPI’s Symmetry. Expertise that matters.
missiongrey.com/insights/jan…

Mission Grey retweeted
I'll speak at this event in two weeks in London. Let's try to catch up if you are around.
@MissionGrey @MyPrifina

EUROPE’S WAR RISK IS WIDENING AGAIN
The clearest strategic signal today is that the Russia-Ukraine war is re-escalating faster than diplomacy can contain it. After a brief pause around US envoy visits, Russia resumed large-scale aerial pressure on Kyiv, with Ukraine reporting 32 cruise missiles and 166 drones in one assault, while intercepting most cruise missiles but facing continued strain against ballistic threats. Germany has now signaled more Patriot support, and Ukraine says it is contracting for about 1,000 Patriot missiles ahead of winter.
At the same time, Kyiv is pushing the war’s cost back onto Russia’s energy system. Ukrainian strikes hit refineries in Ryazan, Perm and Tatarstan, alongside logistics targets in occupied Crimea. That matters because this is no longer just a battlefield story. It is a widening business-risk story for energy markets, insurers, logistics networks and defense supply chains across Europe. The implication is straightforward: firms should plan for a longer war of attrition, not a near-term diplomatic reset.
NORTH AMERICA’S SAFE-HAVEN TRADE MODEL IS BREAKING
The most important business signal today is not China or energy. It is the rapid hardening of the US-Canada trade rupture. Canada’s retaliatory tariffs on roughly $20 billion of US goods are now in force, hitting hundreds of products at rates from 15% to 50%, and Washington has responded by excluding Canadian products from major US government contracts while adding fresh import bans on selected dairy, alcohol and motorcycles.
This matters because North America has long been treated as the low-friction fallback for global supply chains. That assumption is now weaker. Bilateral trade is worth more than $1.2 trillion annually, yet more than 70% of Canadian exports still go to the US, leaving firms exposed to policy shocks, procurement risk and rules-of-origin disruption. RBC has warned that if tariffs stay in place for a year, they could add about 0.3 percentage points to Canadian inflation and cut real GDP growth by 0.5 points.
The implication is clear: companies in autos, metals, food and public procurement should stop planning around a quick reset and start planning for a structurally less predictable North American market.
HORMUZ IS NO LONGER JUST AN OIL STORY
The sharpest business signal today is the return of sustained operating risk around the Strait of Hormuz. Iran says it will declare a new exclusion zone near the waterway, while the US says more than 20 warships are enforcing a blockade that has already redirected 92 commercial vessels and disabled three. Even with roughly 9 million barrels per day still moving through the strait, total regional flows are only around two-thirds of pre-conflict levels once pipelines are included. This is not a full supply collapse. It is a cost shock in motion.
That matters far beyond crude. The Strait of Hormuz normally carries about a fifth of global oil supply, and around 19% of global LNG trade, including most LNG exports from Qatar and the UAE. The implication is straightforward: higher tanker rates, rising war-risk insurance, tighter petrochemical and fertilizer costs, and renewed imported inflation risk for Europe and Asia. For boardrooms, the key planning question is no longer whether Hormuz closes, but how long elevated disruption pricing lasts.
A market can have strong GDP growth, competitive wages, and attractive incentives — and still be a bad place for your next investment.
Why?
Because the workforce you need may not actually exist where you need it.
The new Mission Grey Guild newsletter double issue
HEALTH OF NATIONS
looks at human capacity as a business-risk variable:
→ Can you recruit?
→ Do the skills exist?
→ Can the workforce sustain the workload?
→ Who replaces retiring expertise?
→ Can workers adapt to AI and automation?
Because headcount is a stock. Human capacity is a system.
For investors and executives, that affects productivity, capex, expansion, operating costs and continuity.
Read: missiongrey.com/insights/#ne…
🎙️ And listen to Rwizi Rweizooba Ainomugisha’s This Week in Business Risk for more on turning external developments into business intelligence.
missiongrey.com/insights/#po…
🤖 Made with AI

G20 JUST TURNED CHINA RISK INTO A GLOBAL BOARDROOM ISSUE
The most consequential shift in today’s brief is not a new tariff headline, but a broader coalition forming around China risk. At the recent G20 finance meeting, 19 members backed language targeting “non-market” distortions and persistent export-led surpluses, with China the lone dissenter. That matters because this is no longer just a bilateral US-China dispute. Reuters reported China’s exports surged 23.9% year on year in July, while its goods surplus with the EU reached €360.6 billion last year. Ahead of Xi Jinping’s 24 September Washington visit, both sides are discussing tariff relief on roughly $30 billion of non-sensitive goods per side and possible progress on rare earth export licenses.
The implication for business is clear: selective stabilization may emerge in low-sensitivity trade, but broader de-risking pressure is widening across major economies. Companies should plan for segmented access to China, not normalization.
CHIPS NOW COME WITH A GEOPOLITICAL PASSPORT
The most important shift in today’s brief is not a new tariff rate. It is a new business rule: access to the US market is increasingly being tied to where semiconductors are made. Washington is preparing targeted chip tariffs under Section 232, while Commerce Secretary Howard Lutnick has made the logic explicit: build in America, or pay to enter. Taiwan is seeking exemptions linked to US investment, and South Korea is already in talks with Washington under a $350 billion framework to secure treatment “no less favorable” than rivals.
The deeper change is in compliance. In parts of the new regime, proof of origin is no longer enough; firms may need bill-of-materials visibility and supplier-by-supplier traceability. This turns market access into a test of geography, transparency and political trust.
The implication for business is clear: semiconductor strategy is no longer just about cost and technology. It is now about where production sits, how supply chains are documented, and whether capacity will still qualify for preferred access in a fragmented trade order.
RATES, OIL AND GEOPOLITICS ARE COLLIDING
The clearest business signal today is not from one central bank or one conflict, but from their interaction. The US added 162,000 jobs in August, far above expectations, while unemployment held at 4.1%. That strengthens the case for the Fed to stay hawkish, with markets now debating whether rates could rise from the current 3.50%-3.75% range rather than fall.
At the same time, Brent has climbed to roughly $95 as renewed disruption around the Strait of Hormuz keeps energy risk firmly in the inflation outlook. Europe is hardly insulated: the ECB deposit facility stands at 2.25%, but imported energy stress is again complicating the path for industry, margins and borrowing costs.
The implication is straightforward. Boardrooms should stop treating inflation, interest rates and war risk as separate scenarios. They are now one operating environment, with direct consequences for capital costs, freight, pricing power and 2027 planning assumptions.
SANCTIONS ARE TURNING INTO TRADE POLICY
One of the most consequential shifts in today’s risk environment is happening in Washington, not on the battlefield. The US Senate has already passed the Lindsey O. Graham Sanctioning Russia and Iran Act by 86-11, and the bill now moving through the House would allow tariffs of up to 100% on the biggest buyers of Russian oil and gas and on countries helping sanctions evasion.
That would mark a major escalation in secondary-pressure risk. The target is no longer only Russian entities, banks, or the shadow fleet. It is also third-country trade exposure, with China and India squarely in view. This matters because Russia’s “shadow fleet” now carries a large share of its seaborne oil exports, keeping war revenues flowing despite existing restrictions.
The business implication is clear: sanctions screening is becoming a board-level trade issue. Firms with exposure to Russian-origin energy, shipping, insurance, or intermediaries in Asia and the Gulf should prepare for a much wider compliance perimeter.