

Shipping & offshore equity research. 40 stocks, 1,900+ vessels modelled. Follow us for updates
Joined July 2025
- Tweets594
- Following2
- Followers1.4K
- Likes139





Saudi Arabia's critical oil export lifeline has been hit. An attack struck the 1,200km East-West Pipeline in the Medina region, the route currently carrying around 4 million barrels/day to Yanbu to bypass the Strait of Hormuz. Operations remain unaffected.
111
$4bn-plus in newbuilding investment and rental commitments. COSCO is planning 24 additional VLCCs: 10 owned vessels costing $1.42bn and 14 bareboat-chartered ships with up to $2.61bn in rental commitments. A major bet on long-term crude tanker demand.
9
530
West Africa–China VLCC rates have fallen 35% from October's record to $493,106/day yet remain 361% higher over three months. The correction is sharp, but tanker earnings are still extraordinary.
12
659
Shipping's record boom has lasted longer than any since 2000, with earnings in the top 10% for eight consecutive months. Yet secondhand and newbuilding prices remain below their 2008 peaks. Are buyers anticipating the next downturn before it arrives?
1
20
1,338
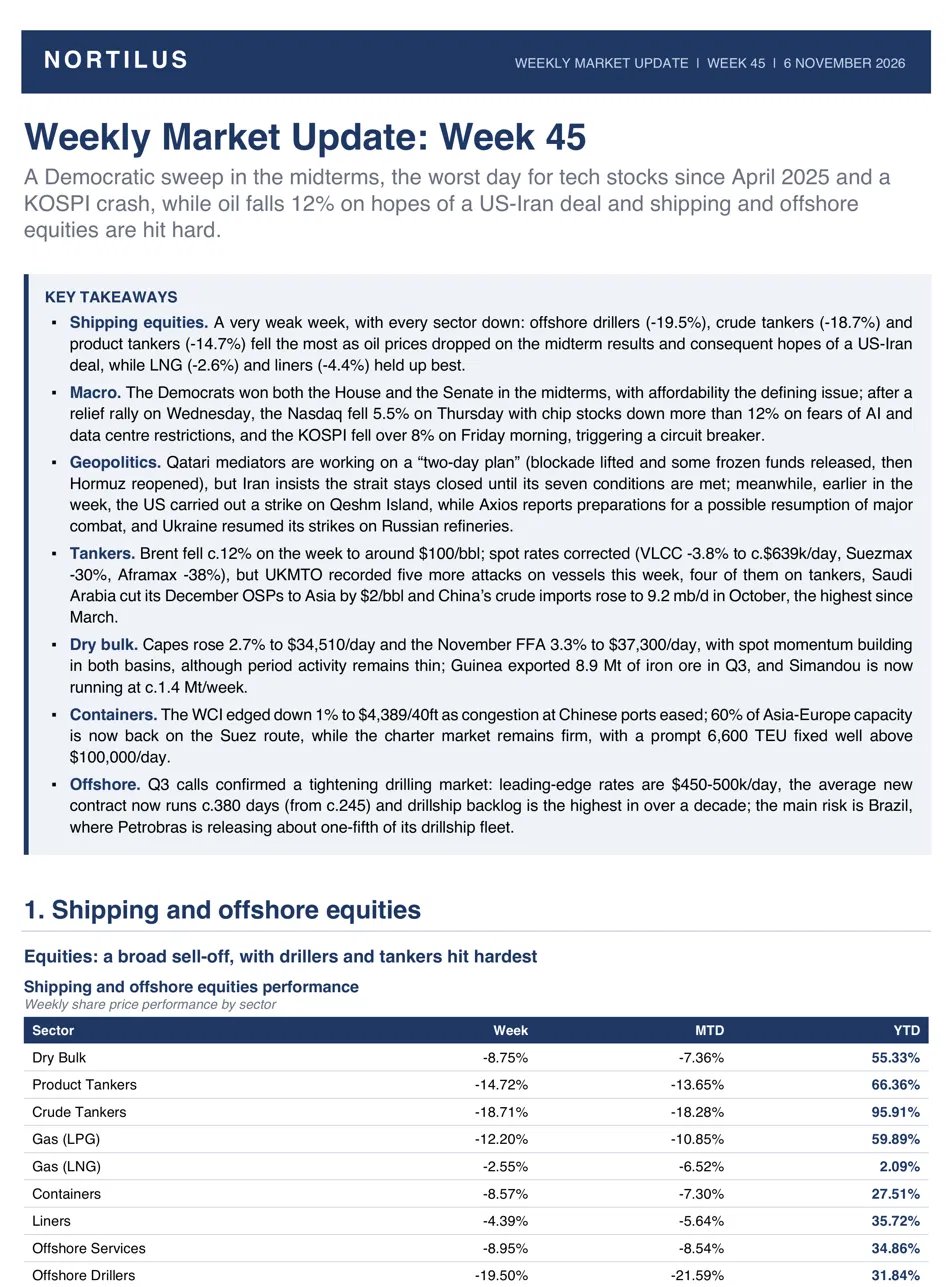
Brutal week for shipping stocks: drillers -19.5%, crude tankers -18.7%, as oil fell 12% on hopes of a US-Iran deal. Yet tankers are still being hit in the Gulf and Iran won’t reopen Hormuz until its seven conditions are met. Free to read on nortilus.com. Sstack link below
#shipping #OOTT
Capital Tankers has secured a 15-month contract for its newly built 155,348 DWT Suezmax Amor at an estimated $160,000–$180,000/day. Total contract revenue could reach $82.2m. That's up to $2.7m every 15 days from a single tanker. Suezmax earnings are entering extraordinary territory.
$NMM Q3: adjusted EPS of $5.66, against $5.44 in our model and $4.32 for consensus. Our estimate was within 4%; consensus was 31% too low. The beat came from rates.
Fleet TCE was $30,371/day, up 26% on a year ago, with dry bulk up 43% to $25,708 and tankers up 38% to $36,183, while containers were flat. Q4 is 80% fixed at about $31,800/day, so the next quarter is largely booked already.
#Shipping #DryBulk #Tankers

Product tanker fleet growth is masking a tightening clean market.
The nominal fleet is up 7% YTD. Yet CPP-trading capacity is DOWN 4%. Around 70 fewer LR2s were trading CPP by end-October, despite 66 newbuildings delivered.
The ships aren't disappearing. They're moving to dirty trades. More ships. Less clean supply.
LR tanker rates are hitting records. But the next move could be DOWN.
Freight has nearly doubled since March, with Middle East Gulf LR1/LR2 availability still ~30% below Q4 2025 averages. Now, laden vessels returning to Asia threaten to release capacity and trigger a sharp rate correction.
1
488
US LPG exports are estimated to rise 13% in 2026, while Middle East exports are forecast to fall 48%. Asian buyers are increasingly looking to long-term US supply deals, potentially reshaping traditional LPG trade routes.
1
409
Dry bulk faces a growing supply-demand squeeze. Demand is forecast to grow 2.6% annually in 2026–29, against 3.8% fleet growth as the orderbook delivers in 2027–28. Rates remain supported for now, but the balance could turn increasingly bearish.
6
552
Simandou's iron ore export outlook is getting bigger. Expectations have risen from 45 million tonnes next year to as much as 65 million tonnes. That's an additional 20 million tonnes of potential cargo demand for the dry bulk market.
4
554