

Neither noise nor guessworks - only insights. Illuminating your investing journey with facts, data, charts, and more. #MarketInsights
Joined June 2025
- Tweets4.1K
- Following76
- Followers4.8K
- Likes2.3K



Pinned Tweet
"2x Volume in next 2 years"
~ CEO, Welspun Corp
Welspun Corp Management Takeaways on Recent $1.8 Bn Order Win
The $1.8 billion order, combined with Welspun’s ongoing US capacity expansion, provides strong volume visibility through FY29.
“From current volumes of 350,000 tons, we are looking at close to 700,000 tons, which is almost 2 times the current volume over the next 2 years.”— Vipul Mathur, MD & CEO
The order is tied to growing US gas production and the need for additional pipeline infrastructure to evacuate gas from the Permian basin.
The $1.8 billion order may not be a one-off. Welspun sees additional large projects developing, although they remain some distance from finalisation.
Debottlenecking, augmentation and the new greenfield facility should leave spare capacity even after accommodating the mega order.
Strong demand and higher capacity utilisation give Welspun the ability to prioritise customers, partners and projects rather than chasing volumes.
Fixed-price contracts are backed by raw-material arrangements, while US orders and raw materials are dollar-linked, protecting profitability from commodity and currency swings.
The US opportunity effectively needs to be served through Welspun’s local manufacturing footprint because tariffs make exports from India unattractive.
Management clarified that the win reflects a long bidding and engagement process rather than a sudden spike in US pipeline spending.

BLS Polymers Ltd: A Specialized Polymer Business with an Interesting MOAT!
30+ years of experience | 90.84% repeat customers | 29.51% ROCE
What makes this business stand out? 🧵👇
1. Specialized Business Model
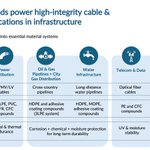
BLS manufactures performance-based polymer compounds used in critical infrastructure.
Key applications:
• Power – HV/MV/LV cables
• Oil & Gas – Pipeline coatings
• Telecom – Optical fibre cables
• Water – Long-distance pipelines
• Renewables – Solar and wind cables
2. Product Customization as a MOAT
• 127 product grades across 6 product lines
• In-house R&D and formulation capabilities
• Customized compounds for electrical, thermal and chemical resistance
• ISO/BIS certifications and government-agency enlistments
Unlike basic polymers, these compounds require application-specific performance and technical validation.
3. Strong Customer Stickiness
• 190+ customers served
• 90.84% repeat customers
• Presence across 24 states and 13 countries
• Long-standing customer relationships
Technical approvals and customized formulations can create switching barriers.
4. Manufacturing Scale
• Installed capacity: 35,251 MTPA
• In-house R&D laboratory
• Focus on advanced compounds, pipeline coatings and cable applications
• Expanding product categories and international reach
5. Strong Financial Metrics – FY26
• Revenue: Rs. 349.43 Cr
• EBITDA: Rs. 46.60 Cr
• PAT: Rs. 27.01 Cr
• EBITDA Margin: 13.3%
• ROE: 33.17%
• ROCE: 29.51%
6. Multiple Industry Tailwinds
BLS is positioned across power infrastructure, oil & gas pipelines, city gas distribution, telecom, water infrastructure and renewable energy.
The Larger Thesis:
BLS Polymers is evolving from a conventional polymer manufacturer into a specialized performance materials supplier.
Its potential MOAT lies in formulation expertise + technical approvals + customer stickiness + diversified applications.
The key monitorable is whether this differentiation translates into sustained margins and profitable growth.
Source: BLS Polymers Investor Presentation | Not investment advice.


#IrisClothingsLimited
*Q2 FY27 Key Financial Highlights*
* Total Income of ₹ 6,222 Lakhs, YoY growth of 40.3%
* EBITDA of ₹ 947 Lakhs, YoY growth of 34.4%
* PAT of ₹ 508 Lakhs, YoY growth of 23.3%
#IrisClothings #FinancialResults

#EmeraldFinanceLimited
The Company has partnered with Kandarp Digi Smart BPO Limited, Uttar Pradesh, to offer its Early Wage Access (EWA) solution to employees, enabling them to access a portion of their earned salary before payday.
#EmeraldFinance #EWA #NBFC #Fintech

📦 LEAP India is expanding its returnable packaging platform through the acquisition of Vimprotech and TIPS.
The two businesses bring different capabilities: Vimprotech adds in-house design and manufacturing, while TIPS expands LEAP’s automotive pooling business.
🏭 Vimprotech brings mould design, tooling and plastic packaging manufacturing capabilities. It reported FY26 revenue of approximately ₹47 crore, with revenue growing at a 23% CAGR over FY24–26.
🔄 TIPS provides reusable crates, lids and inserts to automotive customers, along with cleaning, repair and maintenance services. It reported FY26 revenue of approximately ₹18 crore, with a 25% revenue CAGR over FY24–26.
The deal at a glance:
▪️ Combined acquisition consideration: ₹142 crore through slump sales
▪️ Combined FY26 revenue of the two businesses: approximately ₹65 crore
▪️ Vimprotech brings two manufacturing units in Puducherry and Tamil Nadu
▪️ TIPS adds four warehouses and approximately 2.5 lakh pooled assets
The value creation opportunity: LEAP can cross-sell pallets, crates, containers and material handling equipment to a wider customer base while expanding into industries such as electronics, FMCG and agriculture. Bringing design and manufacturing in-house could reduce external dependence, while shared infrastructure, sourcing and logistics could improve efficiency. Together, these synergies could support a larger, more diversified revenue base and stronger profitability over time.
#LEAPIndia


Ather Energy ~ Demand More Than Doubles, Capacity Expansion Becomes Critical
Ather Energy is witnessing a sharp acceleration in demand, with enquiries and pre-orders growing over 100% YoY in Q2 FY27.
Key Highlights:
- Enquiries: Up 109% YoY to ~10 lakh in Q2 FY27.
- Pre-orders: Up 108% YoY to ~1.8 lakh.
- Wholesale Volumes: Increased 42% YoY to 93,211 units, compared with 65,595 units in Q2 FY26.
- Production Ramp-Up: Average monthly supply increased from ~22,000 units in Q2 FY26 to ~33,000 units in Q2 FY27.
The Interesting Part Is The Demand–Supply Gap.
In Q2 FY27, Ather recorded average monthly enquiries of ~3.34 lakh and pre-orders of ~60,000, against production of ~33,000 units.
To support growth, the company is expanding manufacturing capacity:
- Current Capacity: ~4.2 lakh units annually.
- Hosur Enhancement: Capacity to increase to ~4.9 lakh units.
- AURIC Phase 1: Further expansion to ~9.2 lakh units.
- Additional Enhancement: Total planned capacity of ~11.4 lakh units by Q2 FY28.
The company has also indicated additional investments of Rs. 58 crore in Hosur and Rs. 64 crore in AURIC Phase 1.
The Bigger Picture: Ather is moving from a demand-generation phase towards a manufacturing scale-up phase.
The key question is whether it can convert rising enquiries and pre-orders into deliveries while improving capacity utilisation and operating leverage.
Key Monitorables: Order conversion, production ramp-up, AURIC commissioning and profitability as volumes scale.


🚀 BLS Polymers IPO | Scaling Up for Growth
What makes BLS Polymers interesting? 👇
🔹 Strong Customer Retention: Repeat customers contributed 96.5% of FY26 revenue.
🔹 Expanding Capacity: Plans to increase installed capacity from 35,251 MTPA to 87,301 MTPA by March 2028 — a 2.5x expansion.
🔹 Improving Profitability: FY24–FY26 EBITDA CAGR of 59.8% and PAT CAGR of 89.5%.
🔹 Rising Margins: EBITDA margin improved from 5.5% in FY24 to 12% in FY26 and 14.5% in Q1 FY27.
🔹 Diversified Applications: Specialised polymer compounds for wires, cables and industrial pipelines.
🔹 Strong Return Ratios: FY26 ROE of 28.5% and ROCE of 30%.
🔹 Infrastructure-Led Opportunity: Exposure to demand from power transmission, renewable energy, telecom, construction and pipeline infrastructure.
📌 IPO Snapshot
📅 27–29 October 2026
💰 Price Band: ₹142–150
📊 Issue Size: ₹255 Cr (Fresh Issue)
A capacity expansion story backed by customer stickiness and improving profitability, with supplier concentration, raw-material volatility and single-facility dependence among the key risks to watch.
#BLSPolymers #IPO #IPOAnalysis #IndianStockMarket #Investing

Ather Energy ~ Demand More Than Doubles, Capacity Expansion Becomes Critical
Ather Energy is witnessing a sharp acceleration in demand, with enquiries and pre-orders growing over 100% YoY in Q2 FY27.
Key Highlights:
- Enquiries: Up 109% YoY to ~10 lakh in Q2 FY27.
- Pre-orders: Up 108% YoY to ~1.8 lakh.
- Wholesale Volumes: Increased 42% YoY to 93,211 units, compared with 65,595 units in Q2 FY26.
- Production Ramp-Up: Average monthly supply increased from ~22,000 units in Q2 FY26 to ~33,000 units in Q2 FY27.
The Interesting Part Is The Demand–Supply Gap.
In Q2 FY27, Ather recorded average monthly enquiries of ~3.34 lakh and pre-orders of ~60,000, against production of ~33,000 units.
To support growth, the company is expanding manufacturing capacity:
- Current Capacity: ~4.2 lakh units annually.
- Hosur Enhancement: Capacity to increase to ~4.9 lakh units.
- AURIC Phase 1: Further expansion to ~9.2 lakh units.
- Additional Enhancement: Total planned capacity of ~11.4 lakh units by Q2 FY28.
The company has also indicated additional investments of Rs. 58 crore in Hosur and Rs. 64 crore in AURIC Phase 1.
The Bigger Picture: Ather is moving from a demand-generation phase towards a manufacturing scale-up phase.
The key question is whether it can convert rising enquiries and pre-orders into deliveries while improving capacity utilisation and operating leverage.
Key Monitorables: Order conversion, production ramp-up, AURIC commissioning and profitability as volumes scale.


Indian Telecom trades at premium to global peers on the thesis of lower ARPU
Given that leaves potential upside for ARPU

Blinkit vs Instamart ~ The Execution Gap Is Getting Wider
“I think our competitor, Blinkit, enjoys a pretty strong flywheel that has been compounding over the years. That is the reason why they’ve been able to build a more resilient business........I think our first job is to build a stable, resilient business that has clearest line of sight to EBITDA zero. The optionalities come after that.”
The numbers explain why this matters.
- Mid-2024: Blinkit's net order value (NOV) was ~1.7x Instamart's.
- Now: The gap has widened to ~3.2x.
- Relative scale: Blinkit's NOV advantage has nearly doubled over this period.
This is more than a market-share story.
Higher order density can improve delivery economics, support greater assortment and attract more customers, creating a compounding advantage.
For Instamart, the challenge is no longer just expanding aggressively. It is about improving execution, narrowing the scale gap and building a sustainable path to profitability.
The Bigger Question: Can Instamart improve its unit economics while Blinkit continues to compound its scale advantage?
A closer look at how this execution gap has evolved over the last 10 quarters.
Source: Company earnings commentary and reported NOV figures.

India's Next Capex Supercycle ~ Trillions Of Rupees In Investment Across 12 Emerging Sectors
India is preparing for a major investment cycle, supported by government incentives, private-sector capex and rising demand for advanced technologies.
Key Investment Opportunities:
Semiconductors: ~₹5.27 lakh crore in targeted public and private investment through 2032, including major semiconductor fabrication projects.
Artificial Intelligence: Over $71 billion in indicated investments, led by global technology companies and India's AI Mission.
Data Centres: Potential investment opportunity of up to $200 billion by 2035, driven by AI computing, cloud adoption and digital infrastructure.
Defence Manufacturing: ~₹5.07 lakh crore of combined contract and investment figures, reflecting rising domestic manufacturing opportunities.
Green Hydrogen: ~₹2.04 lakh crore in planned support and investment, with opportunities across electrolysers, renewable power and industrial decarbonisation.
Renewable Energy: ~₹97,065 crore of budgeted and private investment figures for the FY27 cycle, supporting India's 500 GW non-fossil capacity ambition by 2030.
EV & Battery Storage: ~₹80,300 crore in public support and private investment, with battery manufacturing and localisation emerging as major themes.
Biotechnology: ~₹2.31 lakh crore in government support, state targets and announced investments, supporting biopharma manufacturing and innovation.
Critical Minerals & Rare Earths: ~₹42,580 crore in India-specific commitments to strengthen mineral security and domestic processing.
Space, Drones & GCCs: Growing opportunities across private space technology, unmanned systems and demand-led expansion of global capability centres.
The Bigger Picture: India's next investment cycle could be increasingly driven by technology, energy security, defence indigenisation and advanced manufacturing, rather than conventional infrastructure alone.
The Investment Angle: The biggest beneficiaries may not necessarily be the companies announcing the largest capex, but the suppliers of equipment, components, engineering services and critical technologies supporting these investments.


Magellanic Cloud Limited’s wholly owned subsidiary, Provigil Surveillance Limited, secured a ₹3.16 Cr LOA from DFCCIL Jaipur for CCTV surveillance, centralized monitoring and video analytics across the Western Dedicated Freight Corridor, with installation within 90 days and five years of O&M.
#MagellanicCloud #Railways #Surveillance

#ForcasStudioLimited
#H1FY27 Key Results Highlights
* Total Income of ₹1,310.17 Mn, up 56%
* EBITDA of ₹153.06 Mn, up 73%
* EBITDA Margin of 11.74%, up 115 BPS
* PAT of ₹99.91 Mn, up 72%
* PAT Margin of 7.63%, up 69 BPS
* EPS of ₹5.68, up 72%
#FinancialResults

Sterlite Technologies (STL) ~ ₹18,618 Cr Record Order Book, $1.11 Billion AI Data Centre Deal And Net Debt-Free Balance Sheet
Sterlite Technologies is witnessing a significant business transformation, driven by rising AI infrastructure demand, hyperscaler orders and improving profitability.
Key Highlights:
1. Record Q1 FY27 Financial Performance
Revenue: ₹1,910 Cr, up 87% YoY.
EBITDA: ₹397 Cr, up 184% YoY.
PAT: ₹197 Cr.
EBITDA margin reached 20.8%, its highest level in nearly 20 quarters.
2. Order Book Reaches An All-Time High
Outstanding order book: ₹18,618 Cr.
Order intake increased from ₹7,687 Cr in FY26 to ₹13,100 Cr in Q1 FY27, a 1.7x increase.
The expanding pipeline provides multi-year revenue visibility, subject to order execution.
3. Landmark $1.11 Billion AI Data Centre Award
Secured a $1.11 billion (₹10,000+ Cr) product award letter from a global hyperscaler.
Optical connectivity products will support next-generation AI data centres during FY27–FY29.
This could establish AI infrastructure as a major growth driver for STL.
4. Additional Hyperscaler Orders
Secured $100 million+ in orders for its Neuralis integrated data centre connectivity portfolio.
Also won a strategic order for long-haul, dark-fibre high-density micro-cables.
5. Significant Balance Sheet Improvement
Raised ₹1,500 Cr through QIP.
Achieved net debt-free status.
ICRA upgraded its credit rating to AA (Stable), while CRISIL revised its outlook to Stable.
6. Higher-Margin Business Mix
The increasing contribution from AI data centres and specialised optical connectivity products is supporting operating leverage and profitability.
The Bigger Picture: STL is transitioning from a traditional optical fibre manufacturer towards a broader AI-ready digital infrastructure and connectivity solutions provider.
The combination of a record order book, improving margins and a stronger balance sheet creates significant growth potential.


Hindustan Zinc ~ Silver Emerges As A Major Earnings Driver, With Every $1 Price Increase Adding ₹200–225 Crore To EBITDA
Hindustan Zinc (HZL) is increasingly benefiting from rising silver prices, strong production growth and improving zinc cost economics.
Key Takeaways:
1. Silver Becomes A Key Profit Contributor
Silver contributed 28% of segment revenue in Q2 FY27.
Accounted for 43% of segment EBIT, highlighting its disproportionate profitability contribution.
Silver segment revenue surged 141% YoY to ₹4,111 Cr.
Segment EBIT increased 147% YoY to ₹3,609 Cr, with an impressive 88% EBIT margin.
2. Significant Earnings Sensitivity To Silver Prices
According to JM Financial, every $1 per troy ounce increase in silver prices could add approximately ₹200–225 Cr to annual EBITDA, assuming other factors remain unchanged.
This creates substantial earnings leverage to higher silver realisations.
3. Structural Silver Supply Deficit
Motilal Oswal expects the global silver market to remain in deficit for the sixth consecutive year in 2026.
Projected shortfall: ~144 million ounces.
Industrial demand and constrained supply could support silver prices.
4. Silver Production Guidance Maintained
Q2 silver production increased 16.1% QoQ to 173 tonnes.
FY27 production guidance remains 680 tonnes.
Management indicated potential production of 730–750 tonnes by FY28.
5. Zinc Business Also Strengthening
Q2 FY27 revenue increased 76.5% YoY to ₹15,093 Cr.
EBITDA more than doubled to ₹9,248 Cr.
Zinc production cost, excluding royalty, declined from $994/tonne to $703/tonne.
FY27 zinc cost guidance reduced to $825–850/tonne, from $975–1,000 earlier.
6. Long-Term Capacity Expansion
HZL's planned 250,000-tonne integrated zinc capacity addition at Debari is targeted for completion in Q2 FY29.
Refined metal capacity could increase from 1.1 million tonnes to 1.4 million tonnes annually.
The Bigger Picture: Hindustan Zinc is developing a powerful combination of silver price leverage, rising silver volumes, lower zinc production costs and long-term capacity expansion.
Silver is becoming an increasingly important earnings driver, while operational efficiencies in zinc provide an additional profitability lever.
Key Monitorables: Silver prices, FY27 production guidance, zinc cost sustainability and execution of the Debari expansion.
Source: Supplied newspaper report, 22 October 2026, citing JM Financial, Motilal Oswal and company management commentary. Price sensitivity is an estimate, not guaranteed earnings.

India's Pharma CDMO Industry ~ Shifting From Low-Cost Manufacturing To Complex, High-Value Products
India's pharmaceutical CDMO industry is entering a new growth phase, with biologics, peptides, GLP-1 drugs and sterile injectables emerging as key opportunities.
Key Takeaways:
1. A Large Global Opportunity
Global CDMO market exceeded $140 billion in 2024.
India currently accounts for just 2–3% of the market.
McKinsey estimates India could capture 8–10% of the global CDMO market by 2033.
2. Shift Towards Complex Products
The next growth cycle is expected to be driven by:
Biologics and biosimilars
Peptides, including GLP-1 therapies
Sterile injectables
Drug-device combinations
These products require specialised manufacturing capabilities and regulatory expertise, potentially creating higher entry barriers.
3. OneSource Specialty Pharma ~ Scaling Complex Manufacturing
FY26 revenue: ₹1,421.6 Cr
EBITDA: ₹304.2 Cr, up 35%
Management expects FY28 organic revenue of approximately $400 million, with ~40% EBITDA margins.
Near-term performance remains affected by delayed semaglutide approvals and higher ramp-up costs.
4. Akums Drugs ~ Building Beyond Formulations
FY26 consolidated revenue grew 5.9% to ₹4,359 Cr.
EBITDA increased 13.3% to ₹522 Cr.
CDMO contributes approximately 80% of revenue.
Expanding into newer segments while strengthening its regulated-market presence.
5. Kilitch Drugs ~ Expanding Sterile Manufacturing
FY26 revenue increased to ₹235.47 Cr, from ₹198.32 Cr.
Focused on sterile injectables and expanding manufacturing capabilities.
6. Global Supply-Chain Diversification
Geopolitical developments, including the US Biosecure Act, could encourage pharmaceutical companies to diversify their manufacturing partners, creating opportunities for Indian CDMOs.
The Bigger Picture: India's CDMO opportunity is evolving from manufacturing scale and cost competitiveness towards complexity, regulatory compliance and specialised capabilities.
Companies that successfully commercialise higher-value products could benefit from stronger customer relationships and better margins.
Key Monitorables: Regulatory approvals, commercialisation timelines, capacity utilisation, customer additions and returns on specialised manufacturing investments.
Source: Business Standard, 22 October 2026, citing BCG, McKinsey and company management commentary. Forecasts are estimates.

ITC ~ Acquisitions Emerging As A Key Growth Driver, With FMCG Scale-Up And Margin Expansion In Focus
ITC is increasingly using acquisitions to accelerate its FMCG expansion, strengthen its brand portfolio and enter new consumption categories.
Key Takeaways From CMD Sanjiv Puri's Interview:
1. Acquisitions Becoming A Major Growth Lever
ITC's FMCG business now spans 30+ brands, addressing an estimated ₹8 trillion market opportunity by 2035.
Recent acquisitions include Yoga Bar, Mother Sparsh and Prasuma.
Strategy focuses on acquiring promising brands and scaling them through ITC's distribution and operational capabilities.
2. Aashirvaad Crosses ₹10,000 Crore
Aashirvaad has emerged as a ₹10,000+ crore consumer-spend brand.
Sunfeast has crossed ₹7,000 crore.
Bingo! has surpassed ₹4,600 crore.
These brands demonstrate ITC's ability to build and scale large consumer franchises.
3. FMCG Profitability Improving
Non-cigarette FMCG revenue increased from ₹10,000 crore in FY17 to ₹24,000 crore in FY26.
EBITDA margins expanded by approximately 740 basis points during this period.
Management aims to improve margins by another 180–200 basis points on an annualised basis over the next few years.
4. Value-Added Agriculture Gains Importance
Agri-business expanded from ₹8,000 crore to ₹20,000 crore despite global disruptions.
Value-added agriculture has grown 33% annually over the last five years.
Focus areas include spices, coffee and biological extracts.
5. Hotels And Paperboards Offer Additional Opportunities
ITC plans to expand its asset-light hotel portfolio from around 100 properties in 2017 to over 150.
Paperboards and IT businesses are also being positioned for growth.
6. Organisational Restructuring To Support Scale
ITC is developing 25 business heads across categories to improve accountability and execution.
Management remains open to further acquisitions where strategic fit and valuations are attractive.
The Bigger Picture: ITC is working towards reducing dependence on traditional businesses by building a larger, more profitable FMCG platform.
The key investment opportunity lies in scaling acquired brands, expanding FMCG margins and increasing the contribution of value-added businesses.
Key Monitorables: FMCG organic growth, acquisition returns, margin expansion, capital allocation and profitability of new categories.
Source: Supplied newspaper interview with ITC CMD Sanjiv Puri.
