

Stock Market + Conservation, Wild Life. Have no stock specific advice to give. I have NO group. Not on any SM other than Twitter
Joined February 2022
- Tweets14.3K
- Following388
- Followers26.7K
- Likes29.3K
Pinned Tweet
🚨 MILLWORK TECHNOLOGIES – CONSPIRACY THEORY. 👁️Staring at Rs.100Cr Hole in the Wall
First the background, which everybody chose to ignore because there was a lot of hype driven by massive Rs.160Cr issue
Originally, the promoters founded V3 Technologies in 2015. The business was pretty bad and grew VERY SLOWLY to Rs.9.6Cr in Fy24 and 22Cr in Fy 25. YES Rs.22Crore ONLY in FY25.
In between, in FY 22, Promoters founded MILLWORKS TECHNOLOGIES but continued to carry out the works under V3 Technologies only, “grinding” their way to Rs.22Cr.
V3 Technology’s manufacturing Unit was taken on Lease in Millworks Name, in January 2024 only.
2 More small sheds (Unit 2 & Unit3) with machining equipments in Peenya were taken on lease in March and Nov 2024 .
Then in Jan 2025 it took on lease Unit 4 shed which is somewhat large with aim to expand business using proposed IPO funds. Since there was not much business operation, part of this UNIT 4 has been leased out (even now to a third party) for Rs.65,000 per month. PLEASE NOTE THIS!! 😆
So we can see, the company has small workshops only which generated Rs.22Cr max in Fy25. (The large Unit was not operational because machines are not there and needed funds to buy)
To buy large number of CNC Machines huge funds are needed (IPO was estimated for Rs.160Cr).
With measly Rs.22Cr turnover, it is impossible to raise Rs.160Cr from market
That is the background which all of us IGNORED due to the hype.
Now the CONSPIRACY THEORY! 🚨
With insignificant machining business in old run-down sheds, the people behind, must have come up with idea to cook the books and show HUGE turnover in FY26 with fake orders.
A company with pitiable machining capacity and 22Cr turnover in FY25, SUDDENLY BALLOONED to Rs.148Cr in Fy26. WOW! 😜
Considering the lame duck business growth history of V3 Technologies as well as the promoters, we can assume company, at best, would have got around 40 to 45Cr orders in FY26, with addition of sheds (Unit 2 &3) (ie Against Rs.22Cr reported in Fy25)
Even with Rs.45Cr, it will not be enough to raise 160Cr in IPO. No one will accept that. So another 100Cr must have been COOKED UP. Out of this 100Cr around Rs.70Cr is mentioned as work order from QUICKPAY SERVICES for Drone Parts in the RHP. Rest is not specifically stated. But from Auditor comments around Rs.97.5Cr is fake.
Since MILLWORKS has NO machining capability to make drone parts, it is stated in RHP, that this work is being done by Chennai based BIG BANG BOOM TECHNOLOGIES. (this should have been a RED Flag for Investors. Such a BIG Over HYPED company has no capability??) 🚨
Now, it can be safely presumed, there is absolutely NO NEED for QUICKPAY which has to supply high security, high performance drones to the Defense Forces, to place order on a incapable company like MILLWORKS, only to get it made by BIG BANG! 😜
From the AUDITOR QUALIFICATION it is obvious that there is no substance or back up for this order. 🚨
“We could not obtain sufficient and appropriate evidence about whether the trade receivables and the advances due from this party are recoverable” - Auditor🚨
In simple terms, these are fraud entries. (This is Conspiracy Theory) That is about Rs.97.5Crore.
This means, QUICKPAY went ahead and got works done by BIG BANG BOOM and MILLWORKS is NOWHERE in the picture. 🚨
Whatever money is collectable as per books, is NOT COLLECTABLE at all, since QUICKPAY must have already paid money for the works to BIG BANG and it got the stuff made by them. (this is CONSPIRACY THEORY) 😆
Since Millworks does not have precision machining capability to do such works, anyway it could not have done the job. (If it had capability, it would have done the job by itself)
So, we have an IPO, claiming company has Rs.148Cr turnover in Fy26 but with an almost Rs.100Cr HOLE in that.
May be, like in the case of C2C, @sebi_updates need to have a serious look at this fiasco, to check whether there is any substance in the conspiracy theory, especially since Auditor has raised RED FLAG.
REMEMBER, THIS IS CONSPIRACY THEORY!! DON’T BELIEVE THIS. 👍

🔴 MILLWORKS TECHNOLOGIES FY27 H1 RESULTS. H1FY27 RESULTS. Rs.864 was at 41p/e. Now 69x 👎
🚨FIRST QUALIFIED OPINION OF THIS SEASON: Auditor has expressed Doubt about Rs.87Cr receivable from a party who also seem to have been given Rs.10.6Cr as Advance! So Rs.97 Cr is in Doubt.
🔴(Extremely negative to have a Qualified Opinion by Auditor.👎 Generally only useless scam companies end up in such an Audit situation) . There could be further impact on future financials, if this remain non collected.
FROM IPO REVIEW “Company was formed in 2015 as V3 Technologies and the business grew slowly to Rs.9.6Cr in Fy24 and 22Cr in Fy 25. BIG topline growth to Rs.148Cr in Fy26 was driven by subcontract order from QuickPay Services”
Millworks was supplying drone parts to QUICKPAY through BIG BANG SOLUTIONS.
Most likely QUICKPAY could be the defaulter. Probably due to quality issues Indian Army rejected the QuickPay drones? QUESTIONS WILL BE ASKED.
Receivable Rs.148Cr. CFO –ive Rs.72Cr
H1 FY27 Vs.H2 FY26
REV: Rs.18Cr Rs. Vs Rs. 108Cr 🔴
PAT: Rs. (-)1.8Cr Vs Rs. 24Cr 🔴
(May Compare with H1FY26 Rev=Rs. 45.8Cr & PAT=Rs.12.5 Cr ) VERY BAD 👎
TTM Vs FY26
REV: Rs.126Cr Vs Rs. 153Cr 👎
PAT: Rs. 22.2Cr Vs Rs. 36.4Cr 👎
SME IPO was in JULY 2026 at Rs.331
👍AMTECH ESTHERS FY27 H1 RESULTS. H1FY27 RESULTS. Rs.78 was at 17 p/e. Now 13x 👍
Unsaturated Polymer Resin (UPR) maker
There is ongoing expansion. Might get ready soon
👉Company is in the process of expanding the UPR capacity at a new facility (UNIT2) which is expected to be operational in Q3 or Q4 Fy26 (Shortly) .
This expansion takes existing UPR capacity of 2960 MTPA to 7760 MTPA. (2.6x)👍
H1 FY27 Vs.H2 FY26
REV:Rs. 27.5Cr Rs. Vs Rs. 23.5Cr 👍
PAT:Rs. 2.3Cr Vs Rs. 2.8Cr 👎
(May Compare with H1FY26 Rev=Rs. 21Cr & PAT=Rs. 1.3Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.51Cr Vs Rs. 41Cr👍
PAT: Rs. 5.1Cr Vs Rs. 4Cr👍
SME IPO was in SEPT 2026 at Rs.75

📌 Amtech Esters Ltd informed the exchange about its approval for the financial results for the period ended . #SME #AMTECH 📄🧾


1
10
2,817
🫱PRAMODINI MEDICARE FY27 H1 RESULTS. H1FY27 RESULTS. Rs.105 was at 13.5p/e. Now 13.9 x 🫱
This H is dull. 🫱
But there is FUTURE scope IF 👍company executes capex Quickly.
IPO lead capex of Rs.45Cr to buy CT Scan machines
This can give good boost in Hy28 H1 onwards (next year)
Radiology diagnostic service provider which operates CT, MRI, PET-CT, and X-ray etc at Govt Hospitals & PSUs (61% revenue) and Private Clinics (21% Revenue) and own centers (18% Revenue)
H1 FY27 Vs.H2 FY26
REV:Rs. 38Cr Rs. Vs Rs. 34Cr 👍
PAT:Rs. 8.3Cr Vs Rs. 8.4Cr 🫱
(May Compare with H1FY26 Rev=Rs. 28Cr & PAT=Rs. 9Cr )
TTM Vs FY26
REV:Rs.72Cr Vs Rs.62 Cr 👍
PAT: Rs. 16.7Cr Vs Rs. 17.4Cr 🫱
SME IPO was in AUG 2026 at Rs.118
📌 Pramodini Medicare Limited informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #PRAMODINI 📄🧾


11
2,846
Vegorama Punjabi Angithi FY27 H1 RESULTS. H1FY27 RESULTS. Rs.282 was at 39p/e. Now 29x👍
Cloud Kitchen in NCR region. Has shown appetite for growth. GOOD!👍
There is Rs.30Cr IPO funded expansion of cloud kitchens, centralized kitchen, delivery points and a fine dining restaurant👍
H1 FY27 Vs.H2 FY26
REV:Rs. 100Cr Rs. Vs Rs. 73Cr 👍
PAT:Rs. 10.4Cr Vs Rs. 5.6Cr👍
(May Compare with H1FY26 Rev=Rs. 68.5Cr & PAT=Rs. 6.4Cr ) VERY GOOD 👍
TTM Vs FY26
REV:Rs.173Cr Vs Rs. 141Cr👍
PAT: Rs. 16Cr Vs Rs. 12Cr👍
SME IPO was in MAY 2026 at Rs.77


🫱MOTHER NUTRI FOODS FY27 H1 RESULTS. H1FY27 RESULTS. Rs.155 was at 17p/e. Now SAME🫱
Peanut butter maker. It is a contract manufacturer for major consumer brands
ALERT:🔻CAPEX IS STUCK. SOMETHING WRONG. BE CAREFUL. UTILIZATION report shows nothing has been spent. IPO was in DEC 2025
(Rs.23Cr IPO lead Capacity Expansion was planned to add 7200MTPA capacity. Taking total capacity to 15200MTPA from current 8000MTPA level.)
H1 FY27 Vs.H2 FY26
REV:Rs. 74Cr Rs. Vs Rs. 74Cr 🫱
PAT:Rs. 7Cr Vs Rs. 6.4Cr 🫱
(May Compare with H1FY26 Rev=Rs.50 Cr & PAT=Rs. 5.3Cr ) JUST OKAY
TTM Vs FY26
REV:Rs.128Cr Vs Rs. 123Cr 👍
PAT: Rs. 11.4Cr Vs Rs. 11.6Cr🫱
SME IPO was in DEC 2025 at Rs.117
📌 Mother Nutri Foods Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #MNFL 📄🧾


11
2,982
👍Speciality Medicines FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 169 was at 11.5p/e. Now 8.8 x👍
One of many small pharma distributors. Some click. Most fail. This one seem to have got some legspace, in this H1 period. May be it has good team. 👍
The growth in H1 is at the cost of op margin
H1 FY27 Vs.H2 FY26
REV:Rs.87 Cr Rs. Vs Rs. 46Cr 👍👍
PAT:Rs. 9Cr Vs Rs.8 Cr👍 but op margin fell
(May Compare with H1FY26 Rev=Rs. 30Cr & PAT=Rs. 5Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.133Cr Vs Rs. 76Cr 👍
PAT: Rs. 17Cr Vs Rs. 13Cr 👍
SME IPO was in March 2026 at Rs.124
📌 Speciality Medicines Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #SPML 📄🧾


1
11
3,210
GALLARD STEEL FY27 H1 RESULTS. H1FY27 RESULTS. Rs.142 was at 15p/e. Now 12x
Castings for Railways – Like Neeetu Yoshi
Company has 2400MTPA capacity. It is running above 90% utilization level. Capex of 21Cr will be at existing factory sites. Capex will increase capacity from 2400MTPA to 6100MTPA
Capex completion expected by Q4 Fy27.
Stock may move once there is news of Capex progress/ Trial operation
H1 FY27 Vs.H2 FY26
REV:Rs. 39Cr Rs. Vs Rs. 37Cr👍
PAT:Rs. 6.3Cr Vs Rs. 4.8Cr👍
(May Compare with H1FY26 Rev=Rs.32 Cr & PAT=Rs. 4.3Cr ) OKAY GOOD 👍
TTM Vs FY26
REV:Rs.76Cr Vs Rs. 70Cr👍
PAT: Rs. 11Cr Vs Rs. 9Cr👍
SME IPO was in NOV 2025 at Rs.150
📌 Gallard Steel Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #GALLARD 📄🧾


2
11
3,663
🫱CLN ENERGY FY27 H1 RESULTS. H1FY27 RESULTS. Rs.390 was at 19.6p/e. Now 21.5x 👎
CLN was suppose dto do far better than MAXVOLT. But Maxvolt has been a complete surprise with faster growth while CLN struggles
Not a good show when EV Battery demand is exploding 👎
H1 FY27 Vs.H2 FY26
REV:Rs. 174Cr Rs. Vs Rs. 198Cr 👎
PAT:Rs. 7Cr Vs Rs. 12Cr 👎👎
(May Compare with H1FY26 Rev=Rs. 153Cr & PAT=Rs. 9Cr )
TTM Vs FY26
REV:Rs.372Cr Vs Rs. 351Cr 👍
PAT: Rs. 19Cr Vs Rs. 21Cr👎
SME IPO was in JAN 2025 at Rs.250
📌 CLN Energy Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #CLN 📄🧾


1
8
3,285
🫱NEETU YOSHI FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 195 was at 30 p/e. Now SAME🫱
Guidance was for around 200Cr in Fy27 (June Concall) Need a super strong H2.👍
H1 FY27 Vs.H2 FY26
REV:Rs. 59Cr Rs. Vs Rs. 55Cr👍
PAT:Rs. 12Cr Vs Rs. 13Cr🫱
(May Compare with H1FY26 Rev=Rs. 46Cr & PAT=Rs. 12Cr ) OKAY 🫱
TTM Vs FY26
REV:Rs.114Cr Vs Rs. 101Cr👍
PAT: Rs. 25Cr Vs Rs. 25Cr🫱
SME IPO was in JULY 2025 at Rs.75
📌 Neetu Yoshi Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #NEETUYOSHI 📄🧾


👍BONDADA ENGINEERING FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 272 was at 14.9p/e. Now 13.3x👍
OVERALL FLAT 🫱
Since stock has moved to Main Board many factors like Quarterly reporting, Debt, CF, Receivables and various ratios will get into play. It wont be easy life like in SME Board.
H1 FY27 Vs.H2 FY26
REV:Rs. 1427Cr Rs. Vs Rs.1633Cr 👍
PAT:Rs. 111Cr Vs Rs. 117Cr 👎
(May Compare with H1FY26 Rev=Rs.1218 Cr & PAT=Rs. 94Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.3060Cr Vs Rs. 2851Cr 👍
PAT: Rs. 228Cr Vs Rs. 211Cr 👍
SME IPO was in AUG 23 at Rs.75 (After Split it is Rs.15)
3
20
5,177
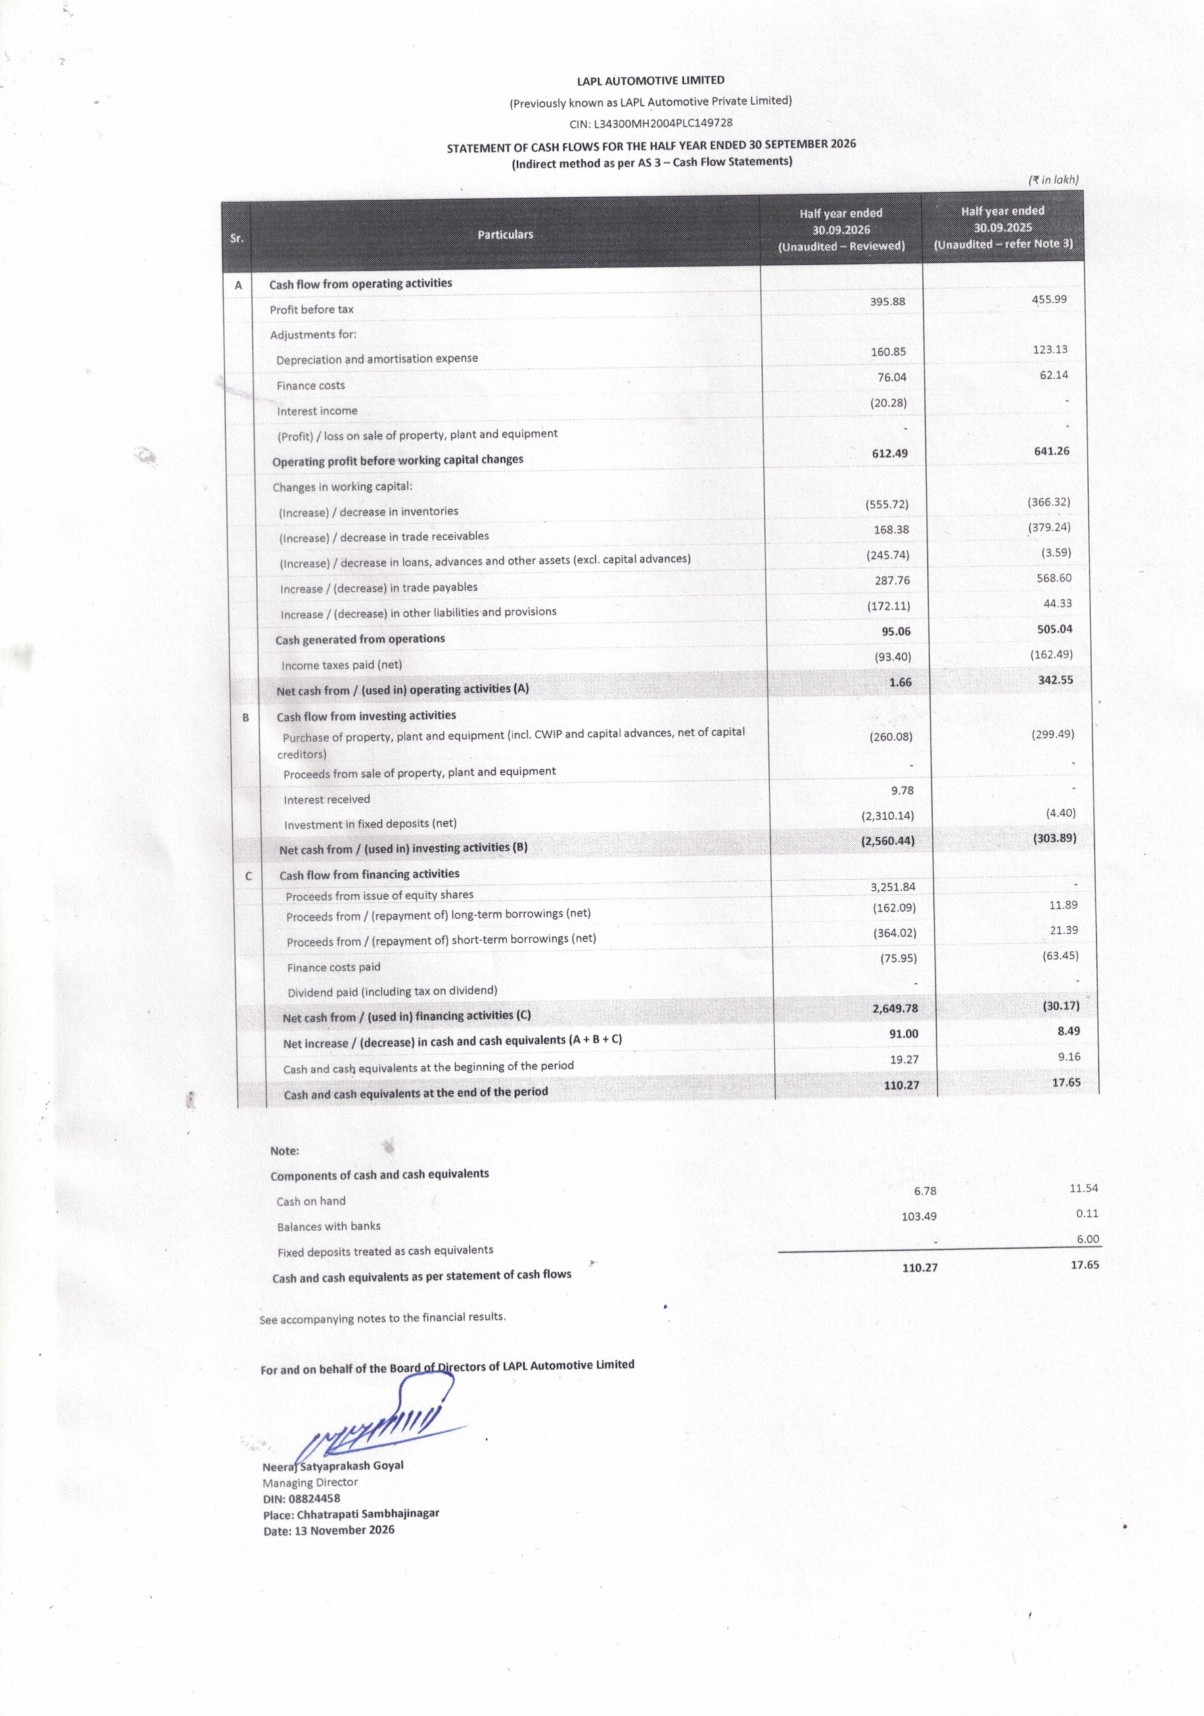
🫱LAPL AUTOMOTIVE FY27 H1 RESULTS. H1FY27 RESULTS. Rs.102 was at 15 p/e. Now SAME. FLAT🫱
OVERALL FLAT 🫱
As per Review for 2 years it can be just flat growth, This is because the unit has no spare capacity, And for new unit, company has given 18 months time line. There was no point in investing except for any listing gain. IPO REVIEW LINK: xitter.gq/RajStockWatch/status/2…
H1 FY27 Vs.H2 FY26
REV:Rs. 44Cr Rs. Vs Rs.52 Cr 👎
PAT:Rs. 3Cr Vs Rs. 4.9Cr 👎
(May Compare with H1FY26 Rev=Rs. 42Cr & PAT=Rs. 3.3Cr ) FLAT 🫱
TTM Vs FY26
REV:Rs.96Cr Vs Rs. 94Cr 👍
PAT: Rs. 7.9Cr Vs Rs.8.2Cr 🫱
SME IPO was in AUG 2026 at Rs.94
📌 LAPL Automotive Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #LAPL 📄🧾


8
3,589
👍VVIP INFRATECH FY27 H1 RESULTS. H1FY27 RESULTS. Rs.154 was at 13p/e. Now 9x 👍
This company is also into real estate development (Builder) apart from civil work contracts. > 50% revenue in this H1 is from Real Estate Sales. Market has placed it in contractor category only if we look at the low valuation
H1 FY27 Vs.H2 FY26
REV:Rs. 264Cr Rs. Vs Rs. 155Cr 👍
PAT:Rs. 31Cr Vs Rs. 12Cr 👍👍
(May Compare with H1FY26 Rev=Rs.194Cr & PAT=Rs. 18Cr ) VERY GOOD 👍
TTM Vs FY26
REV:Rs.419Cr Vs Rs. 345Cr 👍
PAT: Rs. 43Cr Vs Rs. 30Cr 👍👍
SME IPO was in JULY 24 at Rs.93
📌 VVIP Infratech Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #VVIPIL 📄🧾


1
16
4,069
👍SOLARIUM GREEN FY27 H1 RESULTS. H1FY27 RESULTS. Rs.110 was at 11.5 p/e. Now 10.5 x👍
Good topline, But debt costs and Depreciation has started biting.👎 Small problem in topline and the Solar cart will topple. (be cautious - It's segment biz problem) Just like Vikram Solar, there is threat for all solar companies which have done capex.
H1 FY27 Vs.H2 FY26
REV:Rs. 312Cr Rs. Vs Rs. 253Cr👍
PAT:Rs. 10.5Cr Vs Rs. 11.3Cr👎 (Int+Depr hurts)
(May Compare with H1FY26 Rev=Rs. 120Cr & PAT=Rs. 9Cr ) GOOD but margin reduced
TTM Vs FY26
REV:Rs.765Cr Vs Rs. 376Cr 👍
PAT: Rs. 21.8Cr Vs Rs. 20.4Cr 🫱
SME IPO was in FEB 2025 at Rs.191
📌 Solarium Green Energy Ltd informed the exchange about its approval for the financial results for the period ended . #SME #SOLARIUM 📄🧾


1
9
3,838
🫱EVERESTIMS TECHNOLOGIES FY27 H1 RESULTS. H1FY27 RESULTS. Rs.85 was at 14 p/e. Now 11x👍
This is a regular small IT player. Not much expected from this. VK somehow got into this and that was supposed to boost stock. But that has not happened. So, not much use hanging around?
H1 FY27 Vs.H2 FY26
REV:Rs. 28Cr Rs. Vs Rs. 42Cr👎
PAT:Rs. 2.6Cr Vs Rs. 10.2Cr👎👎
(May Compare with H1FY26 Rev=Rs. 24Cr & PAT=Rs.2.8Cr ) - JUST OKAY 🫱
TTM Vs FY26
REV:Rs.70Cr Vs Rs. 66Cr👍
PAT: Rs. 16.8Cr Vs Rs. 13Cr👍
SME IPO was in OCT 2026 at Rs.85
📌 Everestims Technologies Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #EIMS 📄🧾


14
3,828
👍ACCORD TRANSFORMER FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 83 was at 38 p/e. Now 23x 👍
GOOD.👍 If the order book and order flow over last 6 months is good and can deliver 150Cr Sales (Management had stated 120 to 150Cr possible in June), then rerating possible.
But upto 120Cr not much scope since EPS wont move much (Already TTM is at Rs.96Cr)
H1 FY27 Vs.H2 FY26
REV:Rs. 53Cr Rs. Vs Rs. 43Cr 👍
PAT:Rs. 4.2Cr Vs Rs. 3.3Cr 👍
(May Compare with H1FY26 Rev=Rs. 28Cr & PAT=Rs.1.25Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.96Cr Vs Rs. 70Cr 👍
PAT: Rs. 7.5Cr Vs Rs. 4.5Cr 👍
SME IPO was in March 2026 at Rs.46
📌 Accord Transformer & Switchgear Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #ACCORDTS 📄🧾


14
3,741
👍WISE TRAVEL FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 103 was at 8.6p/e. Now 5.3x👍
GOOD! Have been able to pass on fuel price increase and actually move margin up, by a percent. Market seem to have forgotten about this company! May be it will notice now, since there has been sustained growth.
H1 FY27 Vs.H2 FY26
REV:Rs. 494Cr Rs. Vs Rs. 449Cr👍
PAT:Rs. 19Cr Vs Rs.17Cr👍
(May Compare with H1FY26 Rev=Rs. 383Cr & PAT=Rs. 14Cr ) GOOD. 👍
TTM Vs FY26
REV:Rs.943Cr Vs Rs. 832Cr 👍
PAT: Rs. 46Cr Vs Rs. 29Cr 👍👍
SME IPO was in Feb 2024 at Rs.147
📌 Wise Travel India Limited informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #WTICAB 📄🧾


1
9
3,805
🍏👍INDIAN EMULSIFIERS FY27 H1 RESULTS. H1FY27 RESULTS. Rs.36 was at 8.5 p/e. Now 6.3x👍
From Rs.132 IPO price to around Rs.450 ATH after listing and then sustained fall to Rs.36 because the capex did not result in any massive swing in revenue & equity dilution.
With 21Cr IPO capex, capacity was to reach 2.5 times in Fy26. BUT FY26 quarters showed limited growth.
BUT this H1 result shows a big bump in revenue. 👍
👉Have to HEAR FROM MANAGEMENT whether this is a one-of case or actual result of expansion. Re-rating is possible IF management confirms the business is shifting gears with expansion.
Company has raised additional capital through Rights for further expansion.
H1 FY27 Vs.H2 FY26
REV:Rs. 138Cr Rs. Vs Rs. 83Cr👍
PAT:Rs. 15Cr Vs Rs. 6Cr👍👍
(May Compare with H1FY26 Rev=Rs. 77Cr & PAT=Rs.10 Cr )
TTM Vs FY26
REV:Rs.221Cr Vs Rs. 160Cr👍
PAT: Rs. 21Cr Vs Rs. 16Cr👍
SME IPO was in MAY 2024 at Rs.132


👍CFF FLUID CONTROL FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 1081 was at 59p/e. Now 49.5x 👍
Good.But can be erratic like earlier due to order lumpiness
H1 FY27 Vs.H2 FY26
REV:Rs. 124Cr Rs. Vs Rs. 105Cr👍
PAT:Rs. 26Cr Vs Rs.19.5 Cr 👍
(May Compare with H1FY26 Rev=Rs. 104Cr & PAT=Rs. 19Cr ) - GOOD 👍
TTM Vs FY26
REV:Rs.229Cr Vs Rs. 209Cr 👍
PAT: Rs.45.5 Cr Vs Rs. 38.5Cr 👍
SME IPO was in JUNE 2023 at Rs.165
35
4,787
🍏👍ZELIO E MOBILITY FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 1127 was at 84p/e. Now 51 x 👍
Looks all set to break all records with potentially >Rs.600Cr sales this year. This company has taken full advantage of 2 wheeler EV boom. Great pick by MA.👍
H1 FY27 Vs.H2 FY26
REV:Rs. 292Cr Rs. Vs Rs. 172Cr 👍
PAT:Rs. 31Cr Vs Rs. 16Cr 👍👍
(May Compare with H1FY26 Rev=Rs. 134Cr & PAT=Rs. 12Cr ) VERY GOOD 👍
TTM Vs FY26
REV:Rs.464Cr Vs Rs. 303Cr 👍
PAT: Rs. 47Cr Vs Rs. 28.4Cr 👍👍
SME IPO was in OCT 2025 at Rs.136


🍏👍CHANDAN HEALTHCARE FY27 H1 RESULTS. H1FY27 RESULTS. Rs.236 was at 21.5p/e. Now 17 x👍
(The numbers are being reorganized. So there could be further change in Audited Results later)
Company has restated its financials after transferring Chandan Pharmaceuticals back to the Dayals
We can see major drop in topline. But the margin has improved substantially because medical shop business was low margin stuff.
How things changed after Dayal Biz was removed:
FY26 was Rs.280Cr with Rs.27Cr PAT.
Now it is Rs.160Cr with Rs.19Cr PAT
H2FY26 was Rs.144Cr with 11.4Cr PAT.
Now it is Rs.79.6Cr with 9.4Cr PAT
H1FY26 was Rs.136Cr with 15.6Cr PAT.
Now it is Rs.80Cr with 9.6Cr PAT
As per latest financial records of Chandan without Dayal
👉Since there is too much variation, may have to wait for year end, to get clean margin profile.
H1 FY27 Vs.H2 FY26
REV:Rs. 109Cr Rs. Vs Rs. 79.6Cr 👍
PAT:Rs. 24.9Cr Vs Rs.9.4Cr 👍👍
(May Compare with H1FY26 Rev=Rs. 80.4Cr & PAT=Rs. 9.6Cr ) VERY GOOD 👍
TTM Vs FY26
REV: Rs.189Cr Vs Rs. 160Cr 👍
PAT: Rs. 34.4Cr Vs Rs. 19Cr 👍
SME IPO was in FEB 2025 at Rs.159
📌 Chandan Healthcare Limited informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #CHANDAN 📄🧾


2
22
4,456
👍LT ELEVATOR FY27 H1 RESULTS. H1FY27 RESULTS. Rs.325 was at 41p/e. Now 33x 👍
This is just okay. Growth with some margin loss. With around 80% growth guidance need about 120Cr in H2. There is ongoing capex.👍 New facility is expected by end of Q4.
H1 FY27 Vs.H2 FY26
REV:Rs. 72Cr Rs. Vs Rs. 64Cr 👍
PAT:Rs. 10.3Cr Vs Rs. 11Cr 🫱
(May Compare with H1FY26 Rev=Rs. 47Cr & PAT=Rs. 6Cr ) GOOD! 👍
TTM Vs FY26
REV:Rs.136Cr Vs Rs. 111Cr 👍
PAT: Rs. 21.3Cr Vs Rs. 17Cr 👍
SME IPO was in SEPT 2028 at Rs.78
📌 L. T. Elevator Ltd informed the exchange about its approval for the financial results for the period ended . #SME #LTELEVATOR 📄🧾


