Joined December 2022
"As long as that agent can assess the whole policy and not just the price, let the best algorithm win.​" Lets ride!
What does it take to put AI to work effectively in insurance? Root Founder & CEO Alex Timm explores the role of technology, data, and engineering in his first @forbesbizcncl article. forbes.com/councils/forbesbu…
1
1
6
402
incredible. $root is live in 37 states and the cheapest of any carrier in 17, while also having best LR's in the industry. lowest rates + lower LR means superior segmentation, which is the entire bull thesis playing out. once you have best pricing, key is distribution [cont]
Replying to @Experian
@Experian analyzed insurance pricing across the country and named Root the cheapest full coverage car insurance in 17 states. experian.com/blogs/ask-exper…
1
14
821
Riley retweeted
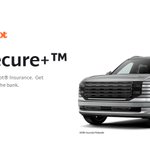
🚨 THIS IS IT - THIS IS JUST THE START OF THE NATIONWIDE ROLL OUT! $ROOT, powering Hyundai's Secure+ Insurance product, is now LIVE at 14 Arizona Hyundai dealerships! 🤯 Every new lease or purchase in AZ comes with 6 months of $ROOT insurance at no cost! This is an incredible way to get people instantly introduced to $ROOT and put them behind the wheel with $ROOT as their insurer from day one. They get 6 months to experience the product, pricing, and telematics firsthand - once that free period ends, $ROOT has already established the relationship and has an opportunity to retain them as a long-term policyholder. 😎 Great find @echoesxzzz! h/t
3
7
1
41
5,854
Insurify just named $root as the best carrier for safe drivers. Their whole thesis revolves around offering best prices to better than average drivers by identifying and omitting the worst ones. Their best in class LR proves they've been able to do this
2
2
1
14
1,203
interesting portion of the roundtable interview that wasn't in the initial cut. Key takeaway for me is the doubling down on OEM partnerships - hard to imagine he'd keep banging this drum if there wasnt meaningful progress happening.
WATCH: Alex Timm, founder of Root Inc, discusses how Waymo and Tesla’s autonomous fleets will impact insurance. In a conversation with Jackson Hinkle @RootInsurance | @jacksonaltonh
1
5
957
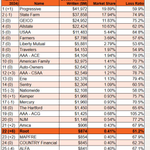
posted by a $root employee today. The table alone says a lot. The biggest jump in Written Premium while delivering the lowest Loss Ratio. The 2026-2027 results will make their advantages even more obvious
3
2
19
4,523
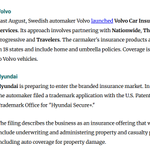
$ROOT may start growing revenue 40% YoY in 2027 and onwards. The market has not priced this in. Here is what is in motion: 1. Hyundai/Kia has been interested in capturing insurance commission sales at point of sale 2. Kia already partners with Wrisk/Allianz in the UK to sell their insurance at point of sale. 3. In the US, Hyundai/Kia through Hyundai Capital America, has selected Root Insurance (beginning in 2025) as their Insurance partner 4. Hyundai has trademarked their own insurance label, "Hyundai Secure+" to sell insurance in the US. 5. The Root website confirms that Hyundai Secure+ is a Root powered product. Their website also shows pages for Kia Secure+ and Genesis Secure+ products, which are brands under Hyundai Capital America. 6. Hyundai has been hiring this summer for job roles that include people to align incentives with dealers to sell an in-house branded insurance product, as well as technical roles for backend digital integration with a product like insurance. These facts establish with strong confidence that Hyundai Secure+ is a Root Point of Sale dealer product. The next step is figuring out what kind of policy sales and revenue growth this would bring to Root. 1. Hyundai Capital America works with 1,800 dealerships, which include 825 Hyundai dealers and 772 Kia dealers. 2. HCA sales in 2025 included, 901,686 Hyundai vehicles, 852,155 Kias, and 82,000 Genesis. For a total of 1.836 Million Vehicles. 3. Wrisk/Allianz which currently does POS car insurance in the UK, have achieved attach rates ranging from 4% to around 11%. 4. Root already partners with Carvana for Point of Sale in the US, and have an attach rate of somewhere around 12.5%. 5. Carvana sold 596,641 cars in 2025. That's about 75,000 in new policies at a 12.5% attach rate to Root. Okay now the math. Dealers will convert at somewhat lower levels than Carvana. We have Wrisk as a baseline at 4-11%. Let's look at 3 possibilities. We will use Hyundai Capital America's 1.8M vehicle sales number: - bear case 5% attach rate = 90,000 new policies a year - base case 7.5% attach rate = 135,000 new policies a year - bull case = 10% attach rate = 180,000 new policies a year With Carvana already at about 1/4 of new policies at est 75,000 per year, Hyundai may increase new policies sold by Root by about 50% per year. And these are all brand new cars. Which means high value comprehensive policies. Not cheap policies for older cars that are liability only. $ROOT could start growing revenue at 40-50% YoY in 2027 with this program active, even without targeting direct growth. Right now is the calm before the storm. Based on the job description postings from HCA, this is nearing the phase where dealer implementation is on the horizon. Screenshot from Root's website below. Unfortunately, as is the case on X, and for human behavior, most people only get interested in a stock after the share price doubles. I think people should get excited now, while there is potential uncertainty and lack of knowledge around specifics of the Hyundai partnership pre-launch. Once all the facts are widely publicized, the alpha is gone, and the share price may capture much of the upside.
5
6
2
39
5,810
oppurtunity he's most excited about for growth is embedded partnerships. also emphasizing point of sale and a much better customer experience. sounds a lot like hyuandai secure+ if you ask me
Root Founder & CEO Alex Timm walks through the technical foundation behind Root, key growth levers, and how real-time model retraining creates a compounding pricing advantage. youtu.be/lJ5v9eIxDJo See end of video for disclosure on forward-looking statements.
5
1,209
Probably nothing... (all Cybercabs)
56
85
6
1,434
46,129
new article about auto carriers policy growth. Despite the current sentiment, when you zoom out you realize $root has grown faster than almost every other carrier YoY, despite the unfavorable environment.
1
1
6
1,036
Partnerships keep stacking up. The comparison partners are especially intriguing if $root's product/pricing are indeed materially better. If they are, the win rate will increase and create a nice flywheel with others wanting to partner to offer $root
2
5
493
Former Senior Executive at Root on why better pricing does not mean lower prices $ROOT
1
7
2,100
recent @_inpractise interview with a former $root exec. Root…use LTV models "and he believes they’re" in the top 2% to 5%" on LTV rigor; contrast: many carriers/agents run "a flat 10% acquisition fee" with limited linkage between marketing and actuarial
1
1
341
president and CFO at Jerry rarely ever posts on linkedin, but recently highlighted the $root partnership.
2
1
7
824
P&C Specialist article highlighting $root vs $lmnd & $hipo titled "Root Breaks Out of the Insurtech Pack". 2 insurtech analysts talk diversified distribution and elite UW, which "position Root to grow faster than both hipo and lmnd". Massive stock price disconnect imo
2
2
1
4
762
🚨🚨🚨 $ROOT Hyundai Alpha 🚨🚨🚨 New job role at Hyundai Capital America Job is responsible for "developing and executing the Region's insurance growth objectives through dealer conversions to the branded F&I (finance and insurance) product. What is their branded insurance product? Hyundai Secure+, powered by Root. Where is it headed? To dealerships for conversions. AKA, a point of sale offering like Carvana.
2
3
2
17
4,460
A wolfe analyst discussed $PGR market saturation saying "They're past their peak growth, there just simply isn't as much opportunity to grow." The larger an insurer gets the harder it is to maintain growth. $root meanwhile has a riches of growth levers yet trades much cheaper
1
1
7
289
new job posting focused on scaling IA's. Current IFP: ~$350M Current US IA availability: ~10% Future IA IFP with 50% availability (a near term goal of theirs): ~1.2B. This includes a 30% haircut for nonlinear growth/efficiency. IFP could nearly double just from scaling IA's
6
178