

Stocks, Crypto, and Macro Investing Investment Analyst | Affiliate BlockPhi
Joined May 2016
- Tweets4.8K
- Following469
- Followers692
- Likes1.8K


Pinned Tweet
I’ve officially joined BlockPhi as an affiliate analyst covering crypto, macro, and equities.
I’ve spent over a decade as an institutional investment analyst. I don’t attach my name to things lightly.
Crypto, macro, and liquidity research is critical to succeed in investing.Without it, you’re investing blind.
BlockPhi provides you institutional grade research at a fraction of the price GMI and Cross Border Capital charge.
Global liquidity, $BTC valuation models, macro frameworks, investment models, all laid out clearly.
You also get access to a community of analysts and live trade updates in one place.
Join us today: blockphi.com/gold?a=rohanj-i…


Holding Bitcoin is easy. Valuing it is not.
We built BlockPhi, a quantitative analytics terminal that tracks Global Liquidity, Bitcoin’s primary driver, and translates it into data-driven investment positioning and valuation models.
Now you see what funds see.
Here's how it works:
blockphi.com
$NVDA at $222 since I posted below.
NVDA’s forecast earnings and its increasing reliability made entering at $210 a no brainer.

$NVDA at $210 is a once in a lifetime gift.
Equity research update.
4 reasons why NVDA reaches $285.
Valuation.
NVDA sits below my model’s fair value right now. Consensus is applying conservative forecasts and discount rates for what this business is building and where the world is going.
A $1T backlog and a strong software moat reduce business risk below standard WACC assumptions.
Higher growth, lower discount rate, that's what pushes my ceiling to $285 while consensus lands near $266.
Guys, this gap doesn't stay open forever.
Moat.
Wide and durable, built on CUDA, it’s a genuine switching cost.
Think long term, this is what lets a company outearn its cost of capital for 20 years or more.
TAM.
This is where my number and consensus diverge big time.
My strong case assumes revenue CAGR of 26-30% through FY27-30, above the 18-22% consensus because AI infrastructure demand is a decade-long buildout that’s just starting
Dividend growth.
Expected growth here sits in the top 1% globally. Real confidence in where the business is heading.
Now the concern.
The stock's revenue multiple runs rich, top 10% globally, and the standard read is that this overstates long-term growth potential.
That read holds if you're still modeling the old TAM.
Model the AI infrastructure buildout as a decade-long cycle instead, and the same multiple looks reasonable, maybe still cheap.
$285 maintained.

2
166
$NVDA up 5% in 2 days since my update below 🟢
Valuation modelling is non-negotiable.
$NVDA at $210 is a once in a lifetime gift.
Equity research update.
4 reasons why NVDA reaches $285.
Valuation.
NVDA sits below my model’s fair value right now. Consensus is applying conservative forecasts and discount rates for what this business is building and where the world is going.
A $1T backlog and a strong software moat reduce business risk below standard WACC assumptions.
Higher growth, lower discount rate, that's what pushes my ceiling to $285 while consensus lands near $266.
Guys, this gap doesn't stay open forever.
Moat.
Wide and durable, built on CUDA, it’s a genuine switching cost.
Think long term, this is what lets a company outearn its cost of capital for 20 years or more.
TAM.
This is where my number and consensus diverge big time.
My strong case assumes revenue CAGR of 26-30% through FY27-30, above the 18-22% consensus because AI infrastructure demand is a decade-long buildout that’s just starting
Dividend growth.
Expected growth here sits in the top 1% globally. Real confidence in where the business is heading.
Now the concern.
The stock's revenue multiple runs rich, top 10% globally, and the standard read is that this overstates long-term growth potential.
That read holds if you're still modeling the old TAM.
Model the AI infrastructure buildout as a decade-long cycle instead, and the same multiple looks reasonable, maybe still cheap.
$285 maintained.
2
4
163
$210 $NVDA 🟢
Massively undervalued.
4 reasons why we reach $285, below.
$NVDA at $210 is a once in a lifetime gift.
Equity research update.
4 reasons why NVDA reaches $285.
Valuation.
NVDA sits below my model’s fair value right now. Consensus is applying conservative forecasts and discount rates for what this business is building and where the world is going.
A $1T backlog and a strong software moat reduce business risk below standard WACC assumptions.
Higher growth, lower discount rate, that's what pushes my ceiling to $285 while consensus lands near $266.
Guys, this gap doesn't stay open forever.
Moat.
Wide and durable, built on CUDA, it’s a genuine switching cost.
Think long term, this is what lets a company outearn its cost of capital for 20 years or more.
TAM.
This is where my number and consensus diverge big time.
My strong case assumes revenue CAGR of 26-30% through FY27-30, above the 18-22% consensus because AI infrastructure demand is a decade-long buildout that’s just starting
Dividend growth.
Expected growth here sits in the top 1% globally. Real confidence in where the business is heading.
Now the concern.
The stock's revenue multiple runs rich, top 10% globally, and the standard read is that this overstates long-term growth potential.
That read holds if you're still modeling the old TAM.
Model the AI infrastructure buildout as a decade-long cycle instead, and the same multiple looks reasonable, maybe still cheap.
$285 maintained.
1
3
193
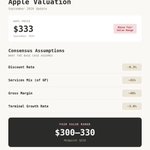
$AAPL is overvalued at $333 🔴
For tech stocks, your attention needs to be elsewhere.
$AAPL at $333 is now overvalued 🔴
Here's why.
September equity research update.
Valuation.
My fair value range sits at $300-330, midpoint $315.
Consensus lands close to my model too.
The real disagreement about Apple's future sits in two places:
How much of gross profit services makes up, and what discount rate you apply to a services-heavy mix.
Margins and terminal growth barely move regardless of who's modelling it.
Price has run to $333, now above the top of my range.
Growth.
Forecast growth here is predictable. Apple won’t be seeing surprises dramatically in either direction at this stage of the cycle.
Macro.
The broader backdrop isn't supportive for Apple's sector right now. That caps how much benefit of the doubt the stock deserves above the midpoint.
Services.
This is the real growth engine, and it's a steady one.
Without a specific catalyst, services grows in line with expectations.
The catalyst question.
The iPhone duo and iPhone 18 range could change this.
If hardware sales run hot and pull services revenue up with them, above what's already priced in, that justifies paying above my range.
I don't see it.
Growth here is predictable enough that I'm not pricing in a surprise from either product cycle.
$315 fair value.
$333 is slightly overvalued.
There’s better names out there.
Wouldn't be surprised to see a pull back toward the range unless the hardware cycle proves me wrong.

1
2
151
$NVDA at $210 🟢
Opportunity of a lifetime.
Bull case below.
$NVDA at $210 is a once in a lifetime gift.
Equity research update.
4 reasons why NVDA reaches $285.
Valuation.
NVDA sits below my model’s fair value right now. Consensus is applying conservative forecasts and discount rates for what this business is building and where the world is going.
A $1T backlog and a strong software moat reduce business risk below standard WACC assumptions.
Higher growth, lower discount rate, that's what pushes my ceiling to $285 while consensus lands near $266.
Guys, this gap doesn't stay open forever.
Moat.
Wide and durable, built on CUDA, it’s a genuine switching cost.
Think long term, this is what lets a company outearn its cost of capital for 20 years or more.
TAM.
This is where my number and consensus diverge big time.
My strong case assumes revenue CAGR of 26-30% through FY27-30, above the 18-22% consensus because AI infrastructure demand is a decade-long buildout that’s just starting
Dividend growth.
Expected growth here sits in the top 1% globally. Real confidence in where the business is heading.
Now the concern.
The stock's revenue multiple runs rich, top 10% globally, and the standard read is that this overstates long-term growth potential.
That read holds if you're still modeling the old TAM.
Model the AI infrastructure buildout as a decade-long cycle instead, and the same multiple looks reasonable, maybe still cheap.
$285 maintained.
1
151
$AAPL at $333 is now overvalued 🔴
Here's why.
September equity research update.
Valuation.
My fair value range sits at $300-330, midpoint $315.
Consensus lands close to my model too.
The real disagreement about Apple's future sits in two places:
How much of gross profit services makes up, and what discount rate you apply to a services-heavy mix.
Margins and terminal growth barely move regardless of who's modelling it.
Price has run to $333, now above the top of my range.
Growth.
Forecast growth here is predictable. Apple won’t be seeing surprises dramatically in either direction at this stage of the cycle.
Macro.
The broader backdrop isn't supportive for Apple's sector right now. That caps how much benefit of the doubt the stock deserves above the midpoint.
Services.
This is the real growth engine, and it's a steady one.
Without a specific catalyst, services grows in line with expectations.
The catalyst question.
The iPhone duo and iPhone 18 range could change this.
If hardware sales run hot and pull services revenue up with them, above what's already priced in, that justifies paying above my range.
I don't see it.
Growth here is predictable enough that I'm not pricing in a surprise from either product cycle.
$315 fair value.
$333 is slightly overvalued.
There’s better names out there.
Wouldn't be surprised to see a pull back toward the range unless the hardware cycle proves me wrong.
$BTC is waiting to rally hard 🟠
Capital has been waiting on the sidelines.
Read my Bitcoin Trend Follower to know when to buy in.

BREAKING: Crypto ETFs attracted +$1.3 billion in inflows last week, following +$3.3 billion in the week prior.
This also marks their 6th consecutive weekly inflow.
Over this period, these funds have posted +$6.8 billion in inflows.
The largest Bitcoin ETF, $IBIT, alone attracted +$3.4 billion during this time.
As a result, the 4-week average of crypto ETF inflows rose to +$1.5 billion, the highest since November 2025.
Demand for crypto is rapidly improving.
1
141
$NVDA at $210 is a once in a lifetime gift.
Equity research update.
4 reasons why NVDA reaches $285.
Valuation.
NVDA sits below my model’s fair value right now. Consensus is applying conservative forecasts and discount rates for what this business is building and where the world is going.
A $1T backlog and a strong software moat reduce business risk below standard WACC assumptions.
Higher growth, lower discount rate, that's what pushes my ceiling to $285 while consensus lands near $266.
Guys, this gap doesn't stay open forever.
Moat.
Wide and durable, built on CUDA, it’s a genuine switching cost.
Think long term, this is what lets a company outearn its cost of capital for 20 years or more.
TAM.
This is where my number and consensus diverge big time.
My strong case assumes revenue CAGR of 26-30% through FY27-30, above the 18-22% consensus because AI infrastructure demand is a decade-long buildout that’s just starting
Dividend growth.
Expected growth here sits in the top 1% globally. Real confidence in where the business is heading.
Now the concern.
The stock's revenue multiple runs rich, top 10% globally, and the standard read is that this overstates long-term growth potential.
That read holds if you're still modeling the old TAM.
Model the AI infrastructure buildout as a decade-long cycle instead, and the same multiple looks reasonable, maybe still cheap.
$285 maintained.
Best way to make money in $BTC 🟠
Understand if trend following is active.
Ep 2 of the Bitcoin Trend Follower live.

Is $BTC finally trending?
It is, and it's violent.
The Bitcoin Trend Follower.
Episode 2 is live ↓
Every week I do a Technical Analysis deep dive on Bitcoin and share the findings with great indicators.
146
$AAPL Share Price Target update 🟢
The foldable, iPhone Duo is announced.
And it looks sensational. Genuine excitement for tech fans.
However, earnings expectations won’t be beaten by this alone.
Apple remains fairly valued.
Will $AAPL share price rocket with the new foldable?
Short answer: no. We’re still at fair value.
The foldable iPhone is coming, and it's a genuine new hardware feature.
The iPhone has plateaued on features otherwise.
A foldable extends the smartphone strategy and reaches a new buyer, maybe even the Android user who wants some style.
So it’s real earnings for hardware.
However, none of it moves the share price the way people expect.
Only a beat against expectations does. And a small boost is already baked in.
Plus Hardware isn't the major driver of Apple's earnings anymore, services are.
I also ran this through my model, in case the foldable was the discrepancy I've found elsewhere.
I looked for the same TAM gap that shows up in $NVDA and $MSFT.
I don’t see it.
Fair value holds.

1
1
229
Everything you need to know about $BTC charts.
The Bitcoin Trend Follower, ep 2, Sep 2026.
Get on it.
Is $BTC finally trending?
It is, and it's violent.
The Bitcoin Trend Follower.
Episode 2 is live ↓
Every week I do a Technical Analysis deep dive on Bitcoin and share the findings with great indicators.
1
128
Will $AAPL share price rocket with the new foldable?
Short answer: no. We’re still at fair value.
The foldable iPhone is coming, and it's a genuine new hardware feature.
The iPhone has plateaued on features otherwise.
A foldable extends the smartphone strategy and reaches a new buyer, maybe even the Android user who wants some style.
So it’s real earnings for hardware.
However, none of it moves the share price the way people expect.
Only a beat against expectations does. And a small boost is already baked in.
Plus Hardware isn't the major driver of Apple's earnings anymore, services are.
I also ran this through my model, in case the foldable was the discrepancy I've found elsewhere.
I looked for the same TAM gap that shows up in $NVDA and $MSFT.
I don’t see it.
Fair value holds.
Is it too late to buy $AAPL or is it still undervalued?
Wall Street’s out of touch Ivy League analysts can’t explain how you reach your own conclusion.
Full Apple Equity Research note July 2026.
Valuation and discount rate:
Bear case - $190.
Discount rate of 9-10.5%.
Treats Apple like a hardware company exposed to real cost shocks and a shrinking market.
Bull case - $420.
Services re-rated, plus AI optionality across 2.5B active devices.
Morgan Stanley put Apple at $400-440.
Base case. Consensus sits at $318.
Same cash flows.
Three completely different views.
Forecast financials:
FY27 EPS consensus sits near $9.30. EBITDA around $160B.
Gross margin guide just dropped from a record 49.3% to under 48.5%.
What’s the catch?
That EPS growth assumes a real AI-driven upgrade cycle.
Siri AI doesn’t ship in the EU or China.
So roughly a third of the growth story is under pressure.
Strategy:
The iPhone has plateaued on features. Foldables, hyper stylistic designs, spec wars is Android world.
Apple’s actual bet is to deepen services and AI as a reason to stay in the ecosystem.
Services are 26% of revenue.
It’s 41% of gross profit, at 75.6% margin.
That’s the strategy and what justifies paying a premium multiple for a phone that isn’t changing much.
Macro:
Middle East conflict is keeping risk sentiment suppressed, pressuring every tech stock.
Layer on record memory chip prices and a 13.9% global smartphone shipment decline, the steepest on record, macro data is far from supportive.
Cost of living and consumer psychology:
This is where the real decision happens, and it’s complex.
Pro Max, or Pro, or base, or just get a cheaper Android.
That’s the actual internal chit chat now. Not “do I want the new iPhone.”
Two schools of thought are colliding.
One says save, trade down, delay, that’s the 33% buying base over Pro, the UK holding phones past three years.
The other says the opposite: everything is already expensive, the phone won’t get meaningfully cheaper by waiting, so why not just buy it now.
Where do I sit in value?
Hard to argue against consensus in stressful macro times.
Fairly valued.

Bitcoin ripped.
Now you’re wondering if you missed it.
Is $BTC still trending and going higher?
Ep 2 of The Bitcoin Trend Follower 🟠

Is $BTC finally trending?
It is, and it's violent.
The Bitcoin Trend Follower.
Episode 2 is live ↓
Every week I do a Technical Analysis deep dive on Bitcoin and share the findings with great indicators.
1
1
163

The most proven way to make money in Bitcoin is to invest when it’s trending.
Is $BTC trending and should we go in?
Episode 2 is live below.
Is $BTC finally trending?
It is, and it's violent.
The Bitcoin Trend Follower.
Episode 2 is live ↓
Every week I do a Technical Analysis deep dive on Bitcoin and share the findings with great indicators.
2
142
Is $BTC finally trending?
It is, and it's violent.
The Bitcoin Trend Follower.
Episode 2 is live ↓
Every week I do a Technical Analysis deep dive on Bitcoin and share the findings with great indicators.
Everyone wants to find the next $NVDA
Guys, sorry to tell you.
Nvidia is the next $NVDA 🟢
Undervalued.
I value $NVDA at $175 to $285, strongly leaning toward the higher end.
I've valued tech stocks for a decade.
Wall Street hasn't figured out how to value this yet.
Here's why they're wrong and how to value NVIDIA.
Every analyst uses DCF models, yet Wall Street's price targets range from $215 to $500.
That's because DCF breaks on Nvidia.
What's the TAM? Discount rate? Terminal value?
No on knows.
Yet they give you an exact $395 valuation.
So what should you do?
Use a realistic floor and ceiling approach.
Floor: Margins compress, capex rises, WACC 13-14%, terminal growth 2.5-3%.
Result: $175-200.
Ceiling: CUDA holds, backlog delivers, software scales, WACC 10-11%, terminal growth 3.5-4%.
Result: $245-285.
Margin of Safety maintained
I lean bullish because the backlog and moat justify the higher assumptions.
NFA

3
197
Load up on growth
$NVDA $AAPL $MSFT $BTC $ETH
In all seriousness, this is long due.
Macro outlook has been stressed from this war. This should send risk assets higher.
BREAKING: President Trump is having private discussions with senior aides about potentially declaring the Iran War over, per WSJ.
Aides are reportedly advising President Trump that an escalation of the war beyond recent strikes could cost Republicans the midterm elections.
2
2
234
$AVGO beats earnings 🟢
How you do you profit in the tech stocks boom?
Here’s the secret.
Tech sector ETFs.
Which one?
VGT holds all the big names.
$NVDA, $MSFT, $AAPL, more.
Getting broad exposure means you win.
Track the ETF, learn which stocks outperformed and why.
This is how you become knowledgeable to pick your own stocks.

1
306
How to profit with AI boom in tech stocks:
$AVGO edition 🟢
Valuation with a range.
Wall Street’s Share Price targets are wrong.
> Underestimated total market
> Underestimated terminal value
> Wrong discount rate
> Wrong Share Price targets
This is a new world that’s changing constantly.
So what do you do?
Build a floor and a ceiling value, and price the uncertainty between them.
Floor: competition bites, margins compress, discount rate moves higher to reflect the added risk.
Ceiling: the moat holds, the backlog delivers, margins expand as software scales, discount rate moves lower to reflect the reduced risk.
The range is the answer.
Where you lean is the judgement call and where macro analysis and short term analysis fits in.
I’ve outlined my in depth thesis in my NVDA posts.

1
1
435