

Everything AI and Data Center
Joined September 2009
- Tweets7.2K
- Following1.2K
- Followers19.8K
- Likes15.5K




Pinned Tweet
Leopold Aschenbrenner thinks interest rates could go above 10% before the end of the decade.
He's not calling it the base case. He says there's "at least a serious chance."
His reasoning: if AI drives explosive growth, companies borrow like crazy to build clusters and then robot factories. And people expecting much higher future growth are less willing to save today. Both push rates up.
"I don't think anyone is expecting interest rates to go above 10%, real interest rates. There's at least a serious chance of that before the decade is out."
Everything that happened in the data center world today (Oct 30, 2026)
Amazon spent $77B in one quarter and Intel lost almost a quarter of its value overnight. Asia didn't wait for New York: KOSPI -3.5%, SK hynix -7%.
HYPERSCALERS
- Amazon Q3: AWS +39% to $46.0B, its fastest in nearly five years. Capex $77.3B vs ~$58.7B expected. 2026 guide held at ~$220B, and Jassy says it spends "meaningfully more" in 2027 (Amazon, CNBC)
- Amazon's trailing free cash flow fell to -$42.4B from -$7.6B a quarter ago. EPS and revenue missed, Q4 sales guide midpoint below the Street. Stock -6% premarket (Amazon, CNBC)
- Jassy sees AWS growing over 40% in both 2027 and 2028. Its chips business is growing triple digits, and Trainium will be sold outside AWS late in 2027 (Amazon, CNBC)
CHIPS
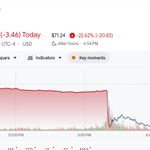
- Intel Q3: revenue $16.5B, +21%. Data center and AI +78% to $7.3B. But Q4 guide is $15-16B vs $17.1B expected, EPS 25c vs 43c. Stock -23% premarket (Intel, CNBC)
- Intel says server demand far exceeds supply, short on wafers and EMIB substrates into 1H 2027. An accident shut its Israel Fab 28 for ~2 weeks, a ~$300M Q4 hit. PC units seen -12% this year, -10% in 2027 on memory costs. No positive free cash flow in 2027 as capex rises (Intel call)
- Follow-up: Lumentum fell 7.5% premarket as the Marvell talks stay unconfirmed. Morningstar puts deal odds below 50%. Marvell closed -13.2% Thursday (Investing, market data)
MEMORY
- Sandisk: revenue $11.0B, +23% q/q. Data center $4.8B, +61% q/q, at an 85% gross margin. Next quarter guided to $12.2-12.6B, plus an 8-for-1 split. Stock still -3% after hours (Sandisk, CNBC)
PARTS + PACKAGING
- Murata raised its full-year operating profit forecast to 520B yen from 430B on data center demand. Computer-related sales +61% in H1. It will put ~1T yen into MLCC capacity through FY2030. Stock still -9.5% (Murata)
- Samsung Electro-Mechanics signed an 879.3B won AI server MLCC deal running Dec 2026-Dec 2027, its 8th long-term deal this year. It expects over half of 2027 MLCC sales on long-term contracts (Digital Today)
- Ibiden sees AI GPU and ASIC substrate demand growing 5.4x by 2030 and added ~151B yen of new capex. Stock still went limit-down, -15%, on Intel (Economic Daily News)
- Delta Electronics: record Q3 sales, AI is now ~half of revenue, but gross margin fell to 34.1% on inventory write-downs as customers shifted orders. It cites shortages of parts, power and labor delaying builds. Limit-down (Newtalk, CNA)
POWER
- AEP raised its five-year capex plan 30% to $100B: $20B for gas plants, $37B for transmission. Contracted large load +22% to 84GW, led by SB Energy's 10.4GW Ohio campus (Utility Dive)
MARKETS
- Thursday: Nasdaq -1.37%, chip index -1.42%. Alphabet -12.6%, Micron -5%, Amazon -4.3% before its report (Reuters, market data)
- KOSPI -3.48% to 5,730, a sell sidecar hit, foreigners sold ~1.8T won. SK hynix -7.1%, Samsung -3.0%, Samsung Electro-Mechanics -7.5% (Chosun Biz, Yonhap)
- Nikkei -2.12%, Tokyo Electron -5%, Advantest ~-6%. BOJ held at 1.25% but will sell more ETFs from January. Taiwan -2.49%, TSMC -1.86%, PCB names down up to ~8% (Maeil Business, CNA)
What it all means: The supply chain keeps printing records and keeps getting sold. Murata, Sandisk, Ibiden and Delta all showed AI demand running hot, and all fell. Amazon held capex and still dropped because the cash went deeply negative. Intel is the cleaner warning: servers are sold out, but PCs are being crushed by memory prices, so the AI build is starting to eat the rest of tech. My read: until a hyperscaler shows capex turning into free cash flow, every beat gets sold.
$AMZN $INTC $GOOGL $MU $SNDK $SKHY $SSNLF $TSM $MRVL $LITE $AEP
Follow @SingularityRes for the full data center roundup every morning.


Why $INTC is down ~20% after hours:
1. PC slowdown. Rising memory prices are crushing PC demand. Client revenue is guided down 20%+ next quarter, and Intel expects the slowdown to last at least through the first half of next year. The CFO: "we are not optimistic about next year."
2. The Israel fab explosion. A ~$300M revenue hit this quarter and another next quarter.
What's still working:
- Data center & AI revenue +78%, best growth in 15 years. Demand is bigger than supply.
- 18A yields improving at a double-digit rate.
- 14A on track for 2027 risk production.
This quarter was fine. PCs stay weak for at least the next two.


$TMDX flight tracker gang: NEED HELP URGENTLY
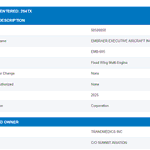
We have a tail number N254TX that is assigned if we search through N-number but if we search through the Name, we cant find anything. Can anyone help me on this?


$TMDX FLIGHT TRACKER UPDATE
Proprietary data is the most valuable asset in the world of AI and I was using a complicated bot to scrape the flight data from another website.
On Oct 28 (yesterday), the other website stopped automated scrapping of data ( save their proprietary data) and hence it was showing zero flights in the last 24 hours.
We are working on a fix.
Everything that happened in the data center world today (Oct 29, 2026)
Alphabet just burned $9B of free cash in a quarter and is down 11% premarket. Microsoft spent less than it planned and is up. Same AI boom, two very different reactions.
HYPERSCALERS
- Alphabet Q3: Cloud +103% to $30.7B. Capex $51.4B vs ~$55.1B expected. Free cash flow -$9.1B. 2026 capex guide held at $195-205B, 2027 to rise "significantly." Stock -11% premarket (Alphabet, CNBC)
- Alphabet's long-term debt is now $125.1B vs $21.6B a year ago. Purchase commitments hit $924B. It started renting third-party compute late in Q3 and says that will hurt cloud margins near term (Alphabet, CNBC)
- Microsoft: Azure +48% to $33.2B, Q2 Azure guide 49-50%. Capex $45.2B, under its own $50B+ guide because third-party capacity arrived late. Q2 capex seen over $50B, calendar 2026 ~$170B. Stock +2% premarket (Microsoft, Reuters)
- Oracle at investor day: FY2030 revenue $225B+, capex peaks this year and next, outside funding capped at $20B more through FY2030, FCF positive in 2H FY2028. Stock +10.7%. CoreWeave, Nebius, IREN up 2-5% (Reuters)
MEMORY
- Samsung Q3: operating profit 107.4T won, the first company over 100T in a quarter. Chips made 106.5T, a hair under the ~107.3T estimate. HBM4 revenue more than tripled q/q. DRAM average prices up ~20% q/q (Samsung, Yonhap)
- Samsung says 2027 HBM is sold out and the shortage lasts through 2028, a shorter call than SK hynix. Long-term deals with 10 customers, 10 more in talks. Chip capex 76.8T won this year, up 62%, rising sharply in 2027 (Reuters)
- Samsung pushed its new shareholder return plan to January. Shares -4.1% to 232,000 won while SK hynix rose 2.6% (Yonhap)
- Samsung foundry says it won 2nm orders from hyperscalers and starts mass production at Taylor, Texas next year (Reuters)
CHIPS AND OPTICS
- Marvell is reportedly in advanced talks to buy Lumentum, worth ~$83B, with a deal possible as soon as next week. Lumentum +5%, Marvell -11% premarket (Bloomberg via Reuters, CNBC)
- KLA: revenue $4.14B, above guide. December quarter guided to $4.7B. It says AI, memory and packaging all keep driving demand (KLA)
- Advantest raised its full-year operating profit forecast 14% to 967B yen on AI chip test demand. Stock +6% (Advantest, Kyodo)
POWER
- DOE offered Constellation $5B in loans to add 1.1GW at eight nuclear plants. Most of the added power at seven of them is already sold to Google, Amazon or Meta. Not final yet (TechCrunch, Constellation)
MARKETS
- Wednesday: Fed held at 3.75-4%, two dissents wanted a hike. Nasdaq +0.27%, chip index +1.8%, Micron +5.9% (Reuters)
- KOSPI -1.24% to 5,937. Nikkei +1.10% on Advantest. Taiwan -1.42%, TSMC -0.4%, UMC limit-down. Amazon and Intel report tonight (Yonhap, Kyodo, CNA)
What it all means: The market is grading capex on cash flow now, not growth. Google posted 103% cloud growth and still got hit because the cash went negative and debt is up almost 6x. Microsoft spent less and got paid. Oracle got a 10% pop for promising to stop raising money. Memory is still the strongest data point, but Samsung shows the bar is now "beat SK hynix," not "beat estimates." Marvell-Lumentum tells you optics is where the next fight is. Amazon tonight decides the tone.
$GOOGL $MSFT $ORCL $SSNLF $SKHY $MU $MRVL $LITE $KLAC $CEG $CRWV $NBIS $TSM
Follow @SingularityRes for the full data center roundup every morning.
Leopold Aschenbrenner's prediction is coming true.
June 2024: "At some point Google will get $100 billion of revenue from AI. Probably their stock will explode. They're going to become a $5 trillion, $10 trillion company."
Today: Google Cloud +103% to $30.7B a quarter (~$123B run rate), a $561B backlog, and $GOOG at ~$4T.


Is bubbleboi in jail???
His gf had tweeted that he is in jail (after his domestic abuse) and later removed.
I had seen that tweet by my own eyes.


Everything that happened in the data center world today (Oct 28, 2026)
SK hynix just printed an 80% operating margin and says its memory is effectively sold out through 2029. Korea ripped 6.6%.
MEMORY
- SK hynix Q3: revenue 104.6T won, its first quarter over 100T. Operating profit 83.3T won, up 632%, vs ~76.7T expected. Operating margin 80% (SK hynix, Reuters)
- DRAM prices rose by a high-20s % q/q. Server DDR5 shipments +40%+. HBM4 should pass HBM3E in shipments and revenue in Q4 as M15X hits full capacity by year-end. HBM customers want 2x+ what it can supply (SK hynix call)
- Long-term deals with 14 customers cover 50%+ of 2027-28 capacity, with deposits. It says DRAM and HBM through 2029 are "effectively sold out" and 2027 capex will rise significantly (SK hynix call)
- Follow-up: ~100T won of 2026 shareholder returns: 30T+ in dividends, 60T+ in buybacks incl. the 40T done. Q3 dividend 14T won incl. a Kioxia special. Solidigm IPO review formally dropped (SK hynix, CNBC)
- Seagate revenue +61% to $4.2B, data center +63% to $3.4B, next quarter guided to $4.8B. Shares still fell ~6% after hours (Seagate, CNBC)
EARNINGS
- Vertiv: sales +61% to $4.31B vs $3.75B expected, organic orders up 100%+. 2026 sales guide raised by $650M. Stock +16% premarket (Vertiv, CNBC)
- GE Vernova: orders $29B, +96% organic. 112 gas turbine orders, 16.6GW. Backlog $197B, seen above $200B in Q4. About 20% of its gas customers are data centers (GE Vernova)
- GE Vernova will buy grid parts maker Trench for $9B, closing late 2027 (GE Vernova)
- Amphenol: sales +65% to a record $10.2B, orders $12.2B, citing "exceptional" IT datacom growth. Stock +7.5% premarket (Amphenol, Newsquawk)
CHIPS AND CLOUD
- OpenAI reportedly plans to buy Google's TPUs, not just rent them. No terms disclosed, OpenAI declined comment (The Information via Reuters)
- Oracle will offer Google TPUs on OCI from 2027, the first cloud outside Google to do so. Oracle calls it multi-gigawatt (Oracle, DCD)
- Oracle and Nvidia made Vera Rubin NVL72 and Vera CPUs generally available on OCI and plan multi-gigawatt superclusters (Data Centre Magazine)
- General Compute raised a $100M Series A for an inference cloud on Cerebras, SambaNova and Positron chips, partly in old bitcoin mines. 75MW planned in 2027 (TechCrunch)
POWER AND POLITICS
- Baker Hughes booked ~1.1GW of gas turbines and generators for an unnamed US tech company's AI site, plus Chart dry coolers (Baker Hughes)
- Follow-up: Hermantown canceled Tuesday's Google vote over early voting. It's now set for Friday, Oct 30 (Duluth News Tribune, Northern News Now)
MARKETS
- Tuesday: Nasdaq +1.18%, chip index +3.6%, AMD +5.5%, Broadcom +4% (AP, market data)
- KOSPI +6.63% to 6,012, SK hynix +10.9%, Samsung +9.0%. Taiwan +2.04%, Gold Circuit limit-up. Nikkei +1.08%. Fed, Alphabet and Microsoft are later today (Yonhap, Focus Taiwan, Nikkei)
What it all means: The memory bull case got its answer. An 80% margin, half of 2027-28 locked in with deposits, and KOSPI over 6,000. But I'd watch the other side: if OpenAI really buys TPUs and Oracle rents them out, Google starts to look like a real chip seller, which could be a slow leak for Nvidia. Power stays the cleanest trade to me. GE Vernova and Vertiv both show orders running well ahead of shipments, and Baker Hughes just booked another 1.1GW. Tonight Alphabet and Microsoft could swing all of it.
$SKHY $SSNLF $MU $STX $VRT $GEV $APH $BKR $GOOGL $ORCL $NVDA $MSFT $TSM
Follow @SingularityRes for the full data center roundup every morning.
Everything that happened in the data center world today (Oct 27, 2026)
Wall Street lined up $63B to lease Broadcom chips to Anthropic, Nvidia is buying into Meta, and Asia bought the memory dip hard.
FUNDING
- BofA, Citi, Morgan Stanley and Blackstone will fund $63B through a new SPV that buys Broadcom XPUs and networking gear and leases them to Anthropic. Deliveries start in 2027. Broadcom gives residual value support equal to the first lien, reportedly ~$43.5B (Broadcom, Reuters)
- Some banks reportedly weighed walking away. Hock Tan held weekend talks and agreed to higher rates to keep it alive (WSJ)
- Follow-up: Meta upsized and priced its stock sale: $25B of common at $625 plus $12.5B of 6.5% convertible preferred. Nvidia will put in $3B, and Meta plans to expand Vera Rubin and Vera CPU use (Meta, Nvidia)
- Naver signed a deal for Brookfield to put up to $9B into an SPV for GPUs and data centers. Naver rents the compute and pays fees tied to revenue (Naver filing, Korea Herald)
- AirTrunk got an A$4.25B green loan from 32 lenders for its SYD3 campus in Western Sydney, done by mid-2028 (AirTrunk)
MEMORY
- Alibaba, Tencent and ByteDance reportedly want long-term server DRAM and LPDDR deals with Samsung and SK hynix, some for 10 years to 2035. 70-80% of next year's output is estimated already locked by US Big Tech (Maeil Business)
- Follow-up: Micron's Taoyuan union talks ended with no deal. The next round is Nov 6 (Domino Theory, Liberty Times)
- Amazon's devices unit now sees a $612M gross loss this year vs a $438M target as memory costs bite, per an internal document (Business Insider)
CHIPS AND SUPPLY CHAIN
- TSMC is reportedly weighing CoWoS price hikes of up to 20%. Tool lead times have stretched to 6-8 months from 3-6 (Commercial Times via TrendForce)
- Applied Materials will raise its Besi stake to about 20%, citing hybrid bonding. Needs US antitrust clearance (Applied Materials)
- Celestica's first 2027 guide: $40B revenue, up 90%. It says 2028 customer forecasts are "meaningfully higher." Stock up ~15% premarket (Celestica, CNBC)
- Amkor's revenue of $1.99B missed estimates and it trimmed 2026 capex to ~$2.5B from $2.5-3B. Stock still up 3.5%+ premarket (CNBC)
- Corning's optical sales rose 44% to $2.38B. Gen AI product sales more than doubled (Corning)
- Johnson Controls orders rose 44%, backlog up 43% to $23B. Americas orders +58% on "sustained demand for data centers" (Johnson Controls)
POWER AND POLITICS
- Spain softened its data center rules: 60% renewable matching in peak hours until 2029, rising to 80% by 2032, vs 80% all day at once in the first draft (Bloomberg)
- Hermantown, Minnesota postponed final votes on Google's ~500MW data center after two hours of protests (MPR News)
MARKETS
- Monday: Nasdaq +0.8%, chip ETF SOXX nearly +3% on the Anthropic filing. Micron +3%, Nvidia +2.4% (CNBC)
- Tuesday: KOSPI +3.09%, SK hynix +5.18%, Samsung +4.23%, foreigners back to buying. Korea Q3 GDP +1.0% q/q vs the BOK's 0.3% forecast. Nikkei +1.7%, Advantest +9%. Taiwan reopened +0.1%, Nanya +6.5% (Yonhap, BOK, Kabutowire, Focus Taiwan)
What it all means: In about two days, roughly $140B of fresh money for AI compute between Broadcom/Anthropic, Meta and SpaceX. But the WSJ detail matters: some banks reportedly weighed walking, and the chipmaker had to pay up and stand behind the loan. To me that's the real trade now, suppliers using their balance sheets to keep demand funded. Memory looks tight, with Chinese clouds chasing 10-year deals and Amazon's gadgets losing money on chip costs. SK hynix reports tomorrow. If it confirms pricing, I think the Korea rebound has legs.
$AVGO $NVDA $MU $SKHY $SSNLF $TSM $AMAT $BESIY $CLS $GLW $AMKR $JCI $AMZN $SPCX
Follow @SingularityRes for the full data center roundup every morning.
Kid's surname would be "Taylor's Edition"

Taylor and Travis are going to be the best parents ever ❤️


Readers added context they thought people might want to know
Taylor Swift and Travis Kelce have no children and are not expecting; the images are AI-generated fakes similar to prior debunked hoaxes, and reports say they are delaying family plans post-July marriage.
tribune.com.pk/story/2636882/…
ibtimes.co.uk/ai-generated-t…
snopes.com/fact-check/tay…
Wall Street is not ready for next few years when these companies will borrow like crazy
And by 2029, the US government will start supporting them

Breaking: Meta plans to raise up to $95 billion in waves of stock offerings to fund its massive investments in AI infrastructure on.wsj.com/4zc7kwY


Everything that happened in the data center world today (Oct 26, 2026)
The money week starts now. Anthropic filed to go public, Meta is selling $35B of stock, and SpaceX lined up $40B to lease GPUs.
FUNDING
- Follow-up: Anthropic's S-1 is public, Nasdaq ticker ANT. H1 revenue $16.29B vs $1.16B a year ago. H1 net loss $80.7B, mostly accounting charges. $9B on AI infrastructure in H1 vs $7.3B in all of 2025. Marketing could start the week of Nov 9 (Anthropic, CNBC, Yahoo Finance, Bloomberg)
- Follow-up: Meta launched ~$35B of stock sales for AI: $22.5B of Class A plus $12.5B of mandatory convertible preferred, and plans a ~$60B at-the-market program once Class C shares trade. Nvidia, AMD and Broadcom indicated interest in up to $5B, non-binding (Meta)
- SpaceX signed a binding commitment with an Apollo-managed entity for a ~$40B GPU finance lease, ~5-year terms, starting H1 2027 on delivery. Still has closing conditions. Musk says 200+ neoclouds face failures and consolidation as debt tightens (SpaceX filing, CNBC)
- AI tenants now ask for $5M+ a day in late-delivery penalties, up from ~$1M this spring. Marsh built a new "delay-in-delivery" insurance policy for a gigawatt project (The Information)
MEMORY
- SK hynix says nothing is final on a reported 16T won (~$12B) special dividend from Kioxia gains, about 80% of ~20T won. New shareholder returns come with Wednesday's results (Dong-A Ilbo, SK hynix filing)
- Nvidia's Vera Rubin page now lists 19.2 TB/s of HBM4 bandwidth per GPU vs 22 TB/s before, and 3 TB/s of NVLink vs 3.6. Implies ~9.3-9.6 Gbps per pin vs the 11.7 asked of suppliers. No reason given (Nvidia, Wccftech)
- Follow-up: Samsung and SK hynix reportedly target Q2 2027 to ship 8-high HBM4 to Nvidia, as Rubin Ultra may mix 8-high stacks because 12-high has heat and yield problems. 8-high still needs its own qualification (ZDNet Korea)
- BofA's Vivek Arya: memory stays tight in 2027 and 2028. Micron's customer deals now run 3-5 years, about 35% of sales, seen ~50% by 2030. Buy, $1,550 target. (TipRanks)
POWER
- EQT is buying Range Resources in an all-stock deal, >$50B enterprise value, >9 Bcfe/d of gas. Pitched at LNG, power and AI data center demand. Close Q1 2027 (EQT)
- Follow-up: Trump told a Georgia rally to ask data center builders for "$10,000, $15,000, $20,000 for everybody that lives in the community." He also backs local approval power (Atlanta News First)
BUILDS
- Malaysia's PM says SoftBank's Son picked Kuching and peninsular sites for a planned $50B AI and data center investment. SoftBank hasn't commented (CNBC, Bloomberg)
- Tata Communications will spend $400-450M over 3-5 years on a 10,000km fiber network linking India's AI data centers, Mumbai-Pune-Hyderabad-Chennai first (Tata Communications)
MARKETS
- KOSPI -1.46% to 5,469.47, a 7-month low. Foreigners sold ~700B won. Samsung -1.16%, SK hynix -0.16%. Nikkei -0.8%, Tokyo Electron and Advantest -3%+. Taiwan closed for a holiday (Korea Herald, Businesskorea, Yonhap Infomax)
- Goldman cut its KOSPI target to 9,000 from 12,000 but stays overweight. Says memory valuations imply a ~65% drop in 2027 earnings (CNBC)
What it all means: The AI build is now a capital markets story. In one day Anthropic opened its books, Meta started selling stock, and SpaceX lined up a $40B GPU lease. Musk says debt has mostly shut for builders with no revenue outside data centers, so the haves and have-nots split fast. Nvidia easing HBM4 speed and 8-high stacks coming tell me supply is still the limit, not demand. My read: Korea trades like memory earnings fall off a cliff, Goldman says valuations imply a ~65% earnings drop. If SK hynix posts big numbers and real cash returns Wednesday, that gap is the trade of the week.
$NVDA $AMD $AVGO $MU $SKHY $SSNLF $EQT $RRC $GOOGL $AMZN $MSFT $CRWV $NBIS $SPCX
Follow @SingularityRes for the full data center roundup every morning.