

Snowcap is an investment firm focused on deep research and active engagement. Tweets reflect solely opinion and do not constitute investment advice.
Joined July 2020
- Tweets141
- Following20
- Followers2K
- Likes10




Pinned Tweet
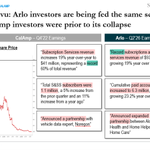
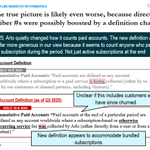
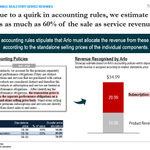
We are short $ARLO. We believe its 20% SaaS growth is illusory, built on bundle accounting games, a bogus churn rate and a $50m acquisition it barely disclosed. Its CFO ran an almost identical playbook at his previous company which later collapsed. Insiders are selling at pace.

17/ Meanwhile, headwinds are mounting: customers angered by years of price hikes, walked-back partnership promises, cheaper rivals like Eufy taking share, and Apple’s entry into home security. Arlo’s FCF is flattered by stock comp, which insiders have been selling at pace.