

SpreadHunters | Cazamos spreads; Situaciones especiales: Mergers, arbitrajes, tender offers, reestructuraciones, etc. Buscamos desajustes temporales de precio
Spain
Joined January 2026
- Tweets726
- Following286
- Followers176
- Likes246





Pinned Tweet
Después de muchos meses de trabajo, hoy por fin podemos decirlo:
🚀Lanzamos la nueva web de SpreadHunters → spreadhunters.es
Una casa para quienes disfrutan cazando spreads y situaciones especiales, no solo leyéndolas.

SpreadHunters retweeted

$BSX is looking attractive…
- 58% drawdown from ATH
- Lowest forward P/E amongst competitors (13.2x)
- New product launches announced for 27’ & 28’
- 75% of the business is still growing around 6-7%
- Two Sigma, Jane Street, AQR, & D.E Shaw have all added exposure in Q3
- Most notably, Dodge & Cox increased their exposure by 17,000% in Q3, adding over 14 million shares
Seems like the market has overreacted to short term turbulence.
Feel free to drop your thoughts below!

🍷 ¿Puede una empresa valer más mientras sus ventas siguen cayendo?
Hemos analizado Naked Wines ($WINE.L), una situación especial con una tender offer a 80p, caja neta y un importante potencial de liberación de inventarios.
Abro hilo 🧵👇
1
134
Aquí está el catalizador.
La dirección prevé liberar aproximadamente £34M de caja vinculada a inventarios hasta FY2030.
Nuestro modelo contempla picos de FCFF superiores a £20M, pero son extraordinarios.
La clave es cuánto efectivo llega realmente al balance.
1
36
SpreadHunters retweeted

$DDI gets taken out at $16.25 cash through a tender. 95% of shares must be tendered for the deal to go through. Can go lower, 90%.
Double U owns 67.05% of co
Hold outs will get acquired through a 2nd step under Korean Commercial Act
🇵🇱 TOYA S.A. ($TOA) ha presentado sus resultados Q32026🚀
Debajo dejamos las claves de los resultados👇

1
3
214

SpreadHunters retweeted

In 2010, @JohnHuber72 had a plan to raise money and buy 100 foreclosed homes.
He and a partner had spent the GFC buying houses from banks at 50 cents on the dollar. They peaked at 19 units. Shortly after, Blackstone and the big single-family rental funds moved into the same trade.
He passed. He didn’t want to spend the next decade managing houses.
He spent three years winding down the real estate and launched Saber Capital in 2013, modeled on Buffett’s 1950s partnership.
@iancassel and I sat down with John for our latest @MicroCapClub podcast.
In this episode, John explains why he moved away from his "never sell great businesses" rule. He uses Copart to show how a stock at 40 to 50 times earnings can fall 50% on a small hiccup. He also covers how he splits his portfolio between long-term compounders and a basket of Ben Graham-style bargains, how Pitney Bowes moved from one bucket to the other, and how he sizes positions so no single mistake can do serious damage. The conversation opens with his essay on the Tampa Bay Rays and what happens when everyone optimizes for the same metric.
Chapters
00:00 Intro
02:38 What the Tampa Bay Rays teach investors
09:58 Home runs vs base hits
11:29 When to sell a great business
15:41 Lessons from a self-taught investor dad
17:28 Why journalism makes better investors
19:11 Buying houses at 50 cents on the dollar
22:12 Why he walked away from real estate
24:16 Compounders vs bargains
27:51 When a turnaround becomes a compounder
32:04 Why he keeps an investment journal
34:14 Margins vs return on capital
38:39 Should you look for value overseas?
41:19 Inside his Ben Graham basket
42:31 How he sizes his biggest positions
45:38 Concentrated, but never fragile
48:01 Greenblatt, Schloss and many ways to win
51:04 How to stay in the game for decades
53:24 Why there’s no high-risk version of Saber
56:07 Do the work on your desk

In this conversation, @DavidBarbato_ and @iancassel sit down with @JohnHuber72
- John explains why he moved away from never selling great businesses.
-He covers how he splits his portfolio between long-term compounders and Ben Graham-style bargains
microcapclub.com/when-to-sel…

📄 Xponential Fitness ($XPOF): Fund 1 Investments mueve ficha.
En su última Schedule 13D/A, el fondo confirma que ha enviado una carta al board proponiendo una posible operación para adquirir la compañía y sacarla de bolsa.
💰 Rango indicativo: $5,61–$7,00 por acción en cash.

1
2
306
Fund 1 abre la puerta a incorporar otros accionistas en la adquisición manteniendo el control mayoritario.
Una fórmula que podría facilitar una operación negociada.
Además, no descarta elevar el precio si la due diligence revela mayor valor.
1
41
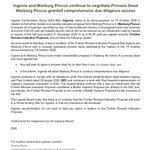
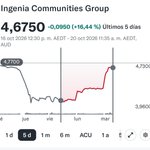
$INA.AX El mercado está reconociendo que Ingenia debería cotizar más cerca de los 5 que de los 4. A continuación comentamos los puntos clave del comunicado publicado hoy, 20 de octubre 👇


Los escenarios que se barajan:
🟢 El Board acepta → cierre: 32% → A$5,30 (+30%)
🟢 Rival: 4% → A$5,60 (+37%)
🟡 Acepta pero se rompe: 8% → A$4,00 (−2%)
🔵 Warburg se va y Peet tampoco sale: 8% → A$4,20 (+3%)
🔴 Warburg se va y Peet sí: 47% → A$3,70 (−9%)
1
2
182
Ahora se han dado de plazo máximo hasta este viernes 23 de octubre de 2026 para firmar el acuerdo de intenciones definitivo.
❌Ingenia deja muy claro que sigue adelante con sus obligaciones contractuales con Peet Limited
1
36