

Tech investor for ~25 years. Ran large hedge fund for 10 of those. Here to help. Not investment advice. I never reach out to sell ANYTHING.
NYC
Joined July 2018
- Tweets2K
- Following353
- Followers19.5K
- Likes2.5K
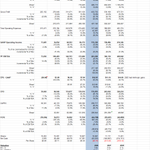
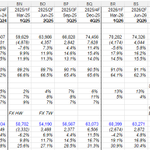
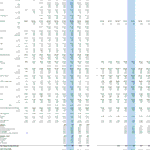
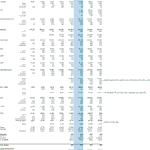

$AMZN qtr was somewhat squishy but “fine”.
Story is still getting better. AWS is accelerating and they now expect it to grow >40% in 2027 and 2028 which is pretty wild (and positive for infra trade).
Margins for the entire business continue to march higher driven by mix shift towards AWS / advertising and better cost control.
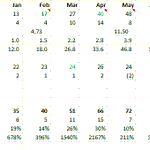
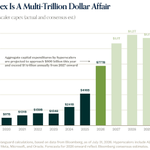
Now, this growth is more capital intensive and the company has flipped to -63b in FCF this year, -79b in 2027 and -60b in 2028; and they will have net debt of -147b at end of 2027.
Returns thus far seem fine evidenced by 2025 capex of $1 producing 0.49 incremental AWS dollars this year which is less than the 80c-100c they used to get pre-AI, but otherwise the AWS margins are nice and healthy still.
Risk / reward pretty attractive.
Upside of 62% to 25x my 2028 GAAP EPS for a company growing GAAP operating profit by 35% yy (with offset being this is capital intensive growth).
Downside of -7% to 20x street 2027 EPS. Obviously any stock can go down 20% no matter how cheap it is so let’s just go with that.
Qtr
AWS rev of 46b accelerated to 39% yy w/ 39% margin slightly down qq. Incremental margin yy was still 49% so trend is still higher even as AI is a greater part of the mix. They mentioned they are accelerating capex payback and that inference is well over half of token consumption.
Their share does continue to decrease: 42.2% share among AMZN / GOOGL / MSFT down from 46.4% a year ago.
Perf obligations only increased by 82b this qtr from 132b add in Q2 and 120b add in Q1.
NA retail was slow bc Prime day was in the prior qtr this year. Normalized growth was >12% yy which is consistent w/ prior qtrs. Advertising within this also slowed to 12% which was a big decel relative to 22-26% in Q1-Q2. Reason being Prime day was in Q1, Q3 didn’t have NBA, and lapped some SEM improvements they made a year ago. They anticipated “Agents took the traffic / ad rev” and said that wasn’t it (whether it will be down the road is a different question). Margins of 7.7% was up from 6.9% last Q3 (but apples to oranges w/ Prime Day).
Intl retail also slowed to 5% yy also partly due to Prime shift. 3.7% margin up from 2.9% last Q3 (but that included severance).

Few random points on $GOOGL:
1) Clicks grew 8% (down from 13% in Q1 / Q2 against easy comps) w/ pricing growth of 4% (consistent w/ 4-5% in Q1 / Q2 against similar comps).
Bulls will say query growth overall is healthy, AI results taking share from regular, and that search will re-accelerate as they turn on ads in AI results (especially for massive discrete regions like intl.)
Bears will say 1) Top of funnel search is moving to ChatGPT, AMZN AI, Muse, etc. and 2) Last click moving to agentic interactions like Muse.
I'm not really smart enough to figure that out.
Definitely more of my top of funnel searches are away from GOOGL, but most of my bottom funnel gets executed with GOOGL.
2) Cloud is doing great. Historically qtrly rev was ~6b ahead of adjusted backlog (total * % recognized over next 2 years / 8). Now, the big signings suggest qtrly rev will be 45b which I reach in ~3 qtrs. Backlog additions are solid (47b vs 52b in Q2 and 220b in massive Q1).
3) One big beautiful bill is very helpful for cash flow. I estimate 2026 CFO of 165b up from 125b in 2025. However, OBBB is likely ~40b of that improvement so CFO really would be flat yy. So, for some reason, CFO doesn't appear to be exploding w/ cloud growth - not really sure why.
I estimate 2026 FCF of -10b which would be -50b without the tax benefit.
That tax benefit has to be paid back at some point which will be a headwind to FCF growth at some point even when CAPEX starts to fall again.


Notes
O365
-Now have copilot across all surfaces w/ DAU up 50% qq
-90% of queries on auto-mode
-E7 doing well which includes Agent
-Number of copilot customers consuming credits through usage grew >75% qq
GTHB
-Credit consumption has 2x since kicked off
-Advanced security rev increased 50% yy as people use it to scan code
AI
-Goal w/ models is to be 3-6 mo behind frontier w/ models at fraction of cost
-MAI-Cyber powers 40% of scans in generic code scanner at 18% lower cost / scan
-Dragon transcription is super cheap
-44k paid fabric customers up 50% yy
Capacity
-Added 24 new dc’s this qtr
Azure
-120k foundry customers up 3x yy. Foundry rev more than tripled yy driven by efficiency gains across GPU fleet
Qtr
-Margins increased a bit offset by sales mix shift to Azure
-75% of capex is servers and 25% is long-lived assets
Guide
-Includes estimate for recently announced employee voluntary exit offer.
-2026 CAPEX of ~170b due to delays
-Expect to be FCF positive in FY27 – will access additional sources of funding if attractive to do so
$MSFT reported an all good in the hood quarter.
Office365 accelerated to 18% yy cc driven by people adoption copilot. They now have a cross-surface solution across all the apps and say 90% of queries use the default model. So the bull case is they do to ANT / OAI what they do to all competitors. Had a buddy who worked there and said MSFT is the only company that successful comes from behind once someone else demonstrates a big market exists (see Teams vs Slack / Zoom, Azure vs AWS, etc.). Seats are growing 5% and pricing uplift is now 13% yy cc!
Azure accelerated to 48% yy cc and they guided to 49-50% yy cc. No slowdown in the hyperscaler buildout / monetization.
OAI was 10b of rev in the qtr or 11% of rev. This is direct Azure contribution but also rev-share. Compares to OA being 24b last FY or 7% of rev. MSFT owns 24% of OAI.
O365 and Azure are now 55% of the business and I don’t care about the rest unless it slides into the ocean.
OM of 49.8% was up nicely from 48.9% last Q1. They guided to margins being down slightly including all the “Pls don’t show up tomorrow” memos they sent to 60k people. Seems conservative. I’m a bit ahead on revenue so I get margins up slightly.
Business is good at $MSFT. Revenue should accelerate this year and next FY w/ margins expanding despite the mix shift to Azure. They are the most responsible of the hyperscalers and staying FCF positive for now.
Stock trades at 22x CY27 EPS and 18x CY28. 27x presents 21% upside over the next few months and 51% upside over the next year.
Maybe downside of 13% to 22x street CY27 EPS.

Search decelerated and will continue to decelerate, after performing quite strongly in face of all AI rhetoric for past couple qtrs.
Notes
Search
-AI searches 5x longer than typical search and vast majority are additive; also see users accepting ads
-Scaling more ads in AI mode including international for first time
->50b visual searches / mo
-Will bring agentic functionality into search like reservations
Agentic
-Will have experiences available later this year
YT
-Living room was 1/3 of ads
-Subscription growing faster than ads
->150m paid users
AI
-Working hard to bring on more capacity
-GOOGL-owned model API tokens up 40% qq and 4x yy
-TPU sales have begun
>2,600 customers have used at least 1b tokens
-Have sold >100m seats for enterprise
-Ulta beauty made AI shopping assistant that takes conversion up 3x [though could be self-selecting further down funnel users]
-Gemini adoption also drives agentic which drives purchases of more actions and add-on storage / compute.
TPU
-Strong demand across wide range of customers (CalTech, etc.)
-AAPL doing pretraining on TPU
-Entered into partnerships to deliver TPU systems w/ other cloud providers like ORCL
-TPU system sale involves networking, software, etc.
Waymo
-15 cities
->300m miles to date
Gemini
->1b users
Qtr
-35% of CAPEX was for data centers / 65% for servers which are alive for 6 years
-Commitments (do have pricing / volume flexibility) - 924 commitments and 152b in other commit
$GOOGL reported a mixed quarter.
Search is 39b of segment profit in the qtr out of overall profit of 41b so understandably everyone freaks out when search is squishy.
Stock trades at 18x my GAAP 2027 EPS which is a bit above street for >30% operating profit growth.
Kind of a tough one: Search - who the hell knows, Cloud - doing great, YouTube - doing fine.
Search
Rev of 63.3b slowed to 12% yy and will likely slow to 10% yy in Q4. Tough comps along w/ China advertisers slowing since the EU stopped tax-exemption for small order e-comm. It was the worst qq Q3 since the 2022 slowdown.
Query growth remains healthy and they stated AI queries are mostly additive to traditional. Testing for ads for AI has gone fine and they will turn on monetization internationally soon.
Very hard to parse – obviously bears think search is moving to ChatGPT / Muse / etc. while bulls think search pie is just growing, GOOGL users are loyal, and GOOGL will enjoy last-click attribution (last place you search before you buy) (offset by maybe Muse becomes the last place you buy bc you tell it to find you the best deal).
Obviously tons of background questions come to the foreground with a miss, but these things don’t die overnight so my bias is probably more towards the upside bc turning on AI mode monetization can move the needle.
Margins of 41% were up from 39% last Q3.
Cloud
Rev of 29.7b (excluding maybe 1b in TPU?) accelerated to 96% yy w/ 5.0b net add vs 1.5b last Q3. They have big deals ramping through this year including the 16b ANT ARR. All good in this business line as the AI buildout continues.
TPU sales also are ramping and going well. ANT disclosed their 125-150b contract but that starts in 2028.
Margins of 37.4% up from 23.7% last Q3. There will be some pressure going forward as they use expensive SPCX capacity to fill supply-constrained gaps.
CAPEX productivity seems to be holding at around $1 of capex producing 70c of incremental forward revenue. I still have that dropping to 0.5x for 2027 rev and 0.4x for 2028 rev which means my cloud estimates might have upside.
YouTube
Rev of 11.2b grew 9% yy against a tough comp also w/ weak 152m net add vs 465m last Q3. Whatever, this business doesn’t move the needle.

Actually, clues for this question are in the S1.
Top 5 customers qq growth slowed dramatically in Q3:
Q1: 1.7b
Q2: 3.0b (1.3b add)
Q3: 3.5b (0.5b add)
All other customers:
Q1: 3.0b
Q2: 8.5b (5.5b add)
Q3: 13.2b (4.7b add, maybe 5.5b add excluding distillation hw)
Caveat: I'm assuming the top 5 stayed the top 5 and accounts didn't enter / exit the cohort.

Re: ANT S1
What's the take on META / Cursor moving to in-house models given the language below?
Seems either very clever phrasing (Q3 was peak but then eroded thereafter) or, more likely, the big customers are still fine. Or META isn't a top 5 customer.
"At the same time, our largest customers continue to expand. For the three months ended September 30, 2026, our revenue from each of our top five customers reached a record high."
The slowdown in Q3 was partly attributed to inhousing but seems like that may not have happened?
Seems like we may be good to go here:
-AI functionality is genuinely mind-boggling and ROI is obviously there (not categorically of course). People who say otherwise might as well try to convince me the sky is green. I just don't see it that way based on my lived reality.
-OAI growth expectations tempered from irrational. Funding will be completed soon.
-ANT had a soft Q3 but should accelerate in Q4. S1 looks great - no gotchas. Positive surprises in a lot of places - particularly with improving compute margins and being solidly FCF positive. IPO will get done at reasonable price. ($DXYZ).
-SPCX / META spending / capital raise plans already out there / getting completed.
-Hyperscaler earnings likely all positive.
-Semi supply constraints likely limit spending growth in 2027 regardless of customer balance sheets / appetite. Helps de-risk pace of investment and lower probabilities of a big digestion period in 2028.
-Multiples basically at trailing lows w/ US yields stabilizing / improving.
-Momentum selloff pretty fierce compared to priors w/ X filled w/ AI bears doing victory laps. So always better to be buying into negativity.
Let's see.
Seriously? Slack, INFA and now next-gen ET (BRZE)? DATA may be useless in a few years although AI obviating it isn’t there bad M&A.
Their bad M&A is literally half the reason the multiple stays low.
Great thoughts. Thx.
Curious if you have thoughts on the concern that there are now 5 players spending half their AI compute budgets on training more or less the same AGI model. So arguably half the spend is duplicative investment.
And that the models already seem pretty good for most things so maybe a rationalization post-AGI leads to a glut that isn’t far off.
I suppose that might then suggest ad potential on Muse is real. I wouldn’t mind seeing ads for other dress shoes - even if they don’t meet the criteria which Muse is using for its search.
Thx. Didn’t catch that. I’m sure they will revisit that down the road but not a good sign for monetization near term.
3 random thoughts on $META
1) Re: The Cheeky Pint podcast - It's kind of crazy they admitted that their AI buildout is a huge bet that will have "very, very, very bad" financial consequences if it doesn't work out. Especially bc monetization is likely far into the future so doesn't that suggest 2027 potentially sees material EPS headwinds as the depreciation comes online?
I get it. There isn't a way to be competitive in AI w/o making big infra bets and I'm sure they were excited in the moment about Muse success. But certainly pulled the curtain back a bit...
2) Muse is great. I get a monthly note on all local events in my area (sports, music, theater, restaurants, etc.). I paid two parking tickets with it. And I have it looking for a new pair of dress shoes and a PS5 Pro (we haven't found either to my liking so the search continues).
But I'm not sure what else to do with it so I haven't checked the app much after that.
3) I assume the Muse data will be added to the knowledge graph. That's interesting bc now META knows far more about me and my ongoing searches. I would think that has to improve targeting / pricing on core META properties.
As opposed to just showing me general products that match my interests / pixel data, they now know that I am in need of new dress shoes on an ongoing basis since the search is still outstanding - and I would think advertisers that have shoes exactly like or even adjacent to what I'm looking for would want to target me on FB / IG.
Anyways, the thought is maybe monetization of Muse actually first shows up as higher monetization of core META.
Good point. Although if I were management and supply constraints limited growth, I would definitely say that in the S1 / meetings.
