

Investor @ 2006 | CA | US CFA L3 WIP | Ex-HSBC & Soc Gen Research Analyst, Director | FTI | My posts on X are not Buy/Sell Reco. DYODD.
Bengaluru
Joined February 2023
- Tweets33.8K
- Following1.5K
- Followers10.1K
- Likes4.8K




Pinned Tweet
The only way you can affect the future is by what you do today.
We can’t change the past, but future can be changed with action!


The “powerful” reset begins 🚀💥💥

FT: Anthropic just paid $3.4B for 1.7GW of Caterpillar gas generators, the largest known power-equipment purchase by an AI lab.
It took over orders that OnePWR Solutions, a San Antonio supplier, placed 2 years ago but could not finance.
Anthropic had planned to be a OnePWR customer, but instead bought the engines plus the engineering and construction work to install them.
Because those orders predate the price surge, the engines arrive over the next 2 years rather than joining manufacturing queues that now run for years.
xAI took a similar route with $2B of mobile gas turbines this year, while Alphabet bought energy developer Intersect in late 2025.
Anthropic has disclosed nearly $900B in computing commitments through 2045, secured largely through partners at premium prices for power, chips and land.

11
2,250
@GoldmanSachs view is that post-midterm restrictions would push activity into 2029/30 while leaving the total addressable market intact. Medium/low-probability projects face significant schedule uncertainty.

Narrative violation: @GoldmanSachs raises data center spending forecast for 2026/27 and 2028.
@GoldmanSachs sees $125bn data center spending in 2028. Texas adds timing risk.
@GoldmanSachs raises its US data center spending forecasts for 2026/27 to $80bn/$100bn and adds $125bn for 2028. Its forecast has double-digit growth through 2028, with spending remaining above 2026 levels through 2030.
The capacity forecast rises from 65GW in 2026 to 143GW in 2030. @GoldmanSachs puts the high-confidence pipeline at $900bn, with 86GW under construction and 171GW in high-probability projects. The spending outlook depends on when that pipeline gets built.
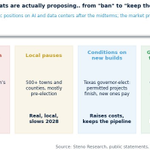
Texas is the immediate timing risk. A proposed construction moratorium would affect 20%/27% of 2027/28 under-construction additions. @GoldmanSachs sees delay and cost risks, with $IREN most exposed and $CLS / $ANET facing knock-on risks from slower AI infrastructure deployment. Its view is that post-midterm restrictions would push activity into 2029/30 while leaving the total addressable market intact. Medium/low-probability projects face significant schedule uncertainty.


2
987
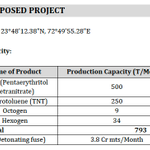
Beezaasan : 1HFY27 - In line with expectations. The real capex is happening for Defence Explosives in Asawara Earthtech Limited (35% owned as of now) which the company is working on 100% merger with Beezaasan.
Revenue grew by 14.3% HoH
EBITDA grew by 73.9% HoH 😇
EBITDA margin 11%, + 377bps HoH
PAT grew by 66.7% HoH
During the 1HFY27 the company raised 29.53cr funds via preferential issue at Rs.570/share with participation from Ashish Kacholia 19.7cr, Kadayam Ramanathan Bharat 6.5cr, and Ashika Global Securiities Limited 2.85cr.
The Asawara's defence explosive plant should be operational soon (usually 24-36 months from EIA study by GPCB, April 2024) and all the products should come online one by one by the end of FY27 or early 1QFY28.
Market estimates for FY27 / FY28 / FY29 PAT are for 14-17cr / 35-50cr / 80-100cr depending upon the scale-up of the new plant(s). Execution remains key!
No buy/sell recommendation.
gpcbmhd.gpcb.gov.in/(S(5lulv…


Data Centres Need Power ! A powerful supercharge coming!
I am expecting a pause in the Data Centre capacities in the US to "supercharge" the power sector globally, especially India as the hyperscalers scout for other locations outside the US.
The dramatic surge in U.S. data center capacity has badly outpaced growth in power generation, creating an unprecedented strain on the electrical grid.
US consumers have been hit hard due to rising electricity prices. U.S. electricity prices have climbed roughly 23% to 30% since 2020/2022, rising significantly faster than overall inflation.
So, the US is choosing to pause the further development in Data Centres to tighten the regulatory supervision and bring down consumer inflation which was amplified by the Iran war.
Around 1 million jobs in the US are directly employed within the data center industry itself (such as data center technicians, engineers, and site managers).
I don't think the under construction Data Centre Capacity in the US will be stopped. According to industry reports for mid-2026, the United States has roughly 43 GW to 66 GW of total data center capacity currently under construction, with Cushman & Wakefield noting 37.7 GW under construction across the Americas (91.7% of which is precommitted).
Industry trackers like Cushman & Wakefield note that around 91.7% to over 80% (CBRE) of under-construction capacity is pre-leased or precommitted, meaning developers have cleared primary commercial hurdles for those blocks.
A substantial portion of the broader pipeline faces severe friction. For instance, national interconnection queues exceed 2,600 GW (stretching median approvals to five years), and hundreds of billions of dollars in projects have faced local delays, moratoriums, or political pushback.
A large percentage of planned and under-construction capacity is situated in states where incoming or sitting governors have proposed or enacted moratoriums, stricter environmental reviews, or power-usage guardrails (such as Texas, New York, Pennsylvania, and Virginia). Projects experiencing permit or power-allocation disconnects face significant slip times (12 to 18 months or relocation).
Around 30% to 50% of large-scale data center capacity slated for 2026—representing roughly 5 GW to 8 GW out of 16 GW of planned capacity (with only about 5 GW actually under construction)—faces delays or cancellations due to power, transformer, and interconnection bottlenecks.
Hyperscalers are mostly responding by bringing their own power within the US, rather than leaving. OpenAI says every future data center campus it owns will pay its full electricity and grid costs, post financial guarantees in case a project is cut. The real goal is to ease growing local anger over power bills.
US constraints are real and will push some capacity abroad, and India is one of the best-placed places to receive it.
India can attract a lot of Data Centre investment !
India has rolled out targeted federal and state policy actions to accelerate data center capacity, lower capital costs, and support AI-driven digital growth.
Key Central Policy Actions
Infrastructure Status: In the Union Budget 2022–23, the Ministry of Finance granted data centers Infrastructure Status (under the "Communication" category), putting them on par with national highways and power grids to unlock cheaper, long-term institutional credit.
Tax Holidays for Cloud Providers: The Union Budget 2026–27 introduced a long-term tax holiday extending until 2047 for eligible foreign cloud service providers utilizing India-based data center infrastructure for global operations (covering Tax Years 2026–27 to 2046–47).
NITI Aayog Evaluation Framework: In October 2026, NITI Aayog released a standardized Data Centre Evaluation Framework developed with MeitY, DPIIT, and the Ministry of Power to help state governments evaluate investment proposals, map grid and fiber readiness, and designate green or exclusion zones.
IndiaAI Mission: Backing compute infrastructure growth, the national mission has allocated significant high-performance GPU and sovereign compute capacity.
State-Level Policy & Incentive Actions
Maharashtra Green Data Centre Policy Amendments (June 2026): Expanded integrated green data center park limits from 3 to 20 projects, broadened scope across the state, adjusted core green power mandates to 51%, and introduced electricity tariff subsidies (₹1 per unit for 10 to 20 years depending on scale). [6]
State Financial & Land Incentives: States like Maharashtra, Haryana, Odisha, and Uttar Pradesh provide customized packages including permanent electricity duty exemptions, capital subsidies (up to 20%), and land subsidies (25%–50%).
The US mid-term elections have dramatically accelerated the timeline and targets for India's digital infrastructure. India’s projected data center (DC) capacity targets are now set to expand five-fold to 7.5 Gigawatts (GW) by March 2030, with aggressive benchmarks stretching up to 8–10 GW by the end of the decade.
Previously, the timeline to scale from 2 GW to 7.5+ GW was seen as a relaxed, decade-long transition driven mostly by domestic enterprise digitization, 5G, and internal data consumption. Following the policy shifts in major US tech states post-elections, the minimum expected baseline target has effectively been locked at 7.5 GW by March 2030, pushing the new maximum target boundary past 10 GW to manage shifted global hyperscaler infrastructure.


Power Sector : Structural Shift to Underground Cabling: Under the National Electricity Policy 2047, the central policy framework aims for 100% undergrounding of power cables in cities with populations exceeding 10 lakh.
Comments from power sector companies on 2QFY27 concall
The Power Transmission and Distribution (T&D) sector in India is experiencing a multi-year capex super-
cycle, driven by aggressive grid expansion, renewable energy integration, and urban infrastructure
modernization.
🟢 National & State T&D Capex Expansion: India plans to add approximately 1.4 lakh circuit kilometers (ckm)
of transmission lines and 870 GVA of transformation capacity by 2032 to accommodate rapid demand
growth and green energy evacuation.
🟢 Structural Shift to Underground Cabling: Under the National Electricity Policy 2047, the central policy
framework aims for 100% undergrounding of power cables in cities with populations exceeding 10 lakh. In
Gujarat, the 'Gujarat Wire-Free City Mission' targets converting overhead power lines to underground
networks across 17 municipal corporations and 161 municipalities by 2030 (over 46,000 ckm total), with
Phase 1 backed by a 500 crore allocation.
🟢 Higher Voltage & Complex Infrastructure: T&D execution is moving rapidly into higher voltage classes (400 KV and upcoming 765 KV networks by state utilities like JETCO and Power Grid). This includes Gas Insulated Substations (GIS), High Voltage Direct Current (HVDC) lines, river-crossing transmission lines, and specialized pipe foundations. The Green Energy Corridor Phase 3 (GEC3) scheme approved an overall outlay of 1.86 lakh crore ( 1.36 lakh crore for intrastate transmission and 50,000 crore for BESS) to evacuate 135 GW of renewable energy.
🟢 Battery Energy Storage Systems (BESS): Renewable energy integration is driving mandatory grid-scale BESS
adoption to mitigate intermittency and meet peak demand. India's cumulative BESS requirement is
projected at 47 GW / 50 GWh by 2032, encouraging EPC contractors to establish standalone BESS EPC
execution capabilities and domestic manufacturing plants.
🟢 Smart Grid & Digital Automation: Power utilities are accelerating adoption of SCADA, Industrial IoT,
Distribution Management Systems (DMS), and Smart Feeder Monitoring Systems (SFMS) for real-time grid
automation and reliability.
🟢 Tendering Activity & Pipeline Visibility : Tendering activity from GETCO surged in September and October
2026. Active bid pipeline stands at 3,500–4,000 crore across T&D, underground cabling, SCADA/DMS, and BESS EPC.