

I’m mostly known for calling out the dips of great companies | DYODD | 15% OFF on FiscalAI (Code: "VALUEINVESTOR" at checkout)👇
London
Joined June 2025
- Tweets3.1K
- Following374
- Followers1.4K
- Likes1.2K




Pinned Tweet
I'm thinking of buying $NBIS for one simple reason.
Today, Nebius is running roughly 20k GPUs.
The plan is ~60k end of FY and ~240k by 2027+
That's a 5x fold increase.
And the CEO has hinted at something even more aggressive: up to 1 GW in 2026
That’s the opportunity.

Just finished the Athens Authentic Marathon in 4.5 hours
My takeaways directly affect $DECK and $ONON and here they are:
1) I personally was wearing $NKE ‘s vapor fly but I was pleasantly shocked to see that most Elite Athletes aren’t necessarily wearing $NKE . Saw a lot of Adidas and New Balance
2) A huge number of people are rocking $ONON’s and $DECK (Hoka) but most importantly I could see a lot of people wearing On Merch. That’s very bullish as clothing for On has a lot more room to grow
3) Most importantly. Once you become a marathon runner you never go back. The amount of people that are simply obsessed with running and continue to buy shoes + clothes will continue to grow. The lifespan of a running shoe is around 500km. I personally did 800km of training + race. So I own HOKAs as well (as my 2nd pair). IMO On Running and Hoka are well placed to continue to capture market share
Overall I’m quite optimistic with brands directly affiliated with running

People ask me why I'm bullish on $ETOR
This is why
The CEO @yoniassia wants to make $ETOR a 100 billion dollar brand
The target couldn't be more obvious
Get to $100B AUA by 2030 and $1 Trillion by 2040
Picture from @StockMentor_UK

Interesting take on $ALC from Bill & Team in their Q3 letter
$ALC trades at 17x earnings, the lowest multiple it has ever had, vs an average in the high-20s since its IPO. Alcon is one of seven new positions this year for $PS
The stock is down 5% this year. That would make sense if the business were slowing, but Alcon just raised full-year guidance to 12-15% constant-currency EPS growth, and Pershing’s long-term estimate is mid-teens.
I’ll be honest about what’s missing. The letter gives the multiple and the guide, not the reason the multiple collapsed, so I’m not going to make one up. What I can see is a medical-device company that raised its outlook and is being valued like one that cut it.
One more detail: Alcon is US-domiciled, with its operational HQ in Texas, and dual-listed in Switzerland. That makes it easier for US investors to own than its Swiss listing suggests.
So what for investors: If guidance holds at 12-15% and the multiple drifts back toward its history, the earnings growth does most of the work. If the multiple stays at 17x because the market doesn’t trust the guide, growth alone has to carry the return. Watch the next quarter’s EPS growth against that 12-15% range.

We just released the Pershing Square Inc. third quarter letter which includes an update on the business, a detailed portfolio review including an update on F2, some thoughts on AI and the hyperscalers, and our perspectives on recent developments in the capital markets. It can be found here:
pershingsquareinc.com/wp-con…
$TEAM grew revenue 24%, took non-GAAP operating margin from 23% to 32%, and the stock lost about 16% because of one number: subscription ARR growth guided to roughly 18.5% for the year.
That is terrible news for SaaS companies reporting later this month $ADBE $CRM
$TEAM ARR grew about 23% this quarter, cloud growth is guided to about 27% next quarter from 31%, Data Center revenue is guided down about 16% for the year, and Truist called the outlook "underwhelming".
But look at what didn't change. Cloud revenue still grew 31%, free cash flow was $463M (a 26% margin), RPO grew 44%, and the company bought back more than $580M of stock in the quarter. The forward P/E was about 33x before the drop and about 28x after, against a five-year average of 81x. This is a cash-generating business still growing over 20%, priced like growth is over.
So what for investors: If cloud growth holds in the high 20s while Data Center shrinks, the blended ARR number is a trough and this drop was a mix scare. If cloud growth keeps stepping down toward the low 20s, 31% was the peak and 28x is not cheap.

$AXON grew revenue 28% to $909 million, and the stock is getting sold after hours because it trimmed its growth forecast.
The 2026 growth outlook is now about 30%, down from 32% to 34%, and growth has slowed from the 35% it printed last quarter. For a stock priced for acceleration, a lower guide hurts.
But look at the size of the cut against the size of the business. A company still growing revenue at 28% is guiding to 30% for the year, and the source says the cut excludes about $130 million of federal drone deployments, which is a specific line, not a broad demand problem. Last quarter ARR grew 39% to $1.6 billion with net revenue retention of 126% and a 26.8% adjusted EBITDA margin. Customers who buy more every year don't disappear in one quarter.
So what for investors: If ARR growth stays in the high 30s and net revenue retention stays above 120%, the cut is a timing story and the sell-off is overdone. If ARR growth starts closing in on revenue growth, the forecast cut was the first sign of a real slowdown.

Months ago I’ve talked about how the cyber truck was quickly becoming a flop
Today’s news solidify that argument
$TSLA

$F Ford’s Edsel is the textbook example of an automotive flop, but $TSLA's Cybertruck is now trying very hard to take that crown.
Musk once talked about building 250k+ a year and called it the best product ever, but through May this year only about 7,133 have been registered in the US, and a big chunk of that was SpaceX buying its own fleet.
Prices started above $100k for early buyers, deliveries were years late, the cheapest version is still around $61k, and the thing has already been recalled roughly 10 times in under two years.
There are lawsuits over doors that wouldn’t open after crashes, production headaches from day one, and reviews that ranged from “weird” to “what were they thinking.”
At this point it’s not just a slow seller; it’s becoming the modern Edsel, but with a cult following and a lot more X noise.

Why semis are in risk, let's analyse $NVDA
$NVDA fell 9.26% to $181.60. That wipes out its entire 2026 gain, and the trigger was a political fear about data-center permits.
UBS says about 30% of 2028 data center additions are now at risk, and Reuters reports public opposition to data centers rising in key states where Democrats won.
But look at how the market priced it. The semiconductor index fell about 12%, its second-biggest drop on record, and the average of eight big chip stocks was down 12.97%. $NVDA fell less than the group.
I'd rather argue with the market about a permitting risk that is still a fear than about an order book that has been cut.
So what for investors: If the data-center rules stay at the pledge stage and the buildout continues, this was a two-day policy scare and the 2026 gain was handed back for nothing. If states start blocking approvals at scale, the UBS 30% becomes the real number and chip estimates have to come down. Watch which states turn pledges into binding rules.

Is $CVS splitting is bad news for investors?
$CVS beat EPS by 44 cents ($2.09 vs $1.65), raised its full-year guide, and the stock fell about 12.5% because it's splitting into two companies.
The bear point is the split. Unwinding the 2007 Caremark merger and the 2018 Aetna deal won't be done until the first half of 2028, which means more than a year of distraction, and pharmacy and insurance lose the integration that was the original pitch.
But look at what the quarter actually said. Insurance operating income jumped to $912M from $314M, the medical benefit ratio improved to 91.3% from 92.8%, and 2026 adjusted EPS guidance went to at least $8.20 from $7.90-$8.10, ahead of the $8.04 consensus. Full-year operating cash flow guidance went up to at least $15.5B from $11.5B. That's a business getting healthier right now.
The market is selling the org chart, not the earnings. I think a company that just fixed its insurance margins deserves a better reaction than this.
So what for investors: If the standalone insurer keeps closing the gap toward UnitedHealth's 88.4%, the split looks like a catalyst. If the pharmacy side loses its scale benefits and the dis-synergies run past what management budgeted, the discount was right.
Apart from AI CAPEX is reaching its peak moment, $QCOM earnings shows a setback..
$QCOM's handset revenue fell 26% to $5.14B. The same quarter had automotive up 89% to a record $1.99B.
The bear point is real. Handset revenue came in under the $5.21B analysts wanted, the Q1 EPS guide midpoint of $2.25 sits below the $2.27-$2.32 consensus, and management said rising memory and manufacturing costs only get fully offset in the second half of fiscal 2027.
But the headline is about the shrinking part of the business. Automotive and IoT are about $3.9B, close to 38% of revenue. Q4 revenue was $10.32B vs $10.11B expected, and the Q1 revenue guide midpoint of $10.8B is above the roughly $10.5B consensus. The CEO says non-handset revenue should grow more than 60% next year, and the company is targeting about $5B of data center revenue in fiscal 2027.
I think the market is still valuing this as a phone chip company, and the numbers say it's turning into something else.
So what for investors: If data center revenue ramps toward that $5B target, handset stops being the story and today's drop was a handset scare. If data center slips, there isn't enough in automotive and IoT to cover a 26% handset decline.
Bulls are saying AVs will be a catalyst for $UBER
Waymo just told them, get ready for the BEAR case scenario
Here’s what happened..
Waymo and Uber are consciously uncoupling.
Waymo Co-CEO Tekedra Mawakana told Bloomberg that the company plans to end its exclusive robotaxi partnership with Uber, currently in Austin and Atlanta, in January 2028.
Mawakana said the Alphabet-owned autonomous car company was pulling out of the partnership and making rides available in those cities on its own app instead.
This is terrible news for UBER and exactly what I’ve been flagging again and again. Uber is fairly traded based on the risks

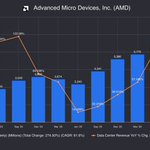
If Data Center revenue continues to grow at this scale (e.g. 100%) for the next 3 years, we are looking at an ARR at roughly $272B in 3 years
Do you think that's plausible?
$AMD

Covering Uber's earnings + Bill Ackman's remarks in my latest vid
youtu.be/fREDFoxRBt0?si=Eerb…
Check it out ;) $UBER

Having read the letter, I think Bill & team have some interesting assumptions on $UBER here
Pershing Square’s new letter says $UBER trades at 16x earnings, its lowest valuation ever, while earnings are on pace to grow about 35% this year. Those are their estimates, but the gap addressed here is hard to ignore.
The reason is autonomous vehicles. The stock is down 16% this year on the fear that robotaxi owners go direct and cut Uber out. That’s a real risk that I have also flagged a few times and I’m not going to pretend it isn’t. Pershing itself points to AV operations in London, Dubai and Croatia and a target of 15 cities by year-end, so this is happening now.
But look at what the market is pricing. DoorDash trades at 30x, or 38x on a normalized tax rate, per the same letter. If indeed the $UBER business potentially is growing earnings 35% at roughly half the multiple of its closest peer, then this is not what a company on the way out looks like.
So what for investors: If AV operators keep needing a demand network to fill their cars, Uber becomes the aggregator and 16x is a mispriced compounder.
If AV owners build their own demand (e.g. $TSLA) and go direct, earnings growth slows and 16x is fair or even quite expensive. I'm closely watching how these 15 AV cities actually launch on Uber.
$SHOP grew revenue 32%, posted a 22% free cash flow margin, powered $119B of GMV, and lost almost 9% in a day.
The bear point is specific. Revenue of $3.74B was a hair under the $3.75B expected, and GMV and subscription gross profit both came in light. Next quarter's guide has gross profit growing at a high-twenties rate while revenue grows low-thirties, so gross profit is growing slower than revenue.
But this is a slight miss on a growth rate most companies this size can't get near. Operating expenses are guided to 29-30% of revenue, stock comp to $155M, and the company is still turning more than a fifth of revenue into free cash.
The stock was down as much as 15% before the open and recovered to about -9%. Buyers showed up.
I think this is a growth stock held to a perfection standard
So what for investors: If gross profit growth catches up with revenue growth, the miss was noise and the margin story stays intact. If gross profit keeps lagging revenue, the market is right to ask what the growth is costing.

HUGEE !! $ETOR]

etoro ha firmado un acuerdo para adquirir a @lb_finanzas, la app financiera integral.
Juntos, ofreceremos a los inversores argentinos nuevas formas de hacer crecer su patrimonio, acceso a educación y una experiencia totalmente localizada.
Damos la bienvenida al equipo de LB Finanzas y a sus clientes a etoro.
👉 etoro.tw/4sM5zEs

$IT beat EPS by 75 cents ($3.59 vs $2.84), accelerated contract value growth for a third straight quarter, raised its full-year guide, and still got hit for 13%. I think this is next for $ACN which is why I sold at $260..
The adjusted share count fell from 75.0M to 63.9M, so a lot of that EPS beat is buybacks, not business growth. Revenue excluding the sold Digital Markets unit grew just 2.4%. And the fear underneath is simple: if AI tools change how companies buy research, why keep paying for Gartner?
But contract value is the leading indicator for a subscription business, and it's accelerating, not rolling over. Free cash flow was $275M in the quarter, the FCF guide is now at least $1.235B, and the whole company was worth about $12.3B at the worst of the morning drop. That's roughly a 10% free cash flow yield (own arithmetic) on a business whose forward indicator just got better.
The stock also ran about 25% in the month before the print. Some of this is a crowded trade unwinding.
So what for investors: If contract value growth keeps accelerating, the AI-disruption story stays a headline and a 10% FCF yield won't last. If contract value growth rolls over next quarter, the bears were early, not wrong, and buybacks can't hide it.

What happened with $TRI should be a WARNING for SaaS reporting soon like $ADBE $CRM etc.
$TRI grew organic revenue 10%, took adjusted EPS up 14%, and the stock closed down about 10%.
Here's the real bear point. Free cash flow fell 23% to $408M, adjusted EPS of $0.81 missed the $0.83 consensus by 2 cents, and management guided Q4 organic growth to about 8%, down from 10%.
But look at what's underneath. Recurring revenue is 88% of the total. Legal, Corporates and Tax each grew 9-10% organically, and the three-segment full-year guide didn't move: 9.5-10% organic. The cash flow drop came from working capital and higher cash taxes, not customers leaving. GenAI-enabled products are now about a third of annual contract value, so this looks like a subscription business with AI inside it, not one being replaced by it.
I'd rather argue with the market about timing than about the franchise. A 2-cent miss doesn't justify a 10% reset for a business built on this much recurring revenue.
So what for investors: If Q4 organic lands near 8% and the three core segments hold 9-10%, this was a one-day overreaction to a small miss. If core segment growth starts sliding toward single digits as AI tools take legal research share, the premium for recurring revenue goes away.


People celebrating that Elon Musk lost $500 million dollars, don't actually realize that 500 million dollars for Elon Musk is the equivalent of
$500 dollars for a Millionaire
Peanuts
$UBER Q3
Y-Y total trips and Y-Y Monthly Active Platform Customers continue to face a slowdown in growth
