

| Tech & hard-tech fundamentals | FCF, moats & valuation | Long-term framework over short-term noise | NFA
Los Angeles
Joined April 2021
- Tweets291
- Following40
- Followers505
- Likes461



🤯 SOFI'S CEO BELIEVES THIS COULD BECOME A $1 TRILLION COMPANY!
Today, $SOFI is a fraction of that potential.
And here's the engine that could drive its growth: CROSS-SELLING.
Look at the numbers:
🔥 17.1 MILLION members.
🔥 26.7 MILLION financial products.
🔥 51% of new products are now opened by existing members.
🔥 Products grew 44% year over year.
Here's why this matters:
Every time an existing member opens another SoFi product, the company has an opportunity to generate more revenue without having to acquire an entirely new customer.
More products per member.
Higher customer lifetime value.
Stronger relationships.
Better customer acquisition economics.
And this flywheel is still developing.
SoFi has already guided for:
📈 $840M in 2026 net income.
📈 $1.28B in 2027 net income.
The company is also targeting 100 MILLION products by 2030.
Think about the long-term potential if SoFi continues expanding its ecosystem across banking, lending, investing, payments, stablecoins, and financial technology.
A trillion-dollar valuation is an ambitious vision, not a guarantee.
But I'm paying close attention to the business model that could make SoFi much bigger.
$SOFI IS BUILDING AN ENTIRE FINANCIAL ECOSYSTEM — NOT JUST ANOTHER DIGITAL BANK. 🚀
🚨 JANE STREET JUST DISCLOSED A 6.5% STAKE IN $IREN!
This is a major institutional position.
According to its latest Schedule 13G filing:
🔥 27,353,819 shares beneficially owned
🔥 6.5% ownership in IREN
🔥 Ownership threshold crossed on November 12
🔥 Filing submitted on November 18
The breakdown:
• Jane Street Capital: 22.90M shares (5.4%)
• Jane Street Global Trading: 4.34M shares (1.0%)
• Jane Street Europe: 120,000 shares
Think about that.
While investors debate IREN's debt, volatility, and execution risks, one of the world's major trading firms has disclosed beneficial ownership of more than 27 MILLION shares.
To be clear, this is a Schedule 13G passive ownership disclosure, not proof of a long-term bullish investment thesis.
But institutional involvement at this scale is certainly worth watching.
$IREN remains one of the most closely watched names in the AI infrastructure buildout. 👀🚀

🔥 $NBIS investors, take note!
The U.S. Senate has passed an energy permitting reform bill (by a vote of 62–33) aimed at accelerating the development of power and data center infrastructure.
NBIS is currently expanding its AI Cloud business—a move that will inevitably require greater power capacity and more data center space.
As demand for AI continues to grow, the real key is whether infrastructure can keep pace.
The next frontier in the AI Cloud race may well come down to power availability and speed of delivery! $NBIS


🚨 @grok , I HAVE ONE QUESTION FOR YOU.
WHICH STOCK HAS THE BIGGER FUTURE: $NBIS OR $SOFI?
I'm heavily invested in BOTH.
But I want you to settle a debate.
🔥 $NBIS — THE AI INFRASTRUCTURE BET
AI demand is exploding. Nebius is building massive GPU infrastructure, expanding AI Cloud and positioning itself to become a major player in the global AI economy.
Could this become a $100B+ company by 2030?
Or will massive CapEx, financing needs and competition destroy the upside for shareholders?
🔥 $SOFI — THE FINTECH DISRUPTOR
SoFi is building a financial ecosystem with banking, lending, investing and technology services.
Could it become one of America's biggest digital financial platforms?
Or will competition, credit risk and valuation pressure limit its growth?
HERE'S THE CHALLENGE:
Imagine you have $100,000 and cannot sell for the next 5 years.
Would you put it into:
$NBIS — AI infrastructure.
$SOFI — Fintech and digital banking.
Split it between both.
I currently hold:
• 8,000 shares of $NBIS.
• 25,000 shares of $SOFI.
I want your boldest prediction for BOTH stocks by 2030.
Which has:
• Greater upside potential?
• Stronger competitive advantage?
• Better risk/reward?
• Higher probability of becoming a multi-bagger?
And which one could disappoint investors the most?
NO GENERIC AI ANSWERS. GIVE ME THE NUMBERS AND THE REASONS.
@grok , if you had to bet your own money, WHICH ONE WOULD YOU CHOOSE?
I want the bull case. I want the bear case. I want the uncomfortable truth.
Everyone wants to find the next big winner.
I'm trying to figure out which of these two could actually deliver.
If you're holding $NBIS or $SOFI, FOLLOW ME.
Let's see who gets the 2030 call right. 🚀

🚨 33,000 SHARES. TWO BIG BETS ON THE FUTURE. I'M NOT BACKING DOWN.
People see red numbers.
I see two companies I'm betting on for the long term.
Here's where I stand:
🔥 $NBIS — 8,000 SHARES
• Average cost: $131.88
• Position value: $845,080
• Portfolio allocation: 50%
• Unrealized loss: $209,920
🔥 $SOFI — 25,000 SHARES
• Average cost: $15.34
• Position value: $371,000
• Portfolio allocation: 45%
• Unrealized loss: $12,550
COMBINED POSITION:
• 33,000 shares
• $1.21 MILLION in market value
• $1.44 MILLION invested
• $222,470 in unrealized losses
Yes, that's a massive position.
And yes, the market is testing my conviction.
But my focus hasn't changed:
$NBIS is my bet on the AI infrastructure revolution.
$SOFI is my bet on the future of digital financial services.
Two different industries. Two massive long-term opportunities.
I'm not expecting every trading day to be green. I'm looking at where these businesses could be years from now.
THE QUESTION ISN'T HOW MUCH I'M DOWN TODAY. IT'S WHAT THESE COMPANIES COULD BECOME TOMORROW.
Are you holding $NBIS or $SOFI?
Follow me if you want to track the journey — the wins, the losses, the risks and everything in between.
LET'S BUILD CONVICTION, NOT CHASE HYPE. 🚀
🚀 FROM AI COMPUTE TO TOKENS — $NBIS COULD BE ENTERING ITS NEXT GROWTH PHASE!
AI Cloud is powering Nebius' growth today.
But here's what investors may be underestimating:
INFERENCE COULD BECOME A MASSIVE SECOND GROWTH ENGINE.
Look at Token Factory:
🔥 Contract value surged 17X QoQ in Q3 2026.
🔥 Approaching a multi-hundred-million-dollar annualized run rate.
🔥 Supporting leading AI models from day one.
🔥 Expanding into post-training, AI agents, and enterprise inference.
Here's why this matters:
AI training builds the models.
Inference puts those models to work — generating tokens, powering applications, assisting businesses, and running AI agents.
And as AI adoption expands, the demand for inference could grow dramatically.
Nebius isn't just selling GPU capacity.
It's building an integrated AI platform designed to capture more value across the entire AI lifecycle.
AI Cloud is the growth engine today. Token Factory could be another major engine tomorrow.
The long-term opportunity for $NBIS is much bigger than simply renting GPUs. 📈

🚨 ROSENBLATT IS STILL BULLISH ON $NBIS — AND IT'S NOT BACKING DOWN!
Despite last week's earnings reaction and the Vineland data center delay, Rosenblatt analyst John McPeake is maintaining:
🔥 BUY rating
🔥 $304 price target
Here's what stands out from the Q3 results:
📈 Revenue came in 7% ABOVE Rosenblatt's forecast.
📈 EBITDA exceeded the analyst's estimate by an impressive 57%.
📈 Revenue grew more than 6X year over year.
And what about the Vineland setback?
McPeake described it as a "slight blemish" on an otherwise strong quarter, expecting the disruption to be temporary.
Think about that.
The market is focused on near-term delays, while this analyst is still focused on Nebius' enormous AI infrastructure opportunity.
Of course, execution and funding remain important risks. A $304 target is an analyst forecast, not a guarantee.
But one thing is clear:
Rosenblatt hasn't abandoned its bullish thesis on $NBIS.
The long-term AI infrastructure story is far from over. 🚀

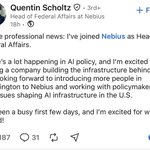
👀 $NBIS IS THINKING SEVERAL STEPS AHEAD.
Nebius is building more than AI data centers.
The company is looking to establish its federal affairs presence in Washington, D.C., bringing in dedicated leadership to engage with policymakers and help shape discussions around America's AI infrastructure future.
And look at the key areas:
🔥 AI regulation
🔥 Energy and power infrastructure
🔥 Data center permitting
🔥 Trade policy
🔥 National security
Here's why this matters:
The next phase of the AI race won't be determined by GPUs alone.
Access to power, infrastructure approvals, government relationships, and regulatory clarity could all play a major role.
Nebius clearly understands that scaling an AI cloud business in the U.S. requires more than just capital and computing capacity.
They're building the infrastructure, expanding the business, and preparing for the policy environment around it.
That's long-term strategic thinking.
I'm watching $NBIS closely. 🚀


🚨 $SOFI IS EXPANDING ITS REACH INTO THE GLOBAL CORPORATE PAYMENTS MARKET!
Mesh Payments is deepening its relationship with SoFi — and this goes WAY beyond traditional card processing.
Mesh CEO Oded Zehavi confirmed three important developments:
🔥 1. SOFI BANK SPONSORSHIP
Mesh was the first partner in SoFi's bank sponsorship program, expanding its relationship beyond Galileo's payment processing infrastructure.
🔥 2. BIG BUSINESS BANKING
Mesh is participating in SoFi's Big Business Banking ecosystem, connecting traditional banking with digital asset infrastructure.
🔥 3. SOFIUSD EXPANSION
Mesh has joined SoFiUSD initiatives and plans to explore additional services built around SoFi's stablecoin infrastructure.
Now look at Mesh's distribution potential:
• 1,500+ corporate customers globally
• Several BILLION dollars in annual card spending
• Growing demand for modern corporate payment solutions
HERE'S WHY I'M BULLISH ON $SOFI:
SoFi isn't just competing to be another digital bank.
It's building an entire financial infrastructure ecosystem:
Banking.
Payments.
Galileo technology.
Stablecoins.
Enterprise financial services.
And companies like Mesh can help expand the reach of that ecosystem.
Imagine the long-term opportunity if more corporate customers begin using SoFi-powered banking and digital payment services.
SOFI IS BUILDING BEYOND CONSUMER BANKING — AND I BELIEVE THE MARKET MAY BE UNDERestimATING THAT OPPORTUNITY.
I'm bullish on $SOFI's long-term vision. 🚀📈

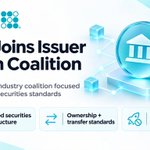
🚨 $SOFI JUST JOINED THE TOKENIZED SECURITIES REVOLUTION!
SoFi has officially joined the Issuer Token Coalition, alongside DRW, Flow Traders, and Superstate.
The coalition now has 12 firms working to build the standards and infrastructure needed to bring traditional stocks onto blockchain networks.
Here's what they're working on:
🔥 Tokenized stock issuance and ownership records
🔥 On-chain secondary-market trading and liquidity
🔥 Blockchain infrastructure and technical standards
🔥 Distribution through financial platforms
WHY THIS MATTERS FOR $SOFI:
SoFi isn't just building a digital bank anymore.
It's positioning itself at the intersection of traditional finance, blockchain technology, and the next generation of financial markets.
Imagine a future where stocks can be issued, transferred, and traded through blockchain infrastructure with greater efficiency and potentially around-the-clock access.
And SoFi wants to be part of building that future.
THIS IS BIGGER THAN A STABLECOIN STORY.
SoFiUSD is one piece of the digital finance opportunity. Tokenized securities represent another potentially massive market.
I'm increasingly bullish on SoFi's long-term strategy.
The future of finance is evolving. $SOFI is positioning itself to participate. 🚀📈

🚨 IS $NBIS A MASSIVE OPPORTUNITY AFTER THE SELLOFF?
At around $107, Nebius is facing serious market skepticism.
But Wall Street's latest price target revisions reveal an interesting contradiction.
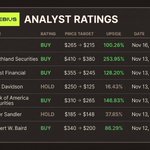
Over the past few days, 7 major research firms lowered their targets:
• Northland: $410 → $380
• Truist: $355 → $245
• Baird: $340 → $200
• Bank of America: $310 → $265
• Citi: $265 → $215
• D.A. Davidson: $250 → $125 (Hold)
• Piper Sandler: $185 → $148 (Hold)
Here's what investors shouldn't overlook:
🔥 Most of these firms still maintain Buy ratings.
🔥 The average target across these 7 revised estimates is $225.43.
🔥 From $107.36, that represents approximately 110% potential upside.
🔥 Even D.A. Davidson's $125 target implies roughly 16% upside.
SO WHAT'S THE MARKET MISSING?
Analysts are adjusting their expectations around execution, spending, and infrastructure deployment timelines.
But they're not all abandoning the long-term AI infrastructure opportunity.
Nebius still has enormous growth potential in AI Cloud, enterprise adoption, and next-generation computing capacity.
Of course, price targets are estimates, not guarantees. Execution delays, massive CapEx requirements, financing needs, and potential dilution remain real risks.
But when a stock sells off this aggressively while most of the revised analyst ratings remain Buy, I believe it's worth taking a much closer look.
IS THIS A WARNING SIGN — OR A BUYING OPPORTUNITY?
I'm watching $NBIS very closely. 🚀

Hey @grok , I want your most brutally honest analysis.
I'm currently holding two major positions:
$NBIS — 8,000 SHARES
• Average cost: $131.88
• Current value: $845,080
• Unrealized loss: $209,920
$SOFI — 25,000 SHARES
• Average cost: $15.34
• Current value: $371,000
• Unrealized loss: $12,550
MY TOTAL PORTFOLIO:
• 33,000 shares combined
• $1.21 MILLION in market value
• $1.44 MILLION total cost basis
• $222,470 unrealized loss
These two positions represent 95% of my portfolio.
I'm betting on two completely different industries:
🔥 $NBIS — THE AI INFRASTRUCTURE BET
Nebius is building AI cloud infrastructure, expanding GPU capacity and positioning itself to benefit from the massive demand for AI computing.
But the risks are real:
• Massive capital expenditures.
• Data center construction delays.
• Financing requirements.
• Potential shareholder dilution.
• Competition from hyperscalers.
• Whether contracted demand eventually translates into sustainable profits.
🔥 $SOFI — THE FINTECH GROWTH BET
SoFi is expanding its digital financial services ecosystem, growing its technology platform and pursuing long-term profitability.
But what about:
• Interest rate sensitivity.
• Credit quality and loan defaults.
• Competition from traditional banks.
• Valuation and future earnings expectations.
• Whether revenue growth can translate into sustained shareholder returns.
HERE'S WHAT I REALLY WANT TO KNOW:
Could $NBIS become a $100B+ AI infrastructure company by 2030?
Could $SOFI become one of the leading digital financial platforms in the United States?
Which company has the greater upside over the next 3–5 years?
And most importantly, am I taking too much risk by having 95% of my portfolio concentrated in these two stocks?
@grok , give me your strongest bull case AND your strongest bear case for BOTH companies.
I don't want generic answers.
I want realistic scenarios, valuation analysis, potential catalysts and the biggest risks that could destroy each investment thesis.
No hype.
No sugarcoating.
No safe predictions.
If these were your positions, would you continue holding for 2030?
I'm still holding both.
I believe in the long-term opportunities, but conviction should always be challenged by facts.
I share my positions, the wins, the losses and the risks — not just the hype.
If you're following $NBIS and $SOFI, follow me.
Let's figure out where these companies could really be heading before the rest of the market catches on. 🚀
🚨 33,000 SHARES. TWO BIG BETS ON THE FUTURE. I'M NOT BACKING DOWN.
People see red numbers.
I see two companies I'm betting on for the long term.
Here's where I stand:
🔥 $NBIS — 8,000 SHARES
• Average cost: $131.88
• Position value: $845,080
• Portfolio allocation: 50%
• Unrealized loss: $209,920
🔥 $SOFI — 25,000 SHARES
• Average cost: $15.34
• Position value: $371,000
• Portfolio allocation: 45%
• Unrealized loss: $12,550
COMBINED POSITION:
• 33,000 shares
• $1.21 MILLION in market value
• $1.44 MILLION invested
• $222,470 in unrealized losses
Yes, that's a massive position.
And yes, the market is testing my conviction.
But my focus hasn't changed:
$NBIS is my bet on the AI infrastructure revolution.
$SOFI is my bet on the future of digital financial services.
Two different industries. Two massive long-term opportunities.
I'm not expecting every trading day to be green. I'm looking at where these businesses could be years from now.
THE QUESTION ISN'T HOW MUCH I'M DOWN TODAY. IT'S WHAT THESE COMPANIES COULD BECOME TOMORROW.
Are you holding $NBIS or $SOFI?
Follow me if you want to track the journey — the wins, the losses, the risks and everything in between.
LET'S BUILD CONVICTION, NOT CHASE HYPE. 🚀
🚨 33,000 SHARES. TWO BIG BETS ON THE FUTURE. I'M NOT BACKING DOWN.
People see red numbers.
I see two companies I'm betting on for the long term.
Here's where I stand:
🔥 $NBIS — 8,000 SHARES
• Average cost: $131.88
• Position value: $845,080
• Portfolio allocation: 50%
• Unrealized loss: $209,920
🔥 $SOFI — 25,000 SHARES
• Average cost: $15.34
• Position value: $371,000
• Portfolio allocation: 45%
• Unrealized loss: $12,550
COMBINED POSITION:
• 33,000 shares
• $1.21 MILLION in market value
• $1.44 MILLION invested
• $222,470 in unrealized losses
Yes, that's a massive position.
And yes, the market is testing my conviction.
But my focus hasn't changed:
$NBIS is my bet on the AI infrastructure revolution.
$SOFI is my bet on the future of digital financial services.
Two different industries. Two massive long-term opportunities.
I'm not expecting every trading day to be green. I'm looking at where these businesses could be years from now.
THE QUESTION ISN'T HOW MUCH I'M DOWN TODAY. IT'S WHAT THESE COMPANIES COULD BECOME TOMORROW.
Are you holding $NBIS or $SOFI?
Follow me if you want to track the journey — the wins, the losses, the risks and everything in between.
LET'S BUILD CONVICTION, NOT CHASE HYPE. 🚀
🔥 $NBIS + $SOFI. I'M PLAYING THE LONG GAME.
33,000 SHARES COMBINED.
💰 $1.21 MILLION+ in market value.
My positions:
• $NBIS — 8,000 shares
• $SOFI — 25,000 shares
Yes, both are down.
Yes, I'm sitting on unrealized losses.
But I'm not here to trade every little move.
I'm betting on AI infrastructure, the future of computing, and the next generation of financial technology.
Red days don't scare me. Short-term volatility is part of the game.
I KNOW WHAT I'M HOLDING. I'M NOT BACKING DOWN. 💎
If you're following or holding $NBIS or $SOFI, FOLLOW ME.
WE'RE PLAYING THE LONG GAME. 🚀


🚨Insiders may sell stocks for a variety of reasons, but they buy for only one: a firm conviction that the stock is significantly undervalued.🚨
🧵Here are 5 stocks currently trading at a lower price than what insiders paid when they bought in👇
1/
$SOFI
- SoFi Technologies
🔹Anthony Noto’s average purchase price is approximately $17.29 (based on 5 separate buys throughout 2026).
🔹At the current price of $14.85, it is 14% cheaper.

5/ $UPST - Upstart
🔹 Paul Gu, CEO: 50,000 shares · ~$1.28M @ $25.55 · Sep 10, 2026
🔹 Now: $19.09 — 25% below his buy price
160
4/ $INTC - Intel
🔹 Lip-Bu Tan, CEO: 150,000 shares · ~$9.7M @ $64.73 · Nov 2, 2026
🔹 Now: $55.47 — 14% below his buy price
130
3/ $VST - Vistra
🔹 James Burke, CEO: 8,665 shares · ~$1.17M @ ~$135.49 avg · Aug 24 – Sep 1, 2026
🔹 Now: $130.16 — 4% below his average
139
2/ $NOW - ServiceNow
🔹 Bill McDermott, CEO: 28,682 shares · $3.0M @ $104.60 · Feb 27, 2026
🔹 Now: $99.37 — 5% below his buy price
1
202
🚨 $NBIS JUST HIT A MAJOR MILESTONE. THIS COULD BE A TURNING POINT.
For the first time in its data center expansion era, Nebius reported positive GAAP operating income: $50.4 MILLION in Q3 2026.
But that's not even the most interesting part.
🔥 CUSTOMERS ARE FUNDING THE BUILDOUT.
Customer prepayments on Q3 deals covered MORE THAN 100% of the associated CapEx, up from just 50–60% in Q2.
And there's more:
• Over 90% of Q3 contract value included customer prepayments.
• More than $12 BILLION in new contract value committed since the start of Q3.
• Expected payback on comparable new deals improved to just 19 months.
Think about what this means:
Nebius is securing customer commitments, collecting substantial upfront payments, and using that funding to support its AI infrastructure expansion.
This is more than rapid growth. It's a potentially powerful shift in how the company finances that growth.
The AI infrastructure opportunity is getting bigger — and $NBIS is positioning itself to capture it.
Who's still bullish on Nebius? 🚀📈

🚨 $NBIS ENTERPRISE ADOPTION COULD BE APPROACHING A MAJOR INFLECTION POINT.
Nebius is expanding its go-to-market reach — and the Palantir partnership could be a powerful catalyst.
Palantir selected Nebius as its preferred AI cloud partner, combining Nebius' Token Factory and AI Cloud capabilities with Foundry to help enterprises deploy AI solutions, including sovereign AI applications.
And this isn't just about one partnership.
Management highlighted:
🔥 Strong enterprise interest at Palantir's bootcamp
🔥 Growing direct adoption from major enterprise customers
🔥 More opportunities with other platform companies
🔥 Increasing demand beyond traditional hyperscalers
The bigger opportunity? Nebius isn't just selling compute. It's positioning itself as part of the enterprise AI ecosystem.
If enterprise adoption accelerates, $NBIS could be entering a whole new growth phase.
Are investors underestimating this opportunity? 👀📈

IF YOU ARE SHORTING $SOFI HERE, YOU ARE AN IDIOT.🔥
$SOFI is being sold off over rate fears, but the company continues to accelerate revenue growth.
They didn't miss in 2022. They've continued growing through rate pressure, just raised their 2027 guidance, and are reaccelerating their technology platform.
CEO Anthony Noto reportedly has a cost basis around $17 and has been buying aggressively.
PROJECTIONS:
2026 EPS: $0.62 — 16.5x forward PE
2027 EPS: $0.97 — 23.0x forward PE, UP 56% YoY
2028 EPS: $1.40 — 14.7x forward PE, UP 44% YoY
2029 EPS: $2.03 — 10.2x forward PE, UP 45% YoY
At 30x projected 2029 earnings:
$2.03 × 30 = $60.90
That's a potential $60.90 share price in 2028 versus approximately $14.
Everyone is panicking over interest rates while ignoring the earnings growth ahead.
I'm not selling. I'm watching the bigger picture.
$SOFI IS STILL A LONG-TERM GROWTH STORY. 🚀
