

Commercial real estate equity and debt capital advisor (deals $25M+). Los Angeles based. Founder Priority Capital Advisory. Boy dad x2. Lucky husband!
Los Angeles, CA
Joined March 2016
- Tweets2.5K
- Following2.7K
- Followers8.1K
- Likes15.9K




Everyone's waiting for the 10-year to bail out their deal.
GlobeSt asked me this week how sponsors are handling that. Short answer: the good ones stopped waiting, and the smartest ones went floating.
The WSJ's survey of 71 economists has the 10-year at 5.1% by year-end and 4.78% at the end of 2027. Pimco is openly talking about 6%. A 10-year near 5.25% isn't a blip. It's the baseline.
Here's what I told GlobeSt that gets lost in the rate chatter: credit markets are wide open and lenders are competing hard for quality deals.
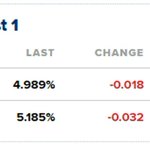
Where they're competing hardest is floating rate. SOFR is sitting at 3.89% against a 5-year Treasury at 4.99% and a 10-year at 5.19%. That's the index for floating more than a point inside the index for fixed, and it's why debt funds and banks are sharpening spreads to win bridge and construction business right now. Sponsors who move now are getting terms that weren't available 12 months ago. That's where we're closing the most business, and it's not close.
What else we're hearing from capital this month:
• Sizing is debt-service driven now, not LTV driven. The sponsors getting full proceeds are the ones who bring real in-place cash flow. Day-one coverage is the whole conversation.
• CMBS is the most aggressive fixed-rate execution on the board right now. Conduit shops are hungry, spreads are tight, and they're stretching on proceeds and structure in ways we haven't seen in a couple of years. If you need fixed and you need full leverage, that's the conversation.
• The bid-ask gap is still the problem on acquisitions. Buyers want 6 to 8% going in; sellers of stabilized product haven't moved enough. The deals getting done are the ones where the sponsor controls the NOI growth instead of hoping for cap rate compression.
• The maturity wall hasn't gone anywhere. The lenders competing today will be busier and pickier when it hits in full.
The takeaway? The cost of capital is what it is. The edge is knowing which lenders are leaning in, on what, and getting in front of them before the window narrows.


12 years ago I was an originator at Colony American Finance (CMBS and bridge loans on BTR). Some of you know it better now as CoreVest. Paul Fuhrman and Jae Yi were at Colony Capital, the parent company, and they had a lot to do with founding CAF and making it take off.
I was a lender. They were on the deal side. There was no business for us to do together. So we just stayed in touch.
A few firms later, including founding Priority Capital Advisory 2.5 years ago, we finally had a reason to work together.
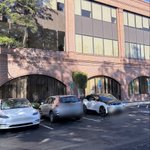
This summer we closed a $16.5MM permanent loan on their 99,300 SF office building in Santa Clara. Lender: Wells Fargo.
Read that again. A money-center bank. A permanent loan. Office. Bay Area. 2026.
Everyone on this app has an opinion about office. Lenders have money for the right building, the right basis and the right sponsor. Our job was to find the ones who still believed and make them compete.
The bigger lesson has nothing to do with office. Relationships in this business compound on a timeline most people quit on. Twelve years is not patience. It is the job.

LOAN
IMAGE: Paul Fuhrman, Zachary Streit & Jae Yi
DATE: 07/22/2026
ADDRESS: 2880 Lakeside Drive
MARKET: Santa Clara
ASSET TYPE: Office ~ SF: 99,300
LENDER: Wells Fargo
BORROWER: Paul Fuhrman & Jae Yi - Miramar Capital
BROKER: Zachary (Zack) Streit - Priority Capital Advisory
LOAN AMOUNT: $16,500,000
LOAN TYPE: Permanent Financing
#LosAngeles #RealEstate #tradedla #LA #LosAngelesRealEstate #California #LARealEstate #CaliRealEstate #TradedPartner #SantaClara #Office #ZacharyStreit #PriorityCapitalAdvisory #MiramarCapital #WellsFargo

Most lenders passed on this one. We closed it anyway.
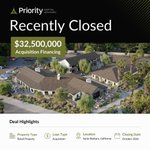
$32.5M in delayed purchase acquisition financing for a one-of-a-kind boutique retail property in Greater Santa Barbara.
No grocery anchor. No national credit tenancy. Specialty retail. The deal most capital sources screen out.
So we ran a real process:
83 lenders canvassed
12 quotes
3 finalists head-to-head
The winner sharpened its terms to take it
The result: non-recourse, interest-only, on terms that beat where most people think unanchored retail can price today.
Retail capital isn't gone. It's selective. Special real estate with a strong sponsor still draws aggressive debt. You just have to cover the whole market to find the lender who sees it.
That brings us to roughly $160M in retail financings over the last 12 months.
Got a retail maturity, refi, or acquisition coming up? DMs open.

Retail debt is the most competitive it's been in a couple of years and most owners haven't caught up to it.
My last 18 months: $150M closed or closing across five retail deals. 75 to 100 lenders on each. Up to 75% LTC on ground-up. As tight as SOFR + 150.
Banks, insurance companies, and debt funds are all back in and competing.
I'll be at ICSC@WESTERN in San Diego this coming Tuesday the 15th. Come find me.
Very excited for thus! Thanks for featuring me @moseskagan

Something strange is happening in the real estate private capital markets: Equity is mostly risk-off while lenders are mostly risk-on, the widest gap between the two that our speaker has seen in more than 20 years of brokerage. They can't both be right.
To give you a sense for how debt providers are thinking right now, we're hosting a dedicated Breakout at RC'26 with Zachary Streit, J.D. M.S.: "Debt Markets Off the Record: What's Actually Getting Financed in 2026."
Zack has 20 years of commercial real estate experience as an equity capital provider, a debt capital provider, and a capital advisor. In 2023, he founded Priority Capital Advisory, a boutique debt and equity advisory firm focused on deals with total capitalizations of $30 million to $200 million. He has closed $5 billion in commercial real estate financings over his career.
The session will cover:
- Equity vs. Debt: Why the two sides of the capital stack disagree so sharply right now, and which one Zack thinks is wrong
- The State of the Debt Markets: Spreads, leverage, and structure across bank, debt fund, CMBS, and agency executions, where we are in the cycle, and why it's all frothier than anyone admits
- What's Getting Done Right Now: Live examples across retail, office, industrial, multifamily, and hospitality, including deals most people assume are unfinanceable
- A Hot Take: Office is financeable again. Real, recent executions say the office debt market has reopened faster than the narrative suggests
- The Distress Wave That Came Sideways: Short sales, discounted payoffs, and lender-driven trades are happening quietly. Where the opportunity sits for buyers of this paper, and why lenders who just took losses are re-levering the same assets at par
Then Zack will hold open office hours: bring your deal, your maturity, or your term sheet, and he'll talk through it live.
As the title says, the session is totally off-the-record. That's the only way anyone in the capital markets can tell you what's really getting done, and at what terms.
If you would like to join a group of entrepreneurial real estate investors, operators and developers for a few days of off-the-record discussions about the future of the business (10/6-10/8 in Santa Monica), pls visit reconvene.com
Just closed a $13.65M bridge loan on a 33-unit student housing deal in LA. Still in lease-up.
Here's what the process taught me about this market:
We canvassed 100+ lenders. Most passed. Not because the deal was bad, but because unconventional product scares generalist credit committees.
The lenders who got it? They underwrote the demand story, not the label. 10K+ students within minutes. Needs-based demand. No new supply coming.
Student housing debt is inefficient right now. That's the opportunity. The spread between lenders who understand the asset class and lenders who don't is the widest I've seen.
Launch to close in ~8 weeks.
Working a student housing deal? DM me.
Everyone said construction lending was dead through 2025.
Our book says otherwise. 3 of our 8 closings this year are ground-up construction loans, including a $174M multifamily financing on the California Central Coast.
What changed: banks and debt funds that sat on their hands in 23 and 24 are now competing for well-sponsored deals. Spreads have tightened, leverage is creeping back up, and the lenders who moved early are winning the best sponsors.
The window for sponsors: if you have entitled land and a real basis, this is the best construction financing market since 2022. It won't stay this quiet for long.
$275M+ closed YTD across 8 deals. Multifamily, industrial, office, hospitality conversion, senior living. If you're penciling something, DM me.
Everyone says office is dead.
We just closed a $16.5M cash out refi on a Bay Area office building. Yes, cash out. Yes, office.
The wild part: the winning lender was a prior lender on this exact asset who lost money on it. We brought them back to the table and they won the deal again, this time handing our client cash out proceeds.
Same bank. Same building. Completely different story.
I've placed over $5B in my career and this is one of the best examples I've seen of a simple truth: lenders aren't avoiding office. They're avoiding bad basis.
We canvassed 101 lenders. Got 7 quotes. Ran 2 term sheets head to head. The winner sharpened terms twice to get it done. That's what real competition looks like when the basis is right.
Office isn't dead. Bad basis is.
Own quality office and think the debt markets are closed to you? My DMs are open.

Just added an analyst to the team, straight out of college. Here's why that's a market call, not a personnel note.
You don't add headcount into a dead market. You add it when the pipeline forces you to.
Right now we're running $250M across the desk. An $87M senior housing development in Austin. An industrial refi in LA that 90% of lenders won't touch. A $17.9M ground-up SFR construction deal in Eagle Rock with hair on it.
None of these are layups. All of them are moving.
The lenders are back. The bid-ask on rate is narrowing. And the sponsors who spent 2024-2025 sitting on their hands are calling again.
We're staffing up because the reps are coming fast. Day one, our new analyst was on live deal calls. That's the job.
If you've got a deal that needs a home, DMs are open.
A lender asked me this week what we're actually seeing and closing. Here's the honest answer.
It's tough out there. Too many brokers, too many banks, not enough deals. Anyone telling you otherwise is selling something.
And yet the deals get done if you grind for them.
Closed in the last few weeks:
$11.5M hotel-to-multifamily conversion, in lease up
$6.5M industrial acquisition
In application right now:
$21M ground-up multifamily construction
$16.5M office CMBS
$15M office DPO bridge
$13.5M multifamily bridge
$12M multifamily construction pref equity
Out in the market:
$35M multifamily construction
$32M retail bridge
$15M industrial bridge
$15M for-sale residential subdivision construction
$8M office acquisition
Roughly $180M in motion. Every major asset class, every capital type.
The read from the trenches: banks are back and winning development bids. Debt funds are hungriest for built, cash-flowing assets and reset-basis plays. If you're capitalizing a deal right now, that map matters more than any headline.
Busy, hunting for more, and hopefully larger. Got a deal that needs a creative capital solution? DMs open.

Just closed a $6.2MM acquisition loan on a small bay industrial property in LA County. Smallest deal we've done. One of the fastest.
53 days from engagement to close. 34 days from signed application to funding.
Here's what nobody tells you about sub-$10M deals: the process doesn't shrink with the check size. We still went to 78 lenders. Still pulled 5 real quotes. Still negotiated every point of structure.
And it was our second closing with the same lender in five days, across two completely different asset classes. That's what repeat execution actually looks like.
The bigger story is the asset. Small bay industrial in infill LA might be the most durable trade in CRE right now. Tenants everywhere, zero new supply, real rent growth. Nobody's building 44,000 SF multi-tenant product at $191/sf basis. You can only buy it.
If you've got a maturity coming due or an acquisition under contract, DMs are open.
Most debt advisors talk about relationships. I'll show you the number instead: 91 lenders canvassed on a single flex industrial assignment this year.
That's not a typo. Construction debt funds, regional banks, USDA and PACE platforms, institutional balance sheet lenders, all run through a live, competitive process to get a 130,000 SF, $20M development the strongest terms available, in a market with a population under 100,000.
Most lenders won't even look at a market that size. We got signed, underwritten term sheets anyway, from groups who'd never looked at a submarket like it before we put it in front of them.
This is the part of the business nobody posts about. Not the closing, the canvass. The unglamorous work of knowing which 91 lenders to call, in what order, with what story, to get a niche asset class real terms in a tightening credit market.
That's the job. Run the market like your own money's on the line, every time, regardless of asset class or market size.
If you're sitting on a deal you think is too complicated, too small, or too overlooked for a real process, that's usually exactly the deal where a real process matters most. DM me.
Welcome to Priority Capital Advisory, Matt Lorimer.
Matt joins as SVP, bringing sharp deal instincts and a builder's mentality to our debt and equity platform. He's already in the mix on live deals across the pipeline.
More firepower, more execution, more wins ahead for our clients.
Welcome to the team, Matt.

Just closed: $11.5M refinance on a 153-unit multifamily conversion in Madison, WI.
Used to be a Radisson. Converted to studios + 1BRs. Still working through lease-up.
We canvassed 118 lenders before landing on the right structure.
Hardest deals to finance right now are conversions without clean trailing financials. Most lenders want a finished story. We look for the ones still being written.
DM me if you've got one of these.

Just got back from Bandon Dunes with three clients. We flew up private from Van Nuys to celebrate a nearly $200M construction and land recap financing we closed for them back in January.
Some deals deserve a proper celebration. This was one of them.
Three days of links golf on the Oregon coast. Wind off the Pacific, firm fairways, and a deer casually grazing the fairway like it owned the place.
But here's the part that matters if you're in CRE.
When we closed this deal in January, everyone was still saying construction financing was dead. Banks had pulled back, spreads had blown out, sponsors were shelving projects.
We placed a dual-tranche structure with a regional bank leading and institutional capital behind it.
The market has only gotten better since. Banks are lending again on the right sponsorship and the right basis. Debt funds are competing hard for what banks won't take. Leverage is back to workable levels.
The deals are getting done. You just need someone who knows which doors to knock on and how hard to push.
That's the business. Certainty of execution first. Bandon Dunes second.
If you've got a construction deal or a recap that needs capital, my DMs are open.


Signed our sixth retail financing assignment in the last 12 months last week. $35M. And I keep hearing retail is dead.
Here's what I'm actually seeing from the capital markets seat.
Retail vacancy is sitting at historic lows. New construction is basically nonexistent, and hasn't been meaningful in a decade. Retailers are signing longer leases and fighting each other for high-traffic corners.
Meanwhile, lenders who wouldn't return a call on retail in 2020 are now competing for the paper. Banks, debt funds, life cos. The bid is real.
The numbers from our shop tell the story. PCA arranged and closed financing for $150M across six retail deals in 2025, including a $50M senior construction loan for a retail project in a major Southwestern Metro. Predevelopment money for retail. That sentence didn't exist three years ago.
GlobeSt named me one of its 2026 Influencers in Retail Real Estate this week, which I'm grateful for. But the real signal isn't the award. It's that the hardest financings to place five years ago are now getting multiple term sheets.
The asset class everyone left for dead has the best supply-demand setup in CRE. Quietly, it's been true for a while.
If you own retail and your maturity is coming up, or you're trying to buy and the debt math finally pencils, my DMs are open.
Zachary Streit retweeted

Literally everyone in the RE industry told them this would happen, and they still went ahead with it.

Just back from ICSC Las Vegas.
Retail is having a moment. $15B in Q1 transactions. Highest volume in 3 years. The energy on the floor matched the numbers.
Supply isn’t coming back. New retail construction down 37% in 2026. Owners with quality assets are sitting on improving fundamentals every quarter.
Deals getting done have one thing in common: creative structure. Lenders are active but selective. Clean story + realistic basis = you win.
Best conversations? Not at the booth. Dinner, the sportsbook, midnight in the lobby. That’s where it actually happens.
If you’re working a retail debt or equity placement, DM me.
PCA | Priority Capital Advisory


Multifamily construction debt is wide open. Nobody seems to know it.
Bank construction quotes on multifamily: low 200s over SOFR. Debt funds competing hard in the low-to-mid 300s at 80% LTC. These are real numbers from live deals.
We've closed $416M in multifamily construction financing over the past two years and are actively marketing 3 new deals totaling $75M.
The constraint isn't debt. It's equity.
Full breakdown in my @MHNonline piece. Link below.
multihousingnews.com/constru…
