

AI boom, chips & biotech . I love finding the story behind the numbers, questioning the hype, and sharing what I actually believe in. 🤍
New York, NY
Joined August 2010
- Tweets808
- Following160
- Followers2.5K
- Likes1.2K





Pinned Tweet
Look at the chart $TSLA just cleared that huge downtrend line to hit $391. The Barclays news generated a massive 52.8M volume spike at the bottom. But let’s be real before getting trapped by FOMO. This pump is heavily driven by SpaceX merger speculation. The fundamental math with Q3 capex doubling to $4.7B doesn't justify a triple-digit P/E yet. It looks visually bullish, but I'm holding back. Don't chase the institutional hype here.
$SPCX

Belmina Rose retweeted

It seems like $NVDA will now start picking winners.
Obviously $NBIS and $CRWV come to mind.
I honestly love it. Didn't like the idea that $NVDA would just artificially fund dozens of low quality shitcos every year.
The entire idea was to be less dependent on the hyperscalers.
But we now have $SPCX and $META joining the hyperscalers.
So with 7 big buyers and enterprises coming in, I think they might be quite happy and have achieved that goal.

Nvidia CFO Colette Kress on neoclouds:
“Neoclouds and frontier labs are seeing extraordinary demand for AI infrastructure, yet many are growing faster than their balance sheets and long-term credit profiles can support.”
Nvidia says securing land, power, and data center capacity has become the next critical phase of the AI buildout.
To address this, Nvidia is helping select neoclouds secure that infrastructure. Its commitments are conditional on customers obtaining financing and getting the compute capacity deployed and operational. Commitments can be reduced or eliminated if those conditions aren't met.
Under these arrangements, Nvidia earns revenue from upfront infrastructure sales and could also receive a share of the revenue neoclouds generate from third-party customers.

People are too focused on how far $NBIS has fallen from its highs and not enough on how much the business has actually improved.
In Q3, Nebius cut hardware payback from 22 months to 19 months, while customer prepayments on new deals now cover over 100% of CapEx upfront.
I get why investors are nervous. Jensen leaving NVIDIA shook the whole AI market, and nobody knows exactly what comes next. But market fear doesn't change the numbers. Nebius's unit economics keep getting stronger while sentiment keeps getting worse.

Everyone is turning bearish on $NBIS and other NeoClouds right now.
I won't.
Nothing changed from a fundamental perspective.
I believe we are at the end of this correction now, and will soon pump back towards new ATH's when people realize how cheap the stock currently is.
Most of the news reported over the last weeks have been positive, the market simply chose to focus on the few bad things.
My long-term PT stays at $560+ for the next major bull-cycle.

$NVDA continues to back independent AI clouds like NBIS and $CRWV when hyperscalers already spend hundreds of billions on GPUs.
Look Microsoft, Google, and Amazon are also building their own custom chips Maia, TPUs, and Trainium to reduce their reliance on NVIDIA over time.
Nebius doesn't build competing silicon. It builds pure-play AI infrastructure directly on NVIDIA’s stack, including Vera Rubin NVL72 racks and the new NVIDIA Vera CPU platform, backed by 4+ GW of contracted power. CoreWeave is also deploying Vera Rubin NVL72 racks and building on NVIDIA’s Vera CPU platform.
For NVIDIA, supporting independent operators like $NBIS and CRWV creates a dedicated distribution channel that doesn't try to replace its hardware. That strategic alignment is a big reason why I think NVIDIA’s partnership with Nebius is far stronger than the market gives it credit for.
Belmina Rose retweeted

$CRWV moved higher in premarket today after NVIDIA said on its earnings call that it will remain "disciplined and selective" when backing neoclouds.
Some investors treated selective support as a risk to CoreWeave, but I see it the other way around.
Being selective makes it harder for newer, unproven builders to get funded not the partnerNVDA already owns over 10% of and backs with a $6.3B capacity agreement.
CoreWeave’s own financing is also steadily improving, with its weighted average cost of debt down to 7.9% and new investment-grade contract facilities pricing around 7%–7.5%.
When $NVDA focuses its support on established operators with live power and existing contracts, CRWV gains a clear advantage over smaller rivals.
The key detail in $NVDA’s new 10-Q filing isn’t just the $32B in future commitments to neoclouds it’s the condition attached to them.
Those deals aren't blank checks. Operators have to arrange their own financing and get infrastructure online before NVIDIA’s commitments kick in, and NVIDIA also participates in rental revenue once clusters are live.
That puts $NBIS in a strong spot. Nebius already has $10B in committed customer prepayments, a $775M asset-backed facility at SOFR + 2.50%, and is scaling toward 1.2 GW of active power by year-end.
If NVIDIA is backing builders that can fund and deliver on their own, $NBIS is built to capture a large share of that $32B pipeline.
$NVDA just posted $115.8B in Q3 revenue (+103% YoY), $107.6B in Data Center (+110% YoY), and guided Q4 to $130B with Vera Rubin NVL72 adding nearly $20B in sequential revenue alone.
What stands out to me for $NBIS is that NVIDIA specifically named Nebius among the first cloud operators already running Vera Rubin NVL72 racks and building on the new NVIDIA Vera CPU platform alongside Microsoft, Google, Oracle, and CoreWeave.
Vera Rubin delivers up to 2x the performance per GPU of Blackwell Ultra. For Nebius, having next-gen racks live early means getting more compute and revenue out of the same data center footprint.
While investors have been selling $NBIS over fears that NVIDIA would pull back from neoclouds, tonight’s release shows Nebius is already executing on NVIDIA’s next hardware cycle.

Belmina Rose retweeted

BREAKING: The US Securities and Exchange Commission (SEC) has opened an investigation into Nvidia, $NVDA, amid the Jensen Huang situation, per WSJ.
The focus of the investigation includes whether the company’s disclosures misled investors.
The Justice Department is also now reportedly leading multiple investigations involving Alice Huang.
Belmina Rose retweeted

Over the past week, I’ve been overwhelmed by the love and support of friends, industry colleagues, and people I've never met. Thank you to everyone who has shown kindness to my family and me. It means the world to me.
I came to the United States 53 years ago, and becoming an American citizen is one of the greatest gifts and proudest moments of my life. NVIDIA has been my life’s work. Building it into the company it is today alongside my colleagues has been a privilege and an honor. Nowhere but in America could a company like NVIDIA be possible. I love our country, and I love NVIDIA.
I did not live up to the standards expected of everyone at NVIDIA, and I have made serious mistakes in my personal life. I created problems for the Board that I deeply regret. I own my mistakes completely, and I am committed to cooperating with the Board’s independent investigation.
Since my departure, I’ve seen an outpouring of calls from NVIDIA’s employees, investors, business partners, and customers for me to return as CEO. Many continue to reach out to me directly as the company navigates complex technology, market, competitive, and geopolitical dynamics. NVIDIA is a once-in-a-generation company. If the Board of Directors decides that my return is in the best interest of our shareholders, our employees, the company, and America, I would be honored to answer these calls and return as CEO.
Thank you again to everyone who has shared their good wishes. I am profoundly humbled by your support. To my family: I love you, and I will spend the rest of my life being worthy of yours.
Jensen
Citi cut its price target on $NBIS from $265 to $215 while actually raising its 2027 revenue estimate to $12.7B and lifting its CapEx forecast to $43.5B.
That tells me Wall Street isn't questioning AI demand anymore. It’s panicking over how much building that capacity costs upfront.
What the market seems to be ignoring is that Nebius isn't funding that CapEx on blind hope customers are already prepaying over 100% of CapEx on new deals, and $215 is still roughly 2x where the stock is trading today around $106. When analysts raise revenue estimates and cut targets at the same time, it usually means sentiment is way behind the business.

The biggest worry around neocloud stocks before tonights $NVDA earnings isn't chip demand its whether NVIDIAs new leadership pulls back on helping finance its cloud partners.
For the last two years NVIDIA has been investing in and backing cloud companies which then used that money to buy more NVIDIA GPUs. That helped build capacity fast, but it also made the market question how much of that demand can stand on its own. If NVIDIA tightens up on new deals or backstops, borrowing costs for $NBIS and $CRWV could stay high for longer.
Even so, I don't think that breaks the business. Companies like Microsoft and Meta still need huge amounts of compute for real AI workloads, NBIS rental rates are still going up +20% QoQ and live data centers with long term contracts aren't going anywhere.
Tonights numbers after the close will tell us if real customer demand is still driving this and probably decide whether the group bounces or keeps selling off.
Belmina Rose retweeted
A lot of people pushed back on my $CRWV post yesterday over debt, interest expense, and CapEx burn. Fair points interest and depreciation are real costs, and looking at Adjusted EBITDA alone isn't enough.
I think bears are getting wrong when they model CoreWeave like a failing company: they are dividing today's CapEx by today's revenue. In AI infrastructure, you spend capital today to bring $132.5B of contracted backlog online over the next several quarters scaling toward a $20B–$21B exit ARR by year end.
More importantly, roughly 92% of CoreWeave’s debt sits in contract-backed facilities priced around 7.9%, structured so that 4 to 5 year take or pay contracts pay off the hardware before the GPUs finish their useful life. That leaves 300,000+ GPUs rolling off debt-free in 2027–2028 to generate pure cash flow while $9B in customer prepayments arrives over the next three months.
Tonight’s $NVDA earnings will test whether hyperscaler GPU demand is actually slowing down. Debt and execution are real risks, but at a $27.4B market cap, I think the market is pricing in a bankruptcy scenario that the contract math doesn't support. I'm still bullish.

$CRWV is back under $50, putting the entire company at roughly a $27.4B market cap.
For that price, you're getting a business exiting 2026 at a $20B–$21B annualized revenue run rate (1.35x exit ARR), backed by a $132.5B backlog and 62% adjusted EBITDA margins.
On top of that, roughly $9B in customer prepayments and deposits are coming in over the next three months, while older GPU fleets are re-contracting above their original rates.
At $49.73, I think $CRWV is seriously undervalued given its growth and fundamentals. Anything under $50–$60 looks like a great buying opportunity. I'm holding and adding more.

Belmina Rose retweeted

Selling pressure has spread from tech into other sectors.
Consumer discretionary and energy are also clearly weak.
New highs and new lows are both made by money.
Support and resistance are always there to be broken.
Shows nothing is impossible in the market.
Before $NVDA reports I suggest mostly waiting and watching.
Dont blindly add inventory.

The detail most people missed in NBIS MLPerf results isn’t just that Vera Rubin trained 1.63x faster than Blackwell Ultra it’s how Nebius configured the rack.
Nebius ran on 64 GPUs (keeping 2 nodes as live hot spares just like a real customer cluster) and still beat every 72-GPU Vera Rubin submission in both pre-training and post-training.
You don't beat full racks with 11% fewer GPUs if you're just a commodity hardware landlord. That comes from cluster software and orchestration and cutting training times by 33–39% means Nebius can push far more billable work through every megawatt it owns.
The stock is trading like compute is a low-margin commodity, while $NBIS is quietly proving it has a real software and execution edge.

Our MLPerf® Training v6.1 results: 1st on @NVIDIA Vera Rubin at rack scale, in both pre-training and post-training. NVIDIA Vera Rubin NVL72 on Nebius trained up to 1.63x faster than NVIDIA Grace Blackwell Ultra NVL72 at matched scale. Plus updated Inference v6.1 results 👇
nebius.com/blog/posts/mlperf…


$NBIS is down nearly 8% today to around $107 ahead of tomorrow's $NVDA earnings, mainly on fears that NVIDIA might pull back on financing AI data centers.
I think the market is ignoring that Nebius doesn't rely on NVIDIA's balance sheet to build customer prepayments and financing already cover 75–85% of 2027 CapEx, backed by a $3.5B Citi facility and over $1B in active enterprise pipeline.
Until tomorrow's report shows actual GPU demand slowing down, selling NBIS around $107 over leadership headlines doesn't make sense to me.

Kris is comparing AI compute to the 2016 fracking bust, warning that falling GPU rental rates will break neocloud unit economics.
I think that comparison misses two things about $NBIS.
First, 2016 fracking flooded the market because anyone could drill fast AI compute supply is gated by multi year grid power, where Nebius already controls 4+ GW of contracted capacity. Second, fracking companies gambled on spot oil with debt, while Nebius is signing 1 to 5 year deals where customer prepayments cover over 100% of CapEx upfront and even without prepayments, hardware payback is down to 19 months as GPU hour rates rose 20%+ QoQ.
Even if rental prices eventually drop years from now, Nebius will already have recovered its hardware costs and will own scarce power capacity.

$NBIS $CRWV $IREN
This is a very good point. The strength of the Neo Cloud will be more important factor on whos left standing...
but also...
GPU rental prices. If GPU rental prices take a tumble over the next few years... a very real possibility given all the improvements from next gen chips and optimization improvements...
We could see rental rates comes down and then the Unit economics break.
I saw this first hand with Fracking in 2016... could happen again with AI compute.
People are debating whether $NBIS wins if Jensen returns or has to pivot to rival chips if he doesn't. I think both sides are missing the bigger shift already happening.
As AI chip competition heats up, value is inevitably shifting away from hardware margins toward inference and agentic applications. Nebius is already built for that shift without abandoning NVDA or worrying about who's sitting in the CEO chair.
NVIDIA already owns over 9% of Nebius through its $2B investment, with a 5GW+ deployment partnership through 2030. Nebius already has its first Vera Rubin systems live, is the first AI cloud deploying NVDA Groq 3 LPX for ultra-low-latency inference, and just grew Token Factory contract value 17x in Q3.
I respect everything Jensen built to make this ecosystem possible, but Nebius isn't just renting GPUs anymore. It's building a full-stack inference platform on top of locked-in infrastructure. However $NVDA leadership story plays out, NBIS is already positioned to capture the upside.
I have watched the exact same narrative flip across neocloud stocks all year without anything changing in the actual business.
$CRWV was written off over credit fears until one strong quarter made it a favorite again. $IREN was hated for dilution until its latest numbers suddenly turned its model into the sector blueprint. Now $NBIS is getting dumped over a temporary site delay, even though its $12–13B 2027 revenue target and 53% AI cloud margins haven't moved an inch.
Stock price action isn't the business. I think Neoclouds looks like the best buying opportunity in the market right now.
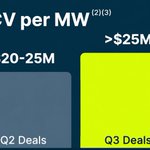
The real edge in $NBIS isn’t just that pricing is moving from $12/W-yr toward $25M $40M+/MW it is the gap between how fast Nebius recovers its hardware cost and how long those GPUs actually generate cash.
Nebius runs a 5 year useful life on its hardware, yet 1–3 year deals now pay back in just 19 months with customers prepaying over 100% of CapEx upfront on new wins.
That leaves over three full years where paid-off GPUs keep printing cash at 53% AI Cloud EBITDA margins while repricing higher every 1 to 3 years.
I think Wall Street is severely underestimating how much cash Nebius can generate from the exact same GPUs without buying new ones.

Compute pricing is becoming as much about contract duration as the chips themselves with 5-year deals across $IREN and $CRWV around $20–25 per watt-year versus $40–50 for short-term capacity and new $SPCX contracts above $50.
That spread creates an interesting opportunity for $NBIS whose 2026 base sits near $12 while newer short-term deals exceed $40 leaving room for realized pricing to rise as its contract mix shifts toward higher rates.
You can see the same dynamic within SpaceX where $ANT initial agreement priced near $30 while $GOOGL is paying $53–79 including H100s at more than 3x the rental index suggesting contract timing and guaranteed access are becoming just as important as the GPU itself.

Belmina Rose retweeted
$CRWV isn't struggling to find buyers.
They have 10x more qualified demand than available capacity through 2027, yet management is deliberately refusing to sell all of it today.
Why? 5-year contracts clear at $20–25M per MW, while short-term capacity is clearing above $40M per MW.
More than 130,000 GPUs roll off their initial contracts in 2027 and another 170,000 in 2028 completely paid off.
Re-contracting paid-off hardware into a $40M+/MW short-term market unlocks up to $4B in incremental annual revenue in 2027 and $10B by 2028 with zero new CapEx.
Holding back capacity to capture that duration spread isn't risky it's the sharpest capital allocation move in the sector.
