

An independent research and advisory firm that creates unbiased, enduring market shares and forecasts for emerging and transitioning high technology markets.
San Francisco Bay Area
Joined January 2011
- Tweets380
- Following283
- Followers256
- Likes190
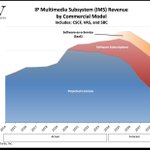



There has been a good deal of hype lately around #SaaS in the telecom space. While Software-as-a-Service (SaaS) commercial models are an increasingly popular way of consuming enterprise software and applications, this trend is just starting to impact operator core networks, especially in the packet core domain. In the voice domain, perpetual licenses continue to dominate voice and #IMS infrastructure revenues. In 2024, we estimate that nearly 80% of revenues were comprised of perpetual licenses. Network operators are very accustomed to these licenses, which are often depreciated along with the costs of the equipment, and are included and planned for in capital budgets (capex). Software subscriptions, which typically span between one and three years, have been rising in popularity. In 2024, we estimate that 17% of IMS revenues were derived from software subscriptions. Software subscriptions tend to work well for operators when they are deployed on top of third-party server hardware. That way customers can negotiate hardware and software costs separately and the software licenses are not necessarily tied to specific network hardware that is being depreciated.
Lastly, SaaS arrangements are beginning to rise in popularity but are not well suited to network functions that are located at the customer premises. Rather, SaaS arrangements are very well suited to network functions that are hosted in third-party clouds, like AWS, GCP, Azure, and OCS, where the software capacity can be better matched to the pay-as-you-go compute and storage arrangements. In this case, just as operators consume compute and storage by the amount of usage and other criteria, they can consume the network function capacity in the same manner. Thus lowering startup costs and reducing the need to purchase excess capacity for busy hour or disaster recovery use cases. We estimate that in 2024, 4% of IMS network function revenues were derived from SaaS arrangements. As the usage of third-party cloud providers increases, we expect that SaaS will account for 20% of network function in 2029, with the remainder being software-subscriptions (49%) and perpetual licenses (31%).
In other core segments, especially packet core, SaaS commercial models are gaining traction in fixed wireless access (FWA), Internet-of-things (IoT) and disaster recovery use cases. In these instances, there is a need to minimize redundant capacity in the form of excess licenses, and to be able to accommodate large, often unpredictable, swings in network connections and network traffic. These networks are often overlays or complements to the primary core network as a way to economically add capacity in relatively low-risk use cases.
What has been your experience?
@ExactVentures has the most accurate and comprehensive market data, forecasts, and analysis covering telecommunications core networks. Please reach out to learn more about how we can help you best compete today and in the future.
@ghcollins

Voice network infrastructure has lagged other parts of the mobile network in terms of its transition to cloud-native network functions creating a strong near term opportunity as operators catch up their investment in this network domain.
In 2024, cloud-native network functions (CNFs) accounted for just 13% of total IMS network function revenue with virtual network function (VNF) revenues and physical network function (PNF) revenues, accounting for 62% and 25%, respectively. Other areas of the network core (like packet core and policy) have been transitioning more rapidly to CNFs than have voice-related network functions. We believe this is due to several factors. First, voice is a low growth area thus operators and vendors would prioritize modernizing high growth products. Second, many operators struggle to get the needed reliability and latency with their cloud-native environments in order keep their voice KPIs within an acceptable range, hence the continued reliance on VMs, despite the processing and cost overhead.
Nevertheless, we expect that in the coming years, this will shift dramatically as operators urgently transition their network to take advantage of cloud economics and the scalability and automation that cloud-native network functions enable. This shift has created strong opportunity for vendors like @Ribboncomm, @Oraclecomms, @Ericsson, @Nokia, @Mavenir, @Alianza_Inc, and others.
@Exactventures has the most accurate and comprehensive market data, forecasts, and analysis covering telecommunications core networks. Please reach out to learn more about how we can help you compete best today and in the future.

While #6G talk is starting to accelerate, there are still plenty of important transitions happening in the #5G Core space. First, many operators are still using legacy Evolved Packet Core (EPC) networks to support 5G access through a Non-standalone (NSA) core network topology. In 1Q25, the 5G Standalone (SA) Core market accounting for half of the total market, while the 5G NSA market accounted for 36 percent of sales. Much of the progress in the 5G SA Core market has been generated by China, which has accounted for 48 percent of the 5G SA market over the past four quarters.
Second, and related to the first transition, is the transition to a pure cloud-native core network infrastructure. This infrastructure will enable many of the 5G use cases and functionality needed to grow revenues plus the ability to greatly automate the operations and security of the network. Nearly every vendor claims that their core network sales are "cloud native" but upon closer examination many of the so-called cloud deployments are on virtual machines (VMs).
Successfully making these transitions is of vital importance in laying the foundation for implementing both AI and 6G in mobile networks.
Progress is happening in the packet core market, but it has been slow. As AI takes hold and work around 6G standards begins to ramp, we expect that these shifts will begin to occur with more urgency in more operators around the world.
@ExactVentures has extensive analysis and analytics of the wireless markets. Please reach out with any questions or clarifications.

Earlier today, in an online session for industry analysts, @Nokia issued an update on its progress with 5G Core and outlined some its key near term initiatives. Here are some highlights and analysis:
First, the company reported 36% year-over-year growth in the number of 5G SA Core Network deployments, from 92 in July 2024 to 125 presently. Less than half of these deployments (53) are currently live, which underlines one of the important issues with the mobile industry: operators have been slow to deploy 5G SA, especially in very busy, demanding smartphone-based networks. 5G SA has achieved more traction in the less challenging FWA, IoT, and Enterprise markets.
Of course, deployments are not a great measure of market share. Nevertheless, Nokia has been growing faster than the market. As of 1Q25 Nokia was the #3 vendor with 12% of the market for 5G SA (AMF, SMF, UPF only) on a four-quarter rolling revenue basis, up from 10% in 1Q24. Nokia holds 22% of the market on the same basis if you do not included China, up from 17% at the end of 1Q24. 2Q25 market share figures will be out next month.
In terms of technology initiatives, Nokia highlighted the need for network automation and their recently announced Autonomous Network Fabric (ANF) which is a cross-domain, pervasive data fabric that will help enable true automation. The company also highlighted its Cloud Native Communications Suite (CNCS), a simplified voice architecture with Nokia IMS as a single CNF. Nokia is the market leader for IMS with nearly 40% of the market on a four-quarter rolling revenue basis. This market has been slow to move from VNF to CNF and this solution will likely help accelerate the shift.
The company is also advocating the use of AI to increase automation and to become more efficient and to reduce the human lift (effort) via:
•AI Agents power core network CNF lifecycles
•AI agents for proactive defense (security)
Closer cooperation with cloud provider (AWS, GCP, OCS, Azure) to get the scale and economics is needed to implement the agentic AI solutions. AWS’s recently announced Amazon S3 Vectors is a good example of a new solution that will help telecoms deal with the massive amount of session and transaction data needed to support the AI models.
Please reach out for more details, clarifications, and feedback.
#NokiaCore #5G #Nokia #ExactVentures
@Nokia @ExactVentures @ghcollins @aws

NEW VIDEO
Check out some of our predictions for 2024. Topics include: #5G, #5GCore, Telecom AI, APIs, and Signaling nextgeninfra.io/2024-predict…

ALT https://nextgeninfra.io/2024-predictions-showcase/?spotlight=exact-greg


#MavenirAnalystEvent @Mavenir. Many operators are turning to core network automation, openness, and programmability (2/2)
Great morning so far in Dallas at #MavenirAnalystEvent. @Mavenir positioned to navigate the current lull in the RAN market with larger/T1 O-RAN opportunities arising in 2025. Innovation and better economics are key for T1s to advance out of the current stasis (1/2)
Check out our latest thoughts and analysis on the outlook for core networks for the remainder of 2023 and beyond. exactventures.com/core-netwo… #5G, #5GStandalone, #5GCore
@nokianetworks @EricssonNetwork

Greg Collins discusses the potential, current barriers to adoption, and the importance of the #5G and LTE private networking market for operator business models and to justify the steep investment in #5GStandalone
youtube.com/watch?v=lmnIS6Lf…


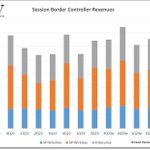
Check out some of our latest research. This time on the Session Border Controller Market. A key workhorse network function for both service provider and enterprise voice networks. exactventures.com/2q23-sbc-m…

Really cool! How Vodafone supplied the most mobile data ever to Glastonbury Festival 2023 techhq.com/2023/07/how-did-v…

More recent #5G Core market analysis from Exact Ventures: 5G Policy Control Function (#PCF) captures 44% of the total market for policy network functions in 1Q23. @Huawei leads @nokianetworks and @EricssonNetwork in increasingly bifurcated markets.
exactventures.com/5g-policy-…

Check out the latest news from Exact Ventures. 1Q23 Market Share Reports were issued recently. View some of the highlights on ther 5G Core, Policy, Signaling and IMS markets here: exactventures.com/news/ #5g #VoLTE #5gcore @EricssonNetwork @nokiaCloud @Huawei @OracleComms
Important move for #5G vendor diversity and long-term industry innovation. @Mavenir Raises $100 Million of Capital to Accelerate Investments in Strategic Growth Products mavenir.com/press-releases/m…


Nokia rebranding at #MWC23 as a B2B tech innovation leader. To enable the coming industrial & enterprise #metaverse will help to offset a basically flat CSP market. @nokia
