
United States
Joined June 2019
- Tweets2.1K
- Following1.5K
- Followers13.6K
- Likes20.4K


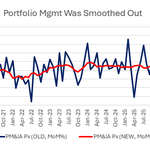
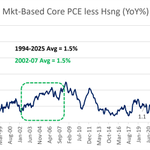



Core PCE looks strong. Set aside imputed px, like recently neutered portfolio mgmt & lags from hsng. The YoY mkt-based core PCE at an estimated 3.2% in Sep would be the highest since mid-1992 (ex-covid), & mkt-based core ex-hsng at 3.1% the highest since at least 1994.

I guess the Fed staff did not have a lot more info than we did on the BEA's revisions as they had it at 3.2% as well.


Aug survey week this year fell 4 weeks after July. In 2025, it was 5 weeks. The factors will necessarily be quite different. A proper comparison would be to Aug 2023.

AUGUST JOBS STRENGTH MAY HAVE BEEN OVERSTATED
August payroll growth of 162K was boosted by unusually favorable seasonal adjustments.
On an unadjusted basis, the economy added just 154K jobs, near 2025 levels. Using last year’s seasonal factor, August payroll growth would have been only around 15K.
The distortion suggests August’s headline strength may be a weak benchmark for September, reinforcing the need to focus on underlying payroll trends.

The downward surprise in the core PCE today (3% vs 3.2%-3.3% exp) is due to 1 previously unknown element of the revisions: the BEA decided to smooth the port mgmt series. That sharply cut the YoY rate for that series from Apr-Jul, leading to a larger cut in the YoY core. (1/3)
The stdev of the MoM% chg in PM over the revision period went from 2.9% to 0.9%. The smoothing attenuates periods of strength. As of Mar26, the old & new YoY rates for PM were close (old 10.4% vs new 9.1%). From there, the smoothing sharply cut the rate from 21% to 8.6%. (2/3)

Core PCE is 3% at a 3m SAAR thru Jul. What happens to 3m when you get Sep data and Jun is your base? Hint, it will jump for core CPI and will prob stay around 3% for core PCE. Not sure why everyone is leaning on 3m when you know Sep will be payback for the abnormal Jun print.

Kevin Hassett questions why the Fed is raising rates, says it is due to an “unusually partisan Fed” and says the “market is worried, too,” about a Fed that is going to be “hiking unwisely”:
“When I'm thinking about what future inflation is, then I look at the last three months of core.... When you annualize it, you know what the number is? 2%.... Right now I think that markets believe in future Fed credibility, but I think the argument that I would make if I were a governor is that if core is 2%, then why are we hiking?”
“The other thing about the Fed, and you know how long I've been close friends with Kevin Warsh…, he's managing an unusually partisan Fed. That is a hard thing to do, but it can start with [Michael] Barr and Jay [Powell] not resigning. If you go back to 1913, when chairmen, when their term is up, they leave. The same has been true for vice chairs… So why are they sticking around if not to worry about what the future Fed is going to do?”
“Geez, it seems like right now the data are saying we are heading in this forward direction and the Fed goes in the other direction, I'm worried about why they did that. I think the market is worried too because if you look today, then a lot of the people who weren't appointed by President Trump are giving speeches over the last couple of days saying we need a lot more hikes. And if they are going to be in control for two or three years, so if the short-term rate goes to 6% because they are hiking unwisely and then they keep it there for two or three years, the two-year rate, because of arbitrage conditions, it's going to be that. And so I think there is still some work to do to restore Fed independence. And I know that that is something that is high on the priority list for Kevin.”
Source: Financial Markets Quality Conference at Georgetown's Psaros Center on 9/23: c-span.org/program/public-af…

Leave out the biggest part of the upcoming BEA revision (port mgmt) & strip out all imputed prices, then look at the market-based core PCE less-hsng. Inflation has not been slowing as some have suggested, and there's quite a bit of wood to chop in 2027.

Omair Sharif retweeted

I don't think he meant it, but it implies a higher neutral rate than the one in the dots...
Interesting that the SEP seemingly did not incorporate the BEA's revisions, but Warsh noted that core PCE looks like it will be 3.2%. Under the old methodology, it was tracking at 3.4% in Aug, so seems like the Board staff's est of the BEA's revisions is about -20bps.
I get the sentiment & get the wireless issue, but one can make a credible case to hike by noting that 7/8 core PCE prints this yr have been *at least* 0.25% (incl prob Aug), or 3% annz. The case has been building steadily all yr. They just locked themselves in w/ recent rhetoric.


“Only raised” to 0.26%. There has been just one reading all year below 0.25%, so 7/8 prints this will be 3% annualized or more. Even under the new methodology, YoY core will be north of 3% (I have 3.3% but 3.1%-3.3% all plausible depending on how one models port mgmt).

Goldman throws in towel on no rate hikes:
"We now expect a 25bp hike at the September FOMC meeting next week (vs. a hold previously). Additional hikes at later meetings are possible but are not our baseline. While today’s CPI report only raised our August core PCE forecast slightly to 0.26% and has not changed our fundamental inflation view, we think that the FOMC will want to avoid the market reaction that would likely follow from remaining on hold when the market is pricing a nearly 90% chance of a hike."
Airfares have been on a tear all yr, in part due to jet fuel. This rise was not surprising. And if you look at hotels, this increase was coming given how it is constructed + severe weakness the last 2m. I would not hand wave that away even if they are volatile.
BofA on CPI: "Beyond its implications for next week's Fed decision, we do not view the CPI report as particularly informative about the underlying inflation trend. The upside surprise was driven largely by core services, which increased 0.33% m/m. Within core services, wireless telephone services surged 5.9% m/m, contributing roughly 10bp to core CPI. The increase likely reflects AT&T's retirement of certain unlimited plans and higher administrative fees, which should prove to be a one-off. In addition, airfares and lodging away from home, two historically volatile categories, contributed a combined 8bp to core CPI. Airfares in particular may have been boosted by higher oil prices. These effects should prove temporary and largely unwind over coming months."
The core CPI was 0.29%, firmer than my 0.27% fcast. Yes, a record jump in wireless added 10bps after it cut -5.5bps in Jun. The median was 0.17% &the 16% trimmed mean was 0.24%. This should push most to around a 0.24%-0.26% core PCE fcast. For the Fed, time to put up or shut up.