





#ENQ Understand the investment case here following the deal announcement today, but the market wouldn't have liked selling core asset before the pending acquisition is complete. The risk is being left without a core asset if that falls through. All other things being equal there is value for holders.
1
16
1,887
#AVAP cancelled all treasury shares 10 days before 4.2m bondholder (in the money) warrants expire? 🤔

3
888
Shockingly low valuation. Maybe existing holders taking advantage of a foreced seller. Regardless, doesn't look good for #CHRY
news.sky.com/story/starling-…

2
1,137
OB>2Ps
#AVAP


6
1,176
#AVAP Tangible NAV (excl. Purchase options) now c234p. Each ATR on order valued at c$3.1m on the books (conservative, sold a couple for $5m cash profit each last year). Share buybacks will be further value accretive, bonds also trade at a discount so further capital optimistaion opportunities there.
The debt modification gain amortisation is gone now, so would easily make 30c in EPS next year and more each year after that. NAV will continue to increase. Shares at 140p a bargain. 5 new ATR deliveries to take in the next 12 months (if ATR can keep up with supply). Potential to sell one of two on delivery (like last year?) I don't see many issues here. Air Baltic bankruptcy a non-issue imo. A very well run company with some great personnel additions in the last year. Will only keep getting better.
2
6
1,378
I hear a lot that they are a bargain but have been for years etc etc. Yes but so was #AEP when it didn't do anything for years and I got similar arguments about it at 700p. Its up 200% since. I look for the best risk/reward. I worry about risk too much, that's why need Asset backed equities. Anyway, we shall see.
1
430

Affan retweeted

[🔵Press release] Goa-based start-up @fly91_IN placed an order for 40 ATR 72-600 aircraft – the largest ATR firm order in almost a decade, and the largest ever by a regional airline. ATR’s order intake for 2026 lifts to 54 aircraft, above that of the whole year of 2025.
FLY91 plans to take its ATR fleet from 6 to 60 aircraft in the next five years, opening up new possibilities for regional connectivity across India’s Tier 2 and Tier 3 cities.
India’s regional connectivity needs an aircraft that can bridge communities reliably, viably, and responsively. That is what FLY91 and ATR will provide in the coming years.
Read the full story: atrnews.info/fly91-places-hi…

reuters.com/world/india/indi…
Has to be ATR's largest order ever? From a regional airline that was established just over 2 years ago. Keeps ATR busy and looking good for #AVAP orderbook and options. ATR still producing about 32-35 p.a.

9
1,152
#AVAP another 245000 shares (0.4% of share capital) bought at a >50% discount to NAV. Long it may continue. Get it down to 50m outstanding shares over 2 years @AVATION_PLC . No one has bothered calculatinf future EPS and FCF per share based on that. I am loving this. Well done Jeff! Keep it going.
Lionel Messi announced his retirement in 2016 after losing 4 finals with Argentina national team and missing a penalty in the Copa America final. He took it back ofcourse and the rest is history.
I don't know if there is a better story that could be used to teach self belief, grit, resilience and perseverance.
This is just truly remarkable. He used to be a part of Addidas "Impossible is nothing" adverts and the guy has literally proven it.
3
1,438
#AVAP This summarises exactly my thoughts and rationale for holding despite lack of share price movement. I believe that management is creating even more value here for shareholders and execution has been excellent. Whilst I have had no short term reward I am confident I will have the last laugh.
DYOR

A quick update on $AVAP.L Avation PLC with recent leasing news and ongoing share buybacks. open.substack.com/pub/andrew…

5
1,848
#AVAP Trading Update
- Trading in line with expectations
-Management observing further increases in valuation and lease rates
-Demand/Supply constraints pushing values up
-Cash still $105m (from half year) despite spending over $5m in buybacks, $2m in buying back bonds, taking delivery of one ATR 72-600 (mainly because of insurance proceeds of the Baltic A220?)
-Bought back over 8m shares (13%) in the last 12 months
-No comment on non-trading items i.e. Purchase rights valuation etc and no indication of net debt although state that they have repaid $130m of secured debt in the last 12 months, I believe a lot of that is for the sold B777 and Baltic A220, regardless a very impressive stat.
-Bottom line, over 50% discount to NAV, 3 more new ATR deliveries in the next 6 months, will still be left with an order book of 10 and 19 purchase rights. All indicators pointing to further increase in valuation. NAV is undercooked. With a market cap of only c$105m and assets worth $1bn, slight increases in valuation can have a material impact on NAV per share. NAV might be c280p but fair value/breakup value could be way in excess of that. SP 135p.
16
1,370
#AVAP They have also bought back $2m of unsecured bonds since start of the year. Both $1m tranches bought at a discount, the second $1m might have been bought at c7-10% less than par depending on when they bought it. The bonds still trade sub par (95c). I reckon, just the bond buybacks would result in an over $100k instant profit and lowers finance costs by $170k p.a. going forward.
Buying back shares, buying back bonds at discount, buying new ATRs as they are delivered from the order book. Excellent capital management.

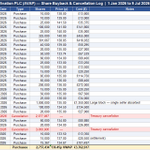
#AVAP Updated buyback table (from 1 Jan 26 to date) Thanks to Claude. Voting shares reduced by 4.5% just this year, c22% over last 20 months, all at c50% discount to NAV.
Obv, nothing to see here.

1
8
1,439