

Believer. husband 2 @jennshamm, dad, advisor, investor, and super lucky guy
San Francisco
Joined August 2008
- Tweets708
- Following565
- Followers363
- Likes653





Geoff Hamm retweeted

The biggest issue with $APP is that no one truly understands the business, and you have all these moron analysts on X thinking that they do, tricking people. The morons own the conversation and Adam seems ok with that (im sure his team isn't - it's embarrassing for them).
@AppLovin needs to hire a real Head of IR and set the damn story straight about the business. It is laughable they let these clowns drive and own the narrative about who they are and what they do.
It's a fantastic business yet they have non-existing IR.

If $APP does what analysts currently expect this year:
2026 EPS: $15.76 l Current price: $271
That puts AppLovin at roughly 17.3x 2026 earnings. 17x!
For a company analysts expect to grow EPS to:
2027: $20.10
2028: $25.37
2030: $29.78
At today’s price, that's roughly:
2026: 17.3x earnings
2027: 13.6x
2028: 10.8x
If AppLovin keeps executing anywhere close to these expectations, 17x is laughable, friends. This is exactly why I’m buying the fear.

Geoff Hamm retweeted

JUST IN: Citi reiterates "Buy" on AppLovin $APP with a $600 price target as e-commerce adoption accelerates
Geoff Hamm retweeted

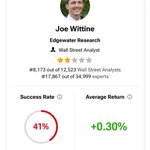
$APP Here’s what Muse says: Joe Wittine is an analyst at Edgewater Research, a boutique research firm (not a bulge-bracket bank). He covers Communication Services — mostly ad-tech: AppLovin, Unity, The Trade Desk, and Meta. No background bio surfaced in my searches, and there's no evidence of any Institutional Investor All-America ranking or other marquee analyst award.
His stature/ranking
• On analyst leaderboards he sits near the bottom, not the top: #3,481 out of 4,651 analysts on StockAnalysis (58 ratings, 41.2% success rate, 0.5% average return), and TipRanks shows 14 of 34 recent ratings profitable with a +0.10% average return.
• In short: a small-firm ad-tech specialist with a thin, middling-at-best track record — not someone whose calls historically move the needle on a name this size.
Early 2025 he said same thing: he cut estimates on both APP and Unity, arguing the mobile gaming macro "seems to be decelerating slowly" while Meta and Alphabet competition was rising. His take then: AppLovin's user acquisition and impression share were stable at industry-leading levels but no longer "rapidly expanding," and its e-commerce momentum was normalizing.
. .
Geoff Hamm retweeted
JUST IN: AppLovin $APP e-commerce clients rise 5.1% week over week to 13,105
Geoff Hamm retweeted

The analyst behind AppLovin drop… $APP


Edgewater says AppLovin $APP is entering a “show-me” phase as growth normalizes.
The firm says MAX is nearing a functional ceiling, market share growth is less consistent, and “competition is impacting APP’s net spreads at the margin.”
4Q26/2027 estimates are moving lower.

Geoff Hamm retweeted

Polymarket & @splashsports are launching the biggest survivor contest in history with $21,000,000 guaranteed.
Make your picks each week & the last person standing wins the biggest prize this format has ever seen.
Skip the flight to Vegas and play from you couch all season long.

Geoff Hamm retweeted

The recent 20VC interview with Adam Foroughi is an incredible example of capital allocation and lean operations. $APP is operating in a league of its own right now. We are talking about a business that generated $5.48B in 2025 revenue and is currently doing roughly $10 M in EBITDA per employee. They operate with a total headcount of around 895 people, but the core advertising unit that prints the cash is only about ~400 people. You never see software companies at a $150 B market cap running this lean. The 84% EBITDA margin profile is completely disconnected from traditional enterprise SaaS norms.
The competitive moat is their recommendation engine, AXON 2.0. The advertising environment is brutal. $META and TikTok have elite targeting engines. TikTok’s algorithm is famous for engagement without a social graph. But AppLovin has built an engine that processes over 2M ad auctions per second, optimizing heavily for performance and incrementality. When the stock completely collapsed by 92% in 2022 management did not panic. Instead, they ruthlessly threw out their old ML infrastructure and rebuilt AXON from the ground up. They ignored the noise, shut down investor relations temporarily to focus internally, and executed one of the highest ROI buybacks in modern corporate history. They targeted private market VC sellers who were desperate for liquidity. That specific buyback maneuver alone accounts for roughly $50 BILLION of the company's current market value.
Their internal culture is intensely anti-bloat. They have zero traditional management layers. There is no CRO, no COO, no CMO, and no Chief Human Resources Officer. Foroughi cut HR from roughly 80 people down to 15. The product team does not exist. Engineers are required to act as product managers. If an engineer cannot understand the business KPIs that drive revenue, they do not belong there. AI enables them to eliminate process-heavy roles. They demand that only their top 10% to 15% of employees take equity risk, while everyone else gets cash compensation. This keeps their SBC tightly capped at around $300 M annually. For a company valued at over $150 B, that dilution rate is almost a rounding error. Foroughi values the business strictly on cash flow minus SBC. It is the absolute cleanest metric.
The bearish narrative assumes AI makes game and app creation easier, which somehow dilutes the value of AppLovin's ecosystem. Foroughi counters that cheaper content creation actually explodes the volume of content, making discovery engines like AXON infinitely more valuable. If they expand this performance-based advertising model into connected TV and the broader $170 B e-commerce sector via their Axon Ads Manager, the path to a trillion-dollar valuation becomes very achievable without even needing to build a native social network. Great interview! Really appreciate hearing Adam.
Geoff Hamm retweeted
I have interviewed 1,000 CEOs of the largest companies over the last 10 years.
Adam Foroughi is top 5 I have ever met. Easily.
AppLovin Market Cap: $160BN
Revenue: $5.48BN
EBITDA per Head: $10M
There is no company on the planet with numbers like AppLovin.
Episode coming 👇

Geoff Hamm retweeted
Why is $APP beaten-up as a high beta software company even though its biz is an AI winner? Some of this fault lies with history (it did own software once) and some with the market's struggle with $APP's business model. Investors who can look past recent performance challenges will see an incredibly strong biz model (see rating vs. software below) that will thrive with AI. $APP's rev per employee at almost 4x palantir confirms this point (see data below). With continued execution, $APP will rerate to an $AI winner over the course of 2026 and will trade at $750-$1,000/sh - a price supported by its peer multiples and $APPs growth and cash flows.


.@united what the heck did you do to your website and purchase path??? It's terrible - you had a very easy purchase path and you made it worse??
2
77
Geoff Hamm retweeted

It's here! This is one of the biggest Masters Guarantees you'll find ($350K), with a massive first prize ($100K) PLUS the chance to win an all-expense paid trip to play golf with John Daly and I.
How insane is that?
Play now: bit.ly/4lj9t3x

Geoff Hamm retweeted

New from our CEO, Adam: A full breakdown of our business model, its merits, and our approach to data. Read it here: applovin.com/blog/how-we-dri…
For a deeper technical dive, check out our CTO, Basil's blog here: 👇applovin.com/blog/examinatio…
Geoff Hamm retweeted

$APP Responding to these two short reports—actually, we analyzed these issues several months ago. The two key points were that Applovin is accused of exfiltrating META data and that Applovin is engaging in backend direct download activities.
Regarding the data exfiltration claim, Applovin has already issued a response.
AppLovin: Two short seller reports from Fuzzy Panda and Culper. Notes it has been told AppLovin stealing data from Meta in their e-commerce push. WFC analyst said he spoke to APP, they fully refuted META point, said they have an agreement with meta and Meta can audit them whenever they want.
Based on my previous research, Applovin offers a streamlined SDK that facilitates advertisers in transmitting data back; because the data belongs to the advertisers, META really has no means to block it.
As for backend downloads, almost all smartphone OEM use this approach, and Applovin is a client of these OEMs. Your app has undoubtedly been directly downloaded from other OEM as well. If there's a problem, then the responsibility should lie with the OEMs to ban this ad service.
.@BottleRockNapa your ticket experience sucks badly. You can't allow someone to put tickets in their cart and then not check out - lame
2
52
@GStephanopoulos your interview with the director of FEMA is in direct contradiction to this
2
58
.@ucdavis I hope your administration does something about this! instagram.com/p/C7nOvzgSazJ/…
4
96
Way to go .@GavinNewsom - your absurd 25% minimum wage increase is causing the loss of jobs in California wsj.com/business/hospitality…

2
88