

I know very little and like to learn in public. DMs open.
Berlin, Germany
Joined October 2010
- Tweets4.1K
- Following340
- Followers5.8K
- Likes22.2K






$TYL continues steadily growing its sticky cloud subscriptions
repurchased 8.5% of shares YTD


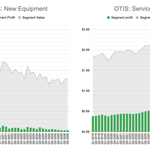
$OTIS grew service sales via low-margin modernizations
Modernizations (like new equipments) should lead to high-margin maintenance & repair contracts in the future

$OTIS core business of maintenance & repairs remains lackluster and plagued with customer satisfaction issues.
Management appears evasive and uninspiring. Definitely, the company with the lowest quality "culture" in my core portfolio...

A few thoughts on $EVO's Q3 2026
Good news and bad. And, lastly, 3 ugly takes:
1. Regulated markets are riskier than unregulated ones
2. Asia is a market share story
3. Good games are not enough anymore


$EVO bear case in one image
"Ice Fishing is probably the largest game in online history, and it's the third time Evolution created such a great game." – CEO Carlesund


GOOD
- North America, Latam & Africa: double-digit growth
- RNG: double-digit growth beyond bounds
BAD
- Asia & Europe
- Brazil: accounts for "well below half of LatAm" → a €20m/q impact could reverse ALL of $EVO's YoY global growth
- Lower margins (even adjusted for one-offs)


My areas of interest at tomorrow's $EVO Q3 results:
SALES
- Live: growth vs decline, game shows vs table games
- CT & Ice Fishing: cannibalization vs net growth
- RNG: further growth
- Asia & Europe: managed stagnation
- North America: double-digit USD growth
- Latam: prospects

OPERATIONS
- Headcount: ex-Americas studio downsizing
- Release schedule of Hasbro games in the US
- Brazil: market outlook, local studio status, replacement supply plans
- $EVO's marketing stance re: Pragmatic's celebrity push

FINANCES
- Profitability from $EVO's struggling higher-margin core sources (Europe & Asia) vs. growing lower-margin peripheries (Americas & Africa)
- Buybacks: pace, timeline & valuation

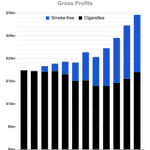
$PM Q3 results
‣ Cigarettes: consistent profit growth (2/3rds of EPS)
‣ IQOS: temporary slow-down (1/3rd of EPS)
‣ Zyn: persistent disappointment (~0% of EPS)

