

Searching for asymmetric bets, off the beaten path | Australian nomad
Newcastle, Australia
Joined June 2017
- Tweets692
- Following690
- Followers2.2K
- Likes1.6K




$PPS leveraging the AI talent acquired via Technotia to pull off a Reed Hastings esque talent density move. Including redundancy costs in the acquisition price, they have removed $9m in costs for $10.8m investment. If capitalised at 10X the investment has delivered 8X MOIC in 1yr


Frontline Services Group is currently seeking a hands-on General Manager to lead the business into its next phase of growth.
You'll have the support and trust of the ownership team—but also the autonomy to shape the business your way
linkedin.com/jobs/view/41834…
Daniel Sims retweeted

We own 32.1% of all the units in the Fat Prophets Global Property Fund (ASX: FPP), a poorly performing ASX listed investment trust that has has consistently traded well below net asset backing. We have put a resolution to all unitholders to consider winding up the fund. $FPP
Daniel Sims retweeted
Closing Thoughts:
Betting isn’t about maximizing wealth for me — it’s about maximizing utility. By flattening stakes, avoiding fragility, and respecting market signals, I aim for balanced, sustainable growth rather than short-term highs that risk long-term collapse.
Next week $FPP shareholders have the chance to generate a greater return in one day then the manager has made cumualtively over the last 7 years...


FAT PROPHETS for the underperforming fund manager, not for shareholders in FPP ASX, FAT PROPHETS GLOBAL PROPERTY FUND WIND UP VOTE
hotcopper.com.au/threads/fat…

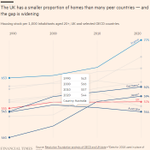
Australia literally the worst on this metric... and given our recent immigration boom, I'd bet it has materially worsened


Given market returns have been driven by a small number of "magnificient" stocks in recent years, I would not have guessed the momentum factor had stopped working 20 years ago
wsj.com/finance/investing/mo… via @WSJ

Daniel Sims retweeted
Shared our $WCG thoughts last Friday. livewiremarkets.com/wires/we…

stocknessmonster.com/announc…
I think this is a great result for $SEQ shareholders. Sure there is a funding risk, but it's essentially a free roll where if they fail to meet any of the payments we get paid a cash breakfee + get the business back!
If it completes, $SEQ will have $0.33 net cash per share + 4 remaining business units generating >$0.07 in EBITDA per share. At $0.60 price you're getting this stub at <4X EBITDA
The frequent use of "annus horribilis" in Q4 2022 fund manager letters so far is hilarious. Clearly all contrarian thinkers...
Daniel Sims retweeted
Imagine a circle laid flat on a table, with a little spinner on it that you can flick. The circle is 80% red and 20% yellow, like a yellow pie slice.
You flick the spinner. It spins, and slowwwly stops.
Where did it land?
78%On the red
22%On the yellow
77,876 votes • Final resultsDoes anyone know of the academic paper that showed fund managers top stock picks generate alpha, but they over-diversify to the point that the whole fund under-performs?
Not sure if this is what finally undid them, but there were plenty of reasons to put $WINE in the too hard pile imo. Base rates for DTC businesses are terrible


$RAP is an interesting merger arb in Aus at the moment. 11.5c last, 14.6c offer, 27% spread for a deal expected to close in <2 months.
Wide spread seems to be driven by a loud group of minority investors on HC who plan to vote against it, putting the headcount vote at risk...
Hopefully the register has more sane voters than this. I counted about 110 on HC. The more sensible arb buyers who get involved, the higher the chance the deal closes.
Will be interesting to see how this plays out, because the downside is substantial in a break scenario.