

Looking for new seat - macro / cross-asset. If you’re in NYC - shoot me a DM to connect!🍻 Substack: https://xitter.cf/t.co/LYfpKXgjyc
Joined February 2020
- Tweets2.2K
- Following980
- Followers1.2K
- Likes477
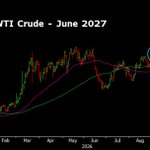


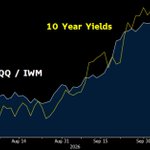



Despite front-month flat-to-lower in the last 6 weeks, Mid-2027 oil continues to grind higher.
$USO /CLM7


First-half 2027 oil might offer the best risk/reward on the curve.
Saudi east-west pipeline shut down and oil barely moved. (Hopes of talks, after strong run, not that surprising).
But, hard to see a world where oil is below $60 early next year (where we were pre-war).
Whereas $100 is easy to see. The number 1 supply workaround infrastructure just shut down!
$USO $XLE /CL


Small caps quietly still up 2% on the week. ✅
Long Treasuries, long mid ‘27 crude still both working well. ✅
I don’t see any reason to sell here, maybe some profit taking in oil with midterms getting close. (Fakenews article bound to be coming soon).
Yen finally reacts to vol, EUR/JPY down big. ✅
Nike +3.3% this week ✅
Start Philippine position only loser, down just -70bps on the week.
$TLT $USO $IWM $NKE $JPY $EPHE

I think the underperformance in tech over the last few weeks has far more to do with crowded positioning and the bond rally, then specifics around token-usage, anthropic ARR, Korean IPOs, or any of the other things people having been blaming the move on.
Late September: Tech became the hide-out spot as rising rates pushed spreads wider while small cyclicals, rate-sensitive areas, value, and equal-weighted baskets were punished.
Then in early October yields finally peaked and you have had a sharp rotation in the other direction. While defensives have of course rallied, look at equal-weight discretionary ($RSPD). 6-week highs today.
$QQQ $IWM $TLT


Nice +2% $IWM pop this morning…
Small Caps.
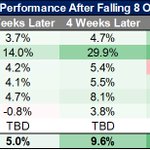
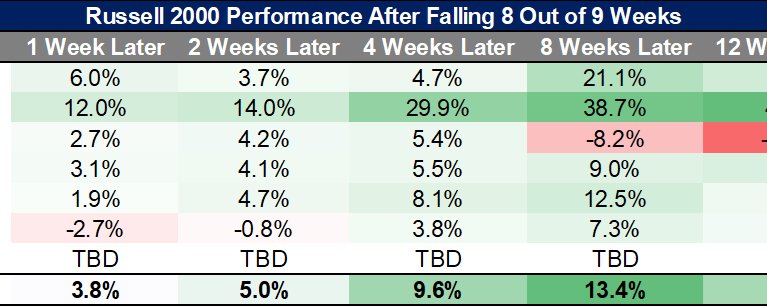
The Russell 2000 has fallen 8 of the last 9 weeks. Meanwhile, the 1 week it was up amounted to 0.1%, so it has pretty much been a straight line down.
While it briefly benefitted from the rebound in Treasuries, the pain in NeoClouds and the pop in equity vol on Friday brought it back to the lows.
I like buying Russell futures this week, worth a tactical long here.
$IWM


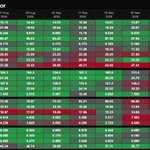
Cross-Asset Implied Vol HeatMap
First, it was rates vol $MOVE in late September heating-up, then credit took notice and sold off rapidly along with it. Equity vol $VIX which was previously ignoring the move, has finally capitulated and closed the gap…
Now, FX Vol is the only green left on the screen.

Small Caps.
The Russell 2000 has fallen 8 of the last 9 weeks. Meanwhile, the 1 week it was up amounted to 0.1%, so it has pretty much been a straight line down.
While it briefly benefitted from the rebound in Treasuries, the pain in NeoClouds and the pop in equity vol on Friday brought it back to the lows.
I like buying Russell futures this week, worth a tactical long here.
$IWM


Last 2 days: Over 25bps of hikes taken off the table for next year with 2027 oil at the highs, growth and inflation data red hot, with the SPX down a whopping -1.4% from its all-time highs.
Dalio same thesis this week. Ray on Japanese incentive to sell Treasuries…
“To the extent that the Japanese government wants to reverse—or at least control—these market excesses, it has big incentives to guide its institutions to sell and/or run down Japanese holdings of US Treasuries to repatriate money, which would help to curtail the yen’s slide and support the JGB market.”
$EUR/JPY
Yen Thesis Update:
I think this thesis has broadly been proven correct. The trade however has been basically flat. Treasuries have in fact sold off (I expected more intervention scare), while the Yen has not rallied much (largely due to positioning).
The better trade was to notice they would sell things like OATs before Treasuries.
Because of this EUR/JPY short HAS worked and has been a better FX play.
So overall, correct on what was happening, wrong on implementation.
Bloomberg Today: "A great asset migration is taking place in Japan as investors reallocate their overseas capital from bonds to stocks and unwind yen-funded carry trades. Some funds at Sumitomo Mitsui DS Asset Management have sold their entire holdings of French government bonds…"
$FXY $USDJPY
