
Public equities/options, card product @mercury. Eternal superalloy cubes @ https://xitter.gq/t.co/fz34u7r194.
North America
Joined April 2014
- Tweets2.1K
- Following495
- Followers1.7K
- Likes22.2K

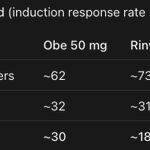



I appreciate @ldbioinv's skepticism re: $ABVX, it's been helpful pushback re: induction. But I think the below table summarizes the core argument for obe's future as the best drug in UC:
You can argue about obe's lower/wider induction CR range. But at the end of the day, on obe you have almost a 1 in 3 chance of getting to endoscopic remission. On Rinvoq/Tremfya you have a 1 in 5 chance.
With the VERDICT treat to target trial showing data pointing towards endoscopic remission as THE endpoint now, it's just a matter of that difference (plus Tremfya-equiv safety) sinking in for GI docs that see obe's data.


This was really good

In honor of some “pods blowing up” and me being traveling I will outline some concepts about pod risk management about which I do know a thing or two, as my name might suggest.
It is a common perception that pods are factor beta neutral and thus largely hedged. That is not quite true. A truer statement is that they are factor beta neutral to the extent they can measure the exposures.
Most equity risk models are derivatives of the original axioma and barra factor models. There are now many things that go into this but at their core they are a 12 (IIRC) variable linear regression. And mathematically, the unexplained remainder, the error term, is assumed to be the alpha (Upon which the team gets paid). You well recognize most of these factors: size, momentum (short and long), quality, dividend, domicile, sector, etc.
Now even the dull among you may note that there are in fact many other things that go into a stock. That’s true and that’s one reason why many people at the pods are very rich. There is though a very active and live debate to the highest level of these firms as what you “want” in the other bucket. On the one extreme, scheduling a proprietary drone flyover on the Aurora AV truck up fitting facility to measure parking lot activity vs expected timeline….that feels like pretty good alpha. On the other extreme, going long the Canadian listing rather than the U.S. listing because the Canadian listing diversifies the domicile score so you get a higher portfolio level idio score…..that doesn’t feel like great alpha. But the range is wide: paying GS a billion dollars so your team is the first meeting at the conference? That’s kind of the pod scale advantage. Albeit less so if every other pod is in the room. Going balls long large cap domestic U.S. GLP-1 manufacturers vs non GLP-1? Well that kind of is thematic alpha (depending on the work put in by analyst), but even if you’re of the opinion fuck it, let the kids rip (a reasonable view) you also know at the levered portfolio level that we aren’t measuring that risk completely. This line can really be illustrated with the concept of a “custom factor”. Maybe going long a shit load of SPACs is alpha, maybe it isn’t, but how the FUCK are you gonna build a portfolio level SPAC factor exposure loading in late 2021 when spacs didn’t functionally exist until 2021????
Anyways, interesting & active philosophical debate but there are some downstream derivatives.
Firstly, as a well known matter, 6 sigma events happen in finance all the time. There’s one every year in some corner of the market. So ex ante we know our models aren’t “great”.
Second, everyone knows the agent is an unobserved blind spot. It’s impossible to actually “know” why the analyst and PM are doing anything. You like to think they’re doing it on the back of deep fundamental quality work, but the median analyst and PM isn’t good at their job. So that assumption is known to be unreliable. The capital allocation solution to this is momentum chasing at the portfolio level: you allocate more to winning pods and you cut the losers fast. This is a brilliant approach because it means the pod business model is capital light- they identify and scale the good teams without actually having to invest in knowing which pods have “good” process. It’s worth really appreciating that point because it’s one of the true genius aspects of the model, and at its core it’s why the GPs are so fucking rich. (Deep finance readers will note that some of the original papers on factors saw that one of the earliest possible explanations for the decade-long trend nature for factor performance is implicit fund flow pressure from the momentum chasing nature of capital at the LP level)
(Continued in reply)
456
Could not agree with this more.
But I’ll add: the true value is in the searching. Have to wade through those mediocre opportunities to both find, recognize, and build conviction in the great ones.

The longer I invest the more I realize you get 1-2 great opportunities every few years. The rest of the time is spent wondering if you will ever get another great opportunity again and convincing yourself to own mediocre opportunities while you wait. Mediocrity is the price you pay for impatience.
microcapclub.com/active-pati…
2
589
First can we stop and admire for a sec the absolute CHAD ATM usage by $COGT mgmt here, they literally TOP ticked a $74m sale at $42 avg.
Second, the ATM means $COGT wasn’t in talks in Q3, and likely not now either. So that’s one prime late-stage BO candidate ruled out.


Explains part of weak Q3 price action, $COGT used ATM for $70M in proceeds. Guys, get the NDAs approved, sell the company and stop doing BS like this esp when you had >$600M on the balance sheet.
Excellent writeup covering the full $ABVX story to-date. Highly recommend for anyone looking to get up to speed.

PsyCap News: I'm on Substack! My first piece? Why $ABVX stock has kept declining since the summer. If you're holding the bag on obefazimod like most people on here, you better check this out! And yes, it's free. Link in the comments. More to come soon!

Re-entered at 1.13M $SKHY $000660.ks


1
1
637

lol. Gonna wait a little this time, not sure the dust has settled. Is this going to be like 5 times in a row I trade this right?

What an incredible story.

Today, Zipline raised $1.5b at a $21.5b valuation.
When we started Zipline, flying autonomously in the US was illegal. Which made it really hard to convince investors to give us money! But we were too naive to think that meant we shouldn’t try.
We started the company on a cow farm. We worked out of run-down construction trailers so that we could keep engineering, manufacturing, and flight test all unified and in one place. Hiring people from normal companies like Google was hard because we didn’t have a cafe or laundry service. But enough risk takers and rebels wanted to go on an insane adventure with us. They became the early team.
We decided to launch in smaller countries and focus on life-saving use cases. We hired incredible entrepreneurs and operators in Rwanda, Ghana, Cote D’Ivoire, and other countries. For eight years, Zipline expanded our service across Africa, serving thousands of hospitals and health facilities and reducing maternal mortality by 51%. Today, the network saves over 14k lives every year and is cash flow positive.
Last year, Zipline launched at scale in the US and the service exploded. We grew flight volumes about 100x over the last 18 months, and now make more than a million deliveries a year per metro. We’re now expanding with our partners to millions of deliveries per day. Normal families love having access to anything they need in 10-20 minutes, no matter where they live. Spend more time with loved ones and less time worrying about errands.
Zipline builds drone delivery that is silent and safe. No one wants to hear an extremely loud “swarm of bees” delivering to their backyard or their neighbor’s. Automated delivery needs to be insanely quiet, which guided the overall architecture of our technology delivering from 330 ft in the air. We are 6 times quieter than the closest competitor during delivery. Zipline also now has over 150m commercial autonomous miles (10x the rest of the industry combined) and no safety incidents. Neighborhoods should demand silent and safe delivery!
Today, Zipline is announcing two things. First, we just signed the largest autonomous vehicle contract in human history to expand automated delivery nationally with Walmart, our first and biggest partner in the US. We’re starting by scaling to 300 supercenters throughout the country. Second, we’ve raised $1.5b at a $21.5b valuation from existing and new investors, led by Paradigm, WCM, and Layer.
Zipline was a hard company to believe in for the first ten years of our history. Investors didn’t think the company was “investable”. Most people didn’t even think Zipline was an economic venture. Thanks to those who have rooted for us along the way. To all of the tens of millions of customers and families who rely on Zipline day in and day out: thank you for helping us build the future. Zipline has grown more than @ryanzip, @keenanwyrobek, I, and all others at the company could have imagined.
There is a big opportunity to build a new layer of infrastructure for humanity over the coming years. We want to approximate teleportation. We can build a logistics network that connects and serves all people on earth. We can free human flourishing from the choking constraint of traffic and roads. There are no roads where we’re going. 🚀🌎
1
352
Why is $SKHY reversing so suddenly? I actually think the Texas moratorium fears are reasonable- gives me some pause to hold too long


1
551
So the $NRIX $SNY news clearly shows that Sanofi/Garijo is continuing to make aggressive moves (and driving savings)... so who are they gonna buy?
Saw some takes on them buying $KYMR here, but they do also have a STAT6 inhibitor through Recludix? 🧵:
This is more conspiracy theory territory but ChatGPT found this job posting:
jobs.sanofi.com/en/job/cambr…
"Sanofi's Immunology Franchise is preparing to transform the treatment landscape for Inflammatory Bowel Disease (IBD) with duvakitug, one of Sanofi's high-priority new assets."

4
2
759
😋
Will enter for round 3 below 1.3M, trying not to jump the gun as I have the past two times (both at 1.4-45M)
$SKHY $000660.ks
