

Just a little goblin looking for the golden pot sharing information, discussing opinions, trading US and EU shares & options. No recommendations #DYOR
Joined March 2019
- Tweets3.2K
- Following321
- Followers3.4K
- Likes1.4K




"We lift $PDD from HOLD to BUY. The company has net cash equivalent to 72% of market cap and trades 2 s.d. below its average P/B, so the valuation is too attractive for us to look past, despite our concerns over Street Consensus being optimistic.
Our concerns regarding lack of shareholder returns and insufficient transparency remain, and the company is coming under regulatory pressure across its key markets that we expect may capping earnings, but we think substantially lower earnings are priced in."


UBS (double) downgrades $BESI.NA to Sell and expects a delay for meaningful Hybrid Bonding adoption from HBM4e to HBM5 which means TCB / conventional advanced packaging lifespan extends.
Hybrid bonding is not “wrong” but the timing and tool-intensity may be wrong (for now at least).


$AMZN Reading some sellside comments which see a pretty bullish AWS setup into Q3 earnings.
UBS raises PT to $348, forecasting 46% AWS operating margins in 2027 vs 38% Street, despite $300B+ capex, with +40.6% in revenue growth YoY.
Edgewater sees Q3 AWS revenue +40.9% YoY vs +37.6% consensus.


Goldman Sachs’ Taiwan PCB/CCL checks point to an accelerating AI hardware upgrade cycle.
Customers are increasingly funding supplier capacity expansions through LTAs/prepayments, while M10 materials command ~$800/sheet vs EMC’s ~$63 blended ASP.
ABF substrate CCL TAM could quadruple by 2028.

UBS bullish on PCB/CCL:
Q-glass is currently on hold after failed sampling, while an M9/PTFE hybrid has emerged as the more feasible solution - potentially reshuffling winners across the PCB/CCL supply chain.
Meanwhile, 800G/1.6T optical modules and custom ASICs are becoming important nearterm PCB drivers, reducing dependence on Nvidia alone. UBS therefore sees the recent weakness as more of a reset than the end of the AI PCB cycle.

$MU New quarterly bonus scheme linked to company profits: 50% in cash and 50% in shares

Barclays´ EU team flags a potential shift in AI infra from “capacity at any price” to “capacity at acceptable returns.”
Anthropic/Nscale pricing implies forward compute economics well below recent scarcity-driven $CRWV /$SPCX AI levels, suggesting buyers are starting to push back.
Seeing mildly negative readthrough for US peers like $ETN $HUBB $NVT $GEV $CRWV if scarcity-driven pricing/margins normalize.
But also potential +ive readthrough for Hyperscalers and AI Labs with lower equipment and compute pricing improves ROI and can actually support more total AI deployment $AMZN $MSFT $GOOGL $META
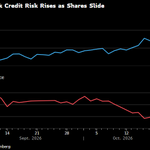
Softbank down 6% today after credit risks rise to a new 4y-high as concerns grow over AI-related funding.
Might be too obvious, but watching $ORCL again today for a potential readthrough with overall AI sentiment being a bit shacky today after the Korean Elice Inc. IPO desaster

SoftBank (-10% in its Asian session today) is the cleanest readthrough here so far: it’s basically a leveraged equity bet on OpenAI with its ~11% stake.
Oracle is a bit different here and arguably even riskier. It’s tied to +-$300B in compute and data center buildout.
If OpenAI demand wobbles, $ORCL isn’t just a valuation story but a balance sheet story.
Short $ORCL today and seeing it even lower than early ARCA prints around $167 but pls dyor!
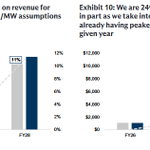
$CRWV upgraded to Buy at Goldman arguing the market is overstating financing risk and understating contract economics. Asset-backed DDTLs mean marginal funding costs look closer to ~7.5-10.5%, while new contracts around ~$13M/MW can still generate ~15% uIRRs; residual GPU value could push that toward 20-25%.
Positive for neocloud/AI infra peers with strong execution and financing access; also supportive for power, cooling, networking and storage vendors as enterprise AI deployment broadens. Biggest risk remains a future collapse in compute pricing once supply normalizes. $IREN $NBIS

Goldman Sachs just raised its global server TAM forecasts by 31% for 2027 and 45% for 2028, now approaching $1.6 Trillion (!!!) by 2028.
Both AI and traditional servers are driving the upgrade, fueled by AI infrastructure expansion, higher memory costs and richer configurations.


FinX discussing how $QQQ performs today and what a massacre this is ... but imagine you are a leveraged Korean seeing this - unable to react in any way, knowing the circuit breaker will enter the stage early monday ... that might hurt even more


$TSM ´s Wendell Huang "It is a bit too early to share the CapEx number beyond this year" ... it is October, when is the right time then?