
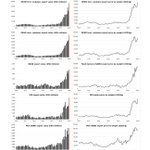


REMEMBER WHEN PEOPLE TOLD YOU IT WAS OVER? WELL, IT CLEARLY ISN’T
(TRASS-BF) South Korea Semiconductor Exports | November 20, 2026
$SKHY, $MU, $SNDK $NVDA $AMD
※ Y/Y compares export value with November 1–20 of the previous year; M/M compares it with the first 20 days of the previous month
※ ATH is the all-time high for cumulative export value from the 1st through the 20th of each month since data collection began in January 2016
[Export Value] All memory product categories record all-time-high export values
- DRAM (excluding modules): Export value $14,424mn, Y/Y +551%, M/M +32%
- DRAM (including modules): Export value $23,378mn, Y/Y +574%, M/M +49%
- Flash memory (NAND): Export value $1,943mn, Y/Y +217%, M/M +7%
- SSD: Export value $3,432mn, Y/Y +447%, M/M +55%
- MCP (HBM): Export value $7,884mn, Y/Y +275%, M/M +41%
[Export Unit Price] DRAM (including modules)/NAND/SSD export unit prices reach all-time highs
- DRAM (excluding modules) export unit price: $92,560/kg, +273% Y/Y, +22% M/M
- DRAM (including modules) export unit price: $75,349/kg, +350% Y/Y, +22% M/M
- Flash memory (NAND) export unit price: $104,462/kg, +298% Y/Y, 0% M/M
- SSD export unit price: $24,801/kg, +400% Y/Y, +35% M/M
- MCP (HBM) export unit price: $94,382/kg, +139% Y/Y, +2% M/M

1
7
269
$ANT
WOW BUY ANTHROPIC DIP
scientificamerican.com/artic…

111
AI Thesis retweeted
WOW 😵💫 Phison’s CEO just debunked the entire narrative behind the recent NAND selloff.
What’s crazy is how many sell-side analysts, independent research providers and firms selling supply-chain intelligence to institutional clients jumped on the bandwagon without even understanding the context. They started downgrading memory stocks and calling for a potential downcycle in 2027.
And what was the actual reason behind the Chinese SSD order cuts? GPU shortages and capital being redirected toward GPU prepayments, not structural demand destruction, according to Phison.
That’s exactly what I’ve been saying. Stop treating these people’s forecasts as facts. They collect information from third parties, conduct channel checks and extrapolate short-term trends without necessarily understanding the underlying reason.
Listen to the people actually running these businesses: Micron, SK Hynix, Samsung, CXMT and Phison. They have direct visibility into customer orders, inventories, production capacity and procurement.
Phison’s CEO is literally telling you that the biggest challenge in 2027 will be insufficient supply, not weakening demand.
$NVDA $MU
If Trump wants to save the stock market right now, he should ban CXMT and YMTC products from entering the US. In my opinion, that could mark the bottom of this AI stock sell-off.
And it could also protect American consumers if the concerns about product quality and reliability are substantiated.
Look at some of the Chinese resellers themselves warning people about reliability issues with certain DRAM and NAND products.
Why allow potentially unreliable products into the US while putting American memory manufacturers at a competitive disadvantage?
1
181
Phison CEO Pua Khein-Seng: Memory supply will remain tight next year
$MU, $SKHY, Samsung, $SNDK, $NVDA, $AMD
Phison wins six SSD controller chip development projects from three manufacturers… plans to hire 250 AI R&D staff
Spot prices weak vs. contract prices firm: With memory spot prices recently declining, Phison CEO Pua Khein-Seng said in an interview after the Meet Taipei forum on the 19th, "Weak purchasing power in the consumer market is weighing on spot prices, but contract prices remain stable and AI demand is also staying strong."
High margins add to consumer strain: High prices, with gross margins on some memory products reaching 80–90%, have driven up supply chain costs, while consumers' purchasing power has gradually reached its limits. The recent decline in spot prices is the result of this mounting strain.
Supply crunch to persist: The CEO predicted that memory supply would remain tight in 2027 and that securing supplies would still be difficult even in the second half of the year.
Phison's order wins, inventory and hiring plans
Major orders and workforce expansion: Phison has won a total of six solid-state drive (SSD) controller chip development projects this year from three NAND flash manufacturers (primary contractors) and plans to hire an additional 250 AI research and development (R&D) staff next year.
Continued NAND flash purchases: Concerns are already emerging in the AI market that cloud operators may be unable to secure the supplies they need for next year. Phison's inventory is also falling short of demand, and it is continuing to purchase NAND flash to support business growth next year.

$AAPL $META $NVDA $AMD
Welcome Apple to the AI CapEx cycle. You tried to avoid it, but you can’t run away from it forever. 😂
Apple knows that if they don’t do this, their core business will eventually be threatened. Look at Google, Meta and now OpenAI. AI is becoming a direct competitive threat to Apple’s hardware ecosystem.
Apple is going to learn the same lesson Google learned early on with Gemini. You can’t compete with frontier models by focusing primarily on efficiency while underinvesting in compute. Look at how much better Google’s models became after investing heavily in AI infrastructure.
And look at Siri AI. Just read the reviews. Nobody is impressed. Small local models running on regular Macs and iPhones are nowhere near capable enough to deliver the same experience as frontier cloud-based models.
At some point, Apple will have to invest heavily in compute, data centers and AI R&D to remain competitive.
The funny thing is that Apple was supposed to be the big tech company that didn’t need to participate in the massive AI CapEx cycle. Well, here we are.

NEW: Apple is developing an autonomous AI agent with computer-use capabilities, including device control, app interactions, web browsing and coding. The effort goes well beyond Siri and aims to compete with Meta’s Muse, ChatGPT’s Dots and Claude Code. bloomberg.com/news/articles/…

4
203
$INTU $PLTR $IGV $NOW $CRM
Like I said before, SaaS companies will get hit hard if their entire AI strategy is just taking open-source models and fine-tuning them. That’s not gonna work anymore.
Every SaaS company must become an AI company, just like Jensen said. They need to invest heavily in AI infrastructure, develop their own models and compete with the AI labs. If they don’t, the AI labs are coming for their business.
And it’s not even just the AI labs. Look at Google and AWS. Every couple of months, they’re releasing products that compete directly with SaaS companies.
One of the biggest mistakes these companies have made, in my opinion, is prioritizing stock buybacks, sometimes even taking on debt to finance them, instead of investing that money in AI CapEx and R&D to develop their own models.
I genuinely believe that would have generated a much better long-term ROI than buying back their own shares.
They need to wake up before it’s too late.

INTUIT $INTU Q1’27 EARNINGS HIGHLIGHTS
🔹 Revenue: $4.4B (Est. $4.31B) 🟢; +12% YoY
🔹 Adj. EPS: $2.91; +56% YoY
🔹 Global Business Solutions: $3.1B; +15% YoY
🔹 Online Ecosystem Revenue: $2.4B; +20% YoY
🔹 GAAP EPS: $2.59; +63% YoY
FY27 Guide:
🔹 Revenue: $23.08B-$23.37B (Est. $23.43B) 🔴
🔹 Adj. EPS: $22.88-$23.12
🔹 Adj. Operating Income: $8.06B-$8.15B
Q2 Guide:
🔹 Revenue: $4.93B-$4.95B (Est. $5.11B) 🔴
🔹 Adj. EPS: $3.17-$3.22
🔹 Adj. Operating Income: $1.13B-$1.15B
Other Q1 Metrics:
🔹 Consumer Revenue: $958M; +7% YoY
🔹 Credit Karma Revenue: $708M; +9% YoY
🔹 Mailchimp Revenue: $313M; -1% YoY
🔹 Stock Repurchases: $1.5B; +73% YoY
Key Updates:
🔹 Mailchimp Sale: Intuit agreed to sell Mailchimp to Bending Spoons for ~$3.68B, including $3.31B in cash and $368M in stock. It expects an early calendar 2027 close and plans to use the cash for buybacks.
🔹 Reporting & Outlook: Adjusted results now include stock-based compensation. Intuit recast the prior year on that basis. Both guides exclude the impact of the pending Mailchimp sale.
🔹 FY27 Outlook: Intuit updated revenue guidance for Credit Karma and reaffirmed its earnings outlook.
Comments:
🔸 CEO Sasan Goodarzi: “We delivered a solid first quarter, with results above the top end of our guidance”

1
3
270
AI Thesis retweeted
It’s genuinely mind-boggling how many people in the financial media keep repeating the same argument without even looking at the underlying unit economics.
Token prices going down in isolation tells you almost nothing about profitability. What matters is how fast the cost of producing those tokens is going down.
Anthropic literally said in its own SEC filing:
“Our compute efficiency allows us to deliver these reductions while preserving our margins.”
Opus 5.5 reduced customer costs per task by 40% while preserving margins.
Now look at Ramp’s OWN latest data over four weeks:
• Anthropic token prices: -10.2%
• Anthropic absolute token volume: ~+31.4%
• Anthropic token spending: ~+15.5%
You’re making intelligence cheaper, maintaining your margins, unlocking more use cases and expanding your addressable market.
How is that inherently bearish?
This is basic price elasticity and the mechanism behind Jevons paradox.
Imagine applying the same logic to the semiconductor industry throughout the last 40 years. The cost per transistor kept collapsing while the entire industry grew exponentially.
Falling token prices are not necessarily a threat to the AI cycle. They can be one of the biggest catalysts for its continued expansion.
Please, do some research on inference economics before calling the end of the AI trade.
AI Thesis retweeted

Fake news. Not what we're seeing in the market.
I've heard "so much capacity" coming online for many months now.
There simply is no power out there. Even if the Chinese labs gave back every GPU out there, demand would still outstrip it—and we're barely scratching the surface on swarms. We now have individual engineers burning 50BN tokens/day.
I, too, thought I was smart for not signing long-term commitments. It was an expensive lesson.
We're so bullish on compute at @telnyx that we started selling it ourselves, so we will have the GPUs we need a year from now. We don't offer commitments longer than a year for that very reason.

I would expect B300 pricing to continue declining.
A staggering number of neoclouds have approached us @liquidcompute looking to remarket long-term B300 capacity originally committed to Chinese-affiliated offtakers into the US and Western Europe due to concerns of stricter legislation regarding compute servicing to China.
liquidcompute.com/share/b300…

So Hunterbrook is now short $AMD and apparently we’re doing the same thing we did with Nvidia.
You found AMD firmware on a blacklisted Chinese company’s servers. Okay. Where is the evidence that AMD directly supplied that firmware without authorization? You literally admit in your own report that you don’t know how they obtained it or whether it was licensed.
Finding AMD’s code inside a third-party BIOS is not proof that AMD illegally exported technology to China. And we’re talking about EPYC CPU firmware here, not shipments of Instinct AI accelerators.
Then you compare AMD’s 22.4% China revenue exposure to Nvidia’s 9.1%, when the two companies don’t even use the same geographical accounting methodology. AMD uses billing location, Nvidia uses customer headquarters. And AMD sells consumer CPUs, gaming chips, embedded processors, etc. Not just AI GPUs.
The $67M licensing income? The original IP agreement was signed in 2016, three years before the Chinese entities were blacklisted. Receiving royalties from previously licensed IP is not the same thing as transferring new technology. It’s also just 0.19% of AMD’s annual revenue.
The Tongfu relationship? Also established in 2016. One of the two facilities is literally in Malaysia. This isn’t some secret supply chain AMD created to circumvent export controls.
And AMD has already disclosed that the US government granted it export licenses for both MI308 and MI325 accelerators.

Investors treated $AMD as the winner of Nvidia’s China crisis.
The problem: AMD has a China problem of its own.
Our investigation:
Readers added context they thought people might want to know
Hunterbrook reports AMD TurinPI firmware in post-Mar 2025 updates from Entity List-listed IEIT Systems (added 3/25/2025, denial policy) and linked firms. Report states it does not establish AMD violation or how firmware was obtained. Hunterbrook Capital is shorting $AMD. govinfo.gov/content/pkg/FR…
$NVDA $NOW $BLK $IGV
We’ve had three supposed apocalypses since the beginning of this year.
Remember when everyone said private equity was going to implode? Private equity stocks got crushed, and the predicted collapse never materialized.
Then came the SaaS apocalypse. Every software stock got crushed, and eventually everyone started piling back in.
And now we’re at the AI bubble apocalypse. Apparently, everything is going to collapse.
And guess what I think will happen? The same people panic-selling today will eventually pile back in at higher prices.
It’s the same stupidity over and over again. 😂
1
6
197
$CRWD $PANW
I think people are completely underestimating what’s about to happen in cybersecurity because of AI.
Look at all these recent cyberattacks and disruptions to critical infrastructure.
Companies are spending billions on CrowdStrike, Palo Alto Networks, Fortinet and other cybersecurity providers, yet the threat is evolving faster than ever.
And here’s what I think people are missing.
We’re entering an era where AI agents will be attacking systems, discovering vulnerabilities and adapting their techniques at machine speed.
You cannot fight autonomous AI attackers with just traditional cybersecurity software.
You need frontier cybersecurity models from companies like OpenAI and Anthropic, capable of reasoning, investigating and responding to threats in real time.
And yes, CrowdStrike and Palo Alto are already integrating AI. But that’s exactly my point. The entire cybersecurity industry is going to have to transform.
Simply adding an AI chatbot to an existing security platform won’t be enough.
These companies will need serious AI infrastructure, specialized models, massive inference capacity and autonomous defensive agents.
Otherwise, the frontier AI labs could eventually come directly for their business.
And here’s the interesting part for AI infrastructure investors.
Cybersecurity could become one of the biggest enterprise inference workloads in the world.
Think about millions of AI agents continuously monitoring networks, investigating threats and defending critical infrastructure 24/7.
That’s an enormous amount of compute.
This is why I keep saying AI infrastructure demand is structural. We’re only beginning to discover how many industries will need it.
4
379
$NVDA
BOYCOTT THE NEW YORK TIMES. BOYCOTT THE FINANCIAL TIMES BOYCOTT THE WALL STREET JOURNAL.
At this point, I think it’s time to start holding these publications accountable for the damage their reporting has caused.
Seriously, how many negative stories have we seen about NVIDIA over the past few months?
They pushed the narrative that NVIDIA would stop supporting neoclouds like CoreWeave, that neoclouds were finished.
They claimed NVIDIA’s suppliers were already sitting on excess capacity, that there was an abundance of supply and AI demand was slowing.
Then we had the stories suggesting NVIDIA’s China-related problems were evidence of wrongdoing by NVIDIA itself, rather than the actions of third parties.
And now look at what NVIDIA and its suppliers are actually saying in their earnings calls. The numbers and guidance are challenging these narratives.
How many more times are we going to go through this?
Retail investors have lost money. Hedge funds have blown up. Billions have been wiped off market valuations.
I’m not saying every bearish article is a lie. But if journalists knowingly publish false information that damages shareholders, there needs to be accountability.
If there’s evidence of deliberate misinformation, shareholders should seriously consider legal action.
You cannot keep publishing sensational headlines, moving markets and then pretend nothing happened when the actual numbers tell a different story.
Journalism comes with responsibility. And frankly, I’m getting tired of seeing the same thing happen over and over again.
AI Thesis retweeted

Over the past week, I’ve been overwhelmed by the love and support of friends, industry colleagues, and people I've never met. Thank you to everyone who has shown kindness to my family and me. It means the world to me.
I came to the United States 53 years ago, and becoming an American citizen is one of the greatest gifts and proudest moments of my life. NVIDIA has been my life’s work. Building it into the company it is today alongside my colleagues has been a privilege and an honor. Nowhere but in America could a company like NVIDIA be possible. I love our country, and I love NVIDIA.
I did not live up to the standards expected of everyone at NVIDIA, and I have made serious mistakes in my personal life. I created problems for the Board that I deeply regret. I own my mistakes completely, and I am committed to cooperating with the Board’s independent investigation.
Since my departure, I’ve seen an outpouring of calls from NVIDIA’s employees, investors, business partners, and customers for me to return as CEO. Many continue to reach out to me directly as the company navigates complex technology, market, competitive, and geopolitical dynamics. NVIDIA is a once-in-a-generation company. If the Board of Directors decides that my return is in the best interest of our shareholders, our employees, the company, and America, I would be honored to answer these calls and return as CEO.
Thank you again to everyone who has shared their good wishes. I am profoundly humbled by your support. To my family: I love you, and I will spend the rest of my life being worthy of yours.
Jensen