

CIO- Alternates PGIM India Investing Philosophy: Topline is Vanity, Bottomline Sanity, Cashflows Reality. Tweets are personal views
Mumbai
Joined April 2010
- Tweets2.4K
- Following1.1K
- Followers1.9K
- Likes432




A very interesting conversation around the Indian macro and the outlook. A barbell strategy around largecaps and smallcaps could prove to be a winning strategy!

With #macroeconomic headwinds beginning to ease and valuations at reasonable levels, this is a compelling opportunity to build equity portfolios, says @nahaani, CIO — alternatives, PGIM India Asset Management.
In an interaction with @Abzk_kr , Naha adds that smallcaps offer the best long-term investment opportunity, followed by largecaps and midcaps.
business-standard.com/s/2gAk…

1
245
Remember the rising yields in France, which I had mentioned in an earlier tweet

Franklin Templeton Warns: No One Is Ready For A Eurozone Debt Crisis 2.0 zerohedge.com/markets/frankl…

177

A very interesting article on how funding is getting tight, whether it is Govt #debt or AI debt.
Excess supply has it's consequences. Same goes for new IPOs in #India.
Banks are now trying to offload the AI data center debt they just underwrote startupfortune.com/banks-are…

1
1
234
Aniruddha Naha retweeted

France 10 year bond yield = 4.79%
Greece 10 year bond yield = 4.43%
Nobody who lived through the PIGS debt crisis in the early 2010s would have predicted Greece to be a better credit than France in 2026.

Aniruddha Naha retweeted

Private credit redemption pressure remains EXTREME:
Investors sought to withdraw 39.0% of Blue Owl Technology Income in Q3, up from 38.1% in Q2, keeping it by far the most heavily impacted fund in the industry.
At the same time, Blue Owl Credit Income faced 16.8% withdrawal requests, while Apollo Debt Solutions and Ares Strategic Income faced requests for 14.7% and 13.1%, respectively.
HPS Corporate Lending and North Haven Private Income also saw elevated redemption requests of 11.5% and 11.4%.
Across these major private credit funds, redemption requests remain well above the 5% quarterly cap, leaving substantial amounts of investor demand unfulfilled.
The pressure comes as investors remain concerned about asset quality, lending standards, and AI disruption to software companies, a major borrower base for private credit.
The private credit liquidity problem is far from over.

Aniruddha Naha retweeted

Japanese investors are DUMPING French bonds.
They hold $145 billion worth & now they're heading for the exits
Holdings are down 2.5% this year and some like Sumitomo Mitsui sold everything.
Even with French yields at their highest level since 2002, they don't offer much more than Japanese yields.
Why hold French debt when domestic bonds finally pay something?
The repatriation trade is accelerating.

Aniruddha Naha retweeted
Eurozone bond spreads keep widening as Spain’s snap-election announcement adds to France’s debt and budget fears. France’s 10yr spread over Bunds widens 4.7bps today, Italy’s 4.6bps, Spain’s 4.3bps. Germany remains a safe haven: only Austria, Latvia and Lithuania outperform Bunds today.

In my interview, I had mentioned about the yield spread between French and German bonds were a concern and not much is spoken about it.
Fears of a contagion in European debt market!
#Yieldspread #debt

Contagion risk is rising in the European bond market:
European government bonds are showing early signs of contagion, with France’s selloff spreading to Italy, Belgium, and Greece and producing some of their largest spread moves in years.
France remains at the center of the stress, as excessive borrowing, large budget deficits, political opposition to economic reforms, and rising debt servicing costs weigh on its bond market.
On Monday, the French-German 10-year yield spread widened another 10 basis points to +150 basis points, while longer-dated French and Italian bonds continued to underperform German debt.
Germany has remained a relative safe haven, with investors rotating into German bonds as the selloff spreads.
The key concern is that higher interest rates increase debt servicing costs, putting additional pressure on heavily indebted countries and causing bond market stress to spread across Europe.
The ECB is already facing pressure to respond, with traders reducing expectations for future rate hikes and policymakers potentially considering a pause in quantitative tightening if contagion intensifies.
Europe is once again facing the risk of bond market contagion.

The US 10year at 5.27%, and 30year at 5.6%, clearly indicating there is no appetite for long dated paper. Incase the middle east conflict sustains, yields will move up further, as inflation persists.
Argument sake, if the US 10year is at 5.75% ( which I believe could happen), it is very unlikely the India 10year can sustain at these levels. We will probably see yields in India move up by 40-50bps, taking the 10year to 7.75%, else rupee weakens further.
In such a scenario, it is unlikely we will see any positive FII inflows, when they can enjoy 10year paper held to maturity at 5.75% or a 30year paper at 6% and the risk of Rupee depreciation of 3% to 4% every year.
Also, another 6-9 months of flat markets on the Nifty, will make a lot of retail clients juxtapose the bank FD return vs market returns ( last 2 years have been painful for them)
Future returns will depend on the entry point into the market. Fy28 might be the year, where, fundamentals will be at the nadir and pessimism peaks out.
2
178
We have been cautious on Indian markets for almost a quarter.
High commodity prices across, agri, base metals and energy is inflationary.
The middle east conflict and constraints on availability of refining capacity is particularly worrisome.
Thr government has confirmed the El Nino fear, one of the worst in the last decade.
Globally also, inflation is reflecting across the bond yields and India is no exception. Rate hikes across the developed world will percolate to India also.
The other worrisome factor, not getting much of attention is the yields in Western Europe, particularly, France and the yield spread with German bonds.
While, the Marco environment is worrisome, Indian market has corrected and valuations are looking reasonable vis-a-vis it's own history.
Our view, while large caps have corrected, but earnings growth has also moderated significantly in large caps, and hence, on a PEG basis, they might not be very cheap.
We had raised 20% +/- 2% cash across our portfolios at the start of September, reflecting our cautious stance.
#Nifty
lnkd.in/dne73Nc5
3
295
We have been cautious on the markets for sometime and it reflects in the high cash levels in our portfolios.
The macro is a confluence of high crude, tight diesel supply, high agri product prices and inflation and tariff uncertainty. #Nifty

#AlphaManagers | Aniruddha Naha, PGIM India Asset Management To @CNBCTV18News
* Remain cautious on markets; Hope for a 5-7% correction in Nifty
* Believe the capital goods cycle is just getting started
* Positive on healthcare, Insurance and select capital market plays after valuation correction
WATCH: youtu.be/Go6eCpdMZDo
@Nigel__Dsouza @prashantnair @Reematendulkar @nahaani
#AlphaManagers #PGIMIndiaMF #CapitalGoods #Healthcare #Insurance #CapitalMarkets #CNBCTV18Market #Market

Aniruddha Naha retweeted
Why the Treasury Yield Surge Shouldn't Be as Big a Surprise as it is:
It is striking how many market participants have been surprised by the recent surge in US yields. The fundamental drivers have been evident for some time:
Borrowing plans for major issuers, such as the government and large corporates (particularly tech), have been well telegraphed.
The Federal Reserve has been signaling strong economic activity.
The reasons behind the declining willingness and capacity of some traditional holders/buyers of US bonds have been well covered.
The challenging quest to define the endpoint for the US/Israel-Iran conflict has been widely debated.
What is playing a far larger role than it should is psychological anchoring:
The collective mindset shaped by more than a decade of artificially low, repressed yields following the 2008 Global Financial Crisis.
#economy #markets #yields #bonds

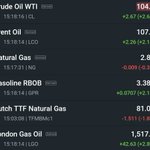
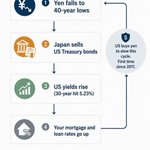
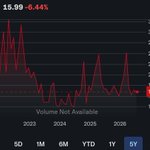
Four tables coming together can only be a case of concern.
Yields moving up.
Commodity and crude prices moving up
Currency losing it's sheen.
Best time to pace out your investments.


1
149


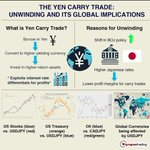
With inflation rising in Japan, interest rate have moved up. The interest rate differential with the US has started to narrow.
The Yen carrytrade was a success as the interest rate differential made sense to take risk. That looks to be unwinding. Charts from @apolloglobal


1
190