

Learn Deeply. Share Freely. My research and insights are free for everyone. You can become a supporting subscriber. https://xitter.gq/t.co/8SEhDctEiR
Joined December 2009
- Tweets3.1K
- Following1.3K
- Followers1.7K
- Likes2K



Pinned Tweet
blog.naver.com/4-fire/224166…
한국어로 보다 자세한 내용은 👆


$IONQ : Dilution, Revenue Growth, and Profitability — What the Numbers Actually Show
I've seen plenty of arguments that IonQ's revenue growth is meaningless because of acquisitions, increasing dilution, and the consolidation of foundry revenue. Others argue that once costs are considered, there's little left.
That's exactly why I put these three charts together.
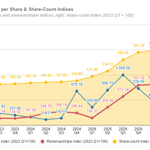
1️⃣ Dilution vs. Growth
From Q3 2025 to Q3 2026, outstanding shares increased 25.7%, but revenue per share surged 246.9%.
In other words, revenue growth has significantly outpaced dilution.
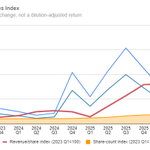
2️⃣ Revenue vs. Losses
Costs and absolute losses are still rising substantially. However, revenue is covering an increasing proportion of the adjusted cost burden.
Adjusted EBITDA loss coverage improved from 44.9% to 56.5%.
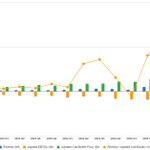
3️⃣ Gross Margin
Here's the important counterpoint: gross margin excluding D&A declined from 46.7% to 21.9%.
So while revenue growth and loss coverage are improving, gross margin is moving in the opposite direction.
This is why IonQ's increasing emphasis on cloud and software is particularly important, given their potential for higher margins.
These numbers don't eliminate concerns about organic growth, acquisitions, or profitability. But they show that dilution alone doesn't tell the whole story.
The next question is whether IonQ can turn this rapid growth into sustainable margins and cash flow.


$IONQ
The trend means more than “the company spends more because it has become bigger.” It suggests that the percentage of its adjusted cost burden covered by revenue is improving

Is $IONQ ’s Revenue Growth Outpacing Its Costs?
🇺🇸netcreat.substack.com/p/is-i…
🇰🇷blog.naver.com/4-fire/224468…
Growth Quality Is Improving, but This Is Not Yet a Cash-Generating Business


책상 서랍에 흔히 굴러 다니는 10G SFP 모듈을 분해해봤습니다.
이 모듈은 주로 네트워크 스위치나 서버에 쉽게 꼈다 뺄수 있는 장점이 있지만 이 모듈에서 광과 전기의 변환이 일어나기 때문에 이러한 변환 모듈을 가속기 혹은 칩에 되도록 가깝게 가져가려는 노력을 하는 중입니다.
NPO CPO라는 개념이 그것이죠. 두번째 사진은 광케이블에서 모듈과 연결되는 부분인데 빛이 다니는 부분을 사진에 담기 위해 애를 먹었습니다.
모듈 내부의 도식은 AI의 도움을 깔끔히 영어 한국어 버전으로 만들었으니 참고하세요.
🤖 Made with AI


Is $IONQ ’s Revenue Growth Outpacing Its Costs?
🇺🇸netcreat.substack.com/p/is-i…
🇰🇷blog.naver.com/4-fire/224468…
Growth Quality Is Improving, but This Is Not Yet a Cash-Generating Business
Interestingly, people in the Korean investor community I’m part of were already talking yesterday, right after the earnings release, about IonQ potentially reaching $1 billion in annual revenue sooner than expected. The results and outlook IonQ delivered were truly the strongest in its history.

“We’re building the quantum ecosystem for the Western world—for our nation, for the Five Eyes, for NATO.”
That’s the mission our CEO, @NiccoloDeMasi, shared with @barronsonline, and it’s how we're driving to be the NVIDIA of quantum.
Today, we supply roughly a dozen other quantum companies with systems, chips, and atomic clocks. We’ve also advanced to the final stage of Defense Advanced Research Projects Agency (DARPA)’s Quantum Benchmarking Initiative, an independent audit of progress toward industrially useful, error-corrected quantum computing.
We’re delivering on what we set out to do, and momentum is building. Quantum is now.
Read the full story in Barron’s: barrons.com/articles/ionq-ea…
#QuantumComputing #QuantumInnovation #QuantumIsNow

IonQ Q3 2026 Earning Call
netcreat.substack.com/p/ionq…
IonQ Q3 2026: The Story Is No Longer Just About Quantum Technology
IonQ reported a record $173.8 million in quarterly revenue and raised its full-year guidance to $505–515 million. But the headline revenue growth is not the most important takeaway, especially given SkyWater's contribution.
The real story is the transition from technological promise to commercial execution.
1. Superion 256 demand is becoming tangible. IonQ says its currently planned 2027 production capacity is sold out, with orders beginning to fill into 2028. However, unit volumes, average selling prices, and delivery-based revenue remain undisclosed.
2. Commercial commitments are accelerating. IonQ Platform's remaining performance obligations reached $689 million, supported by approximately $290 million in new contracts, including $180 million related to quantum computing.
3. SkyWater could fundamentally change the manufacturing equation. IonQ reported 12 times more wafer lots and over three times faster tape-out cycles for its 256-qubit chips. The next challenge is scaling complete systems, not just manufacturing chips.
4. NVIDIA provides a critical deployment test. The planned 2027 installation at NVIDIA's research center could help validate stable GPU-QPU integration in real-world data center environments. Broader deployment is an opportunity, not a committed outcome.
5. IonQ is building businesses beyond quantum computers. Quantum security, sensing, networking, cloud services, and foundry operations could create more diverse revenue streams. Elisity, in particular, introduces a potentially high-margin recurring software business.
Management believes the quantum-cybersecurity TAM could one day exceed the quantum-computing TAM, with software potentially providing higher margins.
Management says buying Elisity significantly accelerated the development of capabilities IonQ had planned to build internally.
An early partnership at NVIDIA’s Boston research center could have considerable strategic value if IonQ’s system proves capable of stable data-center operation despite vibration and optical-alignment constraints.
But the financial reality matters. Acquisition-driven growth, operating losses, cash consumption, stock-based compensation, and dilution must be evaluated alongside commercial momentum.
My central takeaway:
IonQ has made meaningful progress in demonstrating that customers want its technology. The next phase will determine whether it can manufacture, deliver, and monetize that demand efficiently — while creating lasting value for shareholders.
The question is shifting from "Can IonQ build it?" to "Can IonQ scale it profitably?"

blog.naver.com/4-fire/224467…
Anduril, Northrop Grumman, Carahsoft까지.
국방부 PQC를 비롯해서 전부 싹쓸이 하려나요?


IonQ Completes Its Acquisition of Elisity: What It Really Means — The Definitive Analysis
🇺🇸netcreat.substack.com/p/ionq…
Two things stand out in the latest announcement from Elisity, the cybersecurity company acquired by IonQ.
First, Elisity is targeting the first half of 2027 for expanded cryptographic inventory and security posture intelligence capabilities.
Interestingly, this timeline aligns with the U.S. federal government's PQC migration roadmap under the Trump administration.
Second, Elisity says its solution can leverage supported existing network infrastructure without requiring dedicated sensors.
This could allow enterprises to identify quantum-vulnerable cryptography and connect those findings to Zero Trust policy enforcement, while reducing deployment costs and operational complexity.
For me, this is where Elisity's strategic value becomes particularly interesting.
The real competitive advantage may not be detection technology alone, but the combination of deployment simplicity, broad visibility, and the ability to turn security intelligence into enforceable network policies.
I believe these capabilities—combined with the potential to align with the 2027 migration timeline—help explain why Elisity was such an attractive acquisition target for IonQ.
Of course, actual detection coverage and the planned integration still need to be validated.
IonQ, Elisity 인수완료와 그 의미 최최최종
blog.naver.com/4-fire/224466…
IonQ가 인수한 엘리시티(Elisity)의 최신 발표에서 주목해야 할 부분은 두 가지입니다.
첫째, 2027년 상반기 출시를 목표로 하는 암호화 자산 조사 및 보안 상태 분석 통합 기능입니다. 흥미롭게도 이 시점은 트럼프 행정부가 추진하는 미국 연방정부의 PQC 전환 일정과 맞물립니다.
둘째, 별도의 전용 센서를 추가로 설치할 필요가 없다는 점입니다. 지원되는 기존 네트워크 장비를 활용해 암호화 취약성을 파악하고, Zero Trust 정책까지 연계할 수 있다는 것입니다.
기업 입장에서 이는 단순한 기술적 장점을 넘어 도입 비용과 운영 부담을 줄일 수 있는 중요한 경쟁력이 될 수 있습니다.
2027년 일정에 맞출 수 있으면서 배포가 쉽고, 탐지의 사각지대가 가장 적은 업체가 Elisity였습니다.
자세한 내용은 블로그 내용을 참고하시기 바랍니다.
Quantum Security Deep Dive (4) — Why Is $IONQ Focusing on QSPM, QKD, HSMs, and Elisity? The Economics of QKM and Crypto Agility
🇺🇸netcreat.substack.com/p/quan…
🇰🇷blog.naver.com/4-fire/224463…
The vault is stronger and more secure than many people realize.
But the real challenge is how safely we deliver and manage the key that opens it. That is why the emphasis shifts from making the vault itself even stronger to safeguarding the key.
And there is no such thing as perfect security.
Even with a heavily fortified vault, if someone manages to steal the key through any route, we build multiple layers of defense so that the vault cannot simply be opened at once and the resulting damage cannot spread unchecked.
$IONQ
어제 Elisiy의 인수가 마무리가 되었습니다.
Elisity의 PQC를 따르지 않는 탐지는 IonQ가 개발중인 QSPM과 함께 이루어지며, 새로운 하드웨어 센서의 추가 없이도 경쟁사 대비 사각지대 없이 신속히 이루어 질 수 있습니다.
Forescout, Paloalto, Zscaler의 탐지기능과 비교를 하면 쉽게 이해가 됩니다.
그리고, 이러한 솔루션의 배포는 쉽고 빠르게 이루어져야 HNDL의 피해를 최소화 할 수 있습니다.
내일 IonQ의 실적발표가 있습니다. 질의 응답시간에 이에 대한 질문이 많이 나올 것으로 예상되고, IonQ의 경영진이 이에 대해 합리적인 답변을 할 것으로 기대됩니다.
그것이 기술적인 질문이거나, 인수 금액에 대한 질문일지라도.
$IONQ
Is QSPM's Real Competitive Advantage in Deployment Architecture Rather Than Detection Sensors?
Full report here.
🇺🇸netcreat.substack.com/p/is-q…
🇰🇷 blog.naver.com/4-fire/224461….
There’s a world of difference between having absolutely no blind spots and having even just a few.

IonQ, Elisity 인수완료와 그 의미 최최최종
blog.naver.com/4-fire/224466…
IonQ가 인수한 엘리시티(Elisity)의 최신 발표에서 주목해야 할 부분은 두 가지입니다.
첫째, 2027년 상반기 출시를 목표로 하는 암호화 자산 조사 및 보안 상태 분석 통합 기능입니다. 흥미롭게도 이 시점은 트럼프 행정부가 추진하는 미국 연방정부의 PQC 전환 일정과 맞물립니다.
둘째, 별도의 전용 센서를 추가로 설치할 필요가 없다는 점입니다. 지원되는 기존 네트워크 장비를 활용해 암호화 취약성을 파악하고, Zero Trust 정책까지 연계할 수 있다는 것입니다.
기업 입장에서 이는 단순한 기술적 장점을 넘어 도입 비용과 운영 부담을 줄일 수 있는 중요한 경쟁력이 될 수 있습니다.
2027년 일정에 맞출 수 있으면서 배포가 쉽고, 탐지의 사각지대가 가장 적은 업체가 Elisity였습니다.
자세한 내용은 블로그 내용을 참고하시기 바랍니다.
Quantum Security Deep Dive (3) — Zero Trust and Microsegmentation: Breaching Systems Without Breaking Encryption
🇺🇸netcreat.substack.com/p/quan…
🇰🇷blog.naver.com/4-fire/224463…
What if hackers don't need to break encryption at all?
Imagine a hospital protected by AES-256 and post-quantum cryptography.
An attacker steals a legitimate employee's credentials.
No Shor's algorithm. No Grover's algorithm. No broken encryption.
Just a valid login—and access to sensitive data.
Now comes the more dangerous question:
How far can that attacker move inside the network?
Can one compromised server lead to databases, backups, and critical infrastructure?
This is why Zero Trust and microsegmentation matter.
PQC protects key establishment. Microsegmentation limits the blast radius.
In Part 3 of my Quantum Security Deep Dive, I explore why quantum-resistant encryption alone is not enough—and how Zero Trust, EDR, NDR, and network policy enforcement fit into the bigger cybersecurity picture.
Quantum Security Deep Dive (2) — Sharing and Protecting AES Secret Keys: USB, QKD, OTP, Hybrid PQC, HNDL, and Key Management
🇺🇸netcreat.substack.com/p/quan…
🇰🇷blog.naver.com/4-fire/224463…
What if the biggest threat to AES-256 isn't breaking the encryption itself?
AES-256 is extraordinarily difficult to crack, even with quantum computers.
But there's a catch.
You don't need to break the lock if you can steal the key.
And even if the key is safe today, an attacker could record encrypted traffic now and decrypt it decades later.
That's the danger of Harvest Now, Decrypt Later (HNDL).
So how should we protect the keys?
USB? QKD? One-Time Pads? Post-Quantum Cryptography? Hybrid approaches?
Each offers different advantages, but none eliminates the need for secure key management.
In Part 2 of my Quantum Security Deep Dive, I explore why the future of cybersecurity may depend less on breaking encryption and more on how we establish, distribute, protect, and manage the keys.

$SPCX $QCOM
SpaceX, 미국 지상 5G망까지 구축한다
blog.naver.com/4-fire/224466…
스타링크가 미국 전역에 5G 기지국 수만 개를 구축한다고 합니다.
그런데 위성통신의 강자인 SpaceX가 왜 갑자기 지상 기지국까지 설치하려는 걸까요?
더 흥미로운 건 Qualcomm이 기지국의 핵심 기술 공급사로 선정됐다는 사실입니다.
그렇다면 Nokia와 Ericsson은? NVIDIA가 추진하는 AI-RAN은? AST SpaceMobile의 경쟁력은 어떻게 달라질까요?
사실 이 질문에 답하려면 5G 네트워크가 어떻게 구성되는지부터 이해해야 합니다.
스마트폰에서 시작해 안테나, RU, DU, CU, IP·광전송망, 5G Core까지. 각각 누가 만들고, 어디에서 돈을 버는지 살펴봤습니다.
그리고 과거에 분석했던 Starlink와 ASTS의 D2C 경쟁 구도를 이번 발표를 계기로 다시 평가했습니다.
기술이 발전했다고 반드시 그 기술을 보유한 기업이 가장 많은 돈을 버는 것은 아닙니다.
이번 발표에서 누가 돈을 투자하고, 누가 장비를 공급하며, 누가 장기적인 반복 매출을 확보하는지를 구분하는 것이 핵심입니다.
5G에서 6G로 넘어가는 통신산업의 구조와 투자 기회를 함께 정리했습니다.


4FIRE retweeted

Elisity is now part of @IonQ_Inc .
Together, we’ll build on our Zero Trust capabilities to help customers protect critical systems today and prepare for the quantum era.
We’re excited to join the IonQ team!
elisity.com/news/elisity-joi…
