

investigative research. concentrated positions in disruptors & deep value. god. husband. father. love of country. @bxsement
basement
Joined March 2015
- Tweets3.4K
- Following9
- Followers2.1K
- Likes29.6K




Pinned Tweet
The man has spoken. It's a done deal.
WHEN $OSCR hits $100 I will organize a retail meetup in NYC to meet new people, celebrate conviction, hard work, and execution! Book it!

For anyone who doesn’t know or needs a reminder:
on one ordinary transaction, roughly $36,000–50,000 (or about 8% to 12%) of a home's value is consumed by the process of changing owners, before counting months of mortgage, tax and insurance carry while it sits listed or the double move.
$OPEN is set to reduce that significantly putting more cash in both the buyers and sellers pockets while becoming the go to marketplace for homes!
Economics of scale vastly improve as the data continues to compound. The middle layer is already proving its place as we knew it would.
When $OPEN can reduce costs of transfer from 8%-12% to 5%-7% you’re talking about $12,000-$20,000 per home transfers using the U.S. median home price of $425,000. I don’t know anyone who’s going to leave that in the table by choice if there is an alternative to capture it and put it back in their own pocket.
$OSCR SG&A was 14.0% in Q3, down from 14.2% in Q2, it continues walking down as it scales.
For CY ‘27 on 25B of revenue, every point of SG&A leverage is $250M of operating earnings. Roughly $0.60 a share.
A business that gets cheaper to run per member as it grows through operating leverage is such an attractive asset to own.

Q4 revenue guided up at least 40% year over year. The ANI target slipped. I judged that honestly on Thursday/Friday. More accountability there.
The problem isn't demand. It's the spring vintage clearing at a loss into Q1 from a timing mistake.
Growth plus a fixable problem so long as it’s not ignored. $OPEN
When you think about the people who are operating a business you own a piece of this is the type of culture you want to see. $OPEN
I have encouraged people to read over Fahd’s material before and I again encourage you to read this!

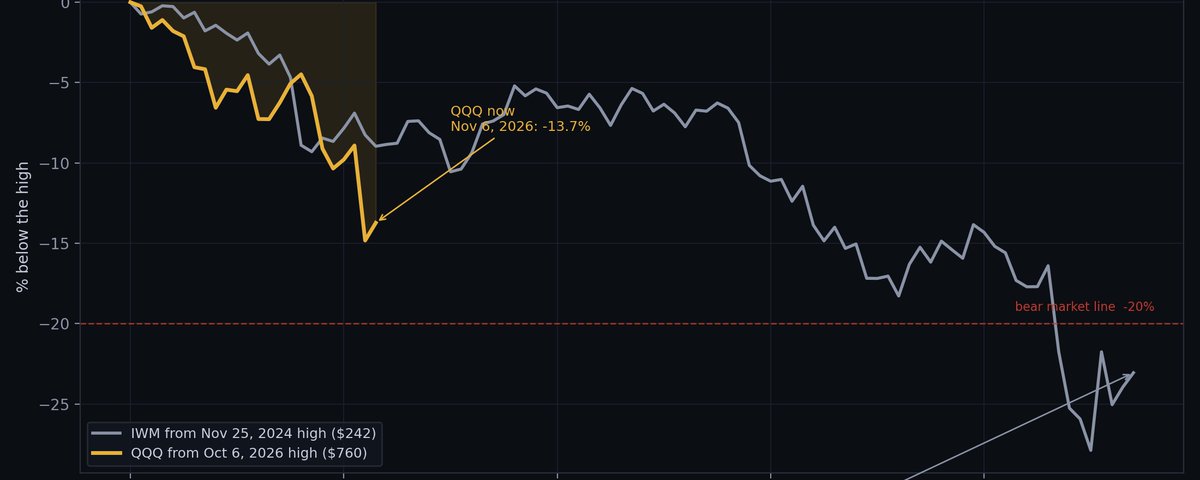
$OSCR at $30 based on new CY 26 guide and what I expect in February for 2027 is as bad as $11 was in March.
Do with that what you will 🤷🏾♂️
I am a shareholder in $OPEN and growing my position. So, @nejatian please read this as a partner, not a critic.
In September you set the bar yourself: revenue +20%, contribution margin 4–4.5%, contribution profit doubled, ANI positive by year-end.
Q3 came in at +12%, 3.3%, and +70%. Your CFO then told us both profit targets are behind schedule, margin is guided down again, and the spring homes clear at a loss into Q1. Every leg of your own bar, missed. That's what shareholders are actually pricing.
The frustrating part: the progress underneath is real. Cash Now, More Later over $1B in a year. Title & escrow at 3x volume. Mortgage up 5x in a quarter. Marketing cost per home down 57%. You take $1 in salary. The building is real. I see it but you’re self-sabotaged by being extremely aggressive in your execution timeline instead of guiding and setting expectations low for the time it will really take to perform the full turnaround.
We got a little ambitious and ramped acquisitions too soon and now are stuck with aging inventory we have to unload. We are too smart to be told it’s because of the last 30 days of macro! It was bad execution, mistiming, and over promising.
So here's the ask going forward: set targets you'd stake the company on, then grade yourself against them in the open, every quarter. Shareholders can price honesty. We cannot price hype. Give us realism and you'll get patience and reasonableness in return.
I'm here for the decade. I believe in the problem, the potential and the leadership. Thank you!

Looking forward to give you all an update about what we've been up to for the past few months at Opendoor.
We'll go live in about an hour on @Opendoor.
For what it’s worth $OSCR has options expiring this week that had built in election and earnings results.
It bounced almost perfectly between the extreme bands and is looking to close the week right at max pain for both sides.
The weekly candle looks ugly but I’m more interested in next week.
As always, regardless, the long term thesis is in tact and this move although not what we wanted to see is irrelevant
The good part about this for $OPEN if you’ve been sizing correctly is there is plenty of time to grow a position as the stock may bounce around but I don’t anticipate any big sustained moves unless we get headlines throughout the next Q

It’s too late for me to do a full review of $OPEN and the numbers / commentary. But I’ll say a few words:
> Under the hood, the NEW business at Opendoor is genuinely working and it's bigger than the headline numbers suggest. Kaz admitted on the call that he "underestimated how big a business title and escrow could become.” it's already running 3x last year's volume, and they're now extending it to transactions that have nothing to do with Opendoor.
>Same with this week's launch of Buy with Opendoor: the full product suite including mortgage, title, escrow now open to buyers whether or not they buy an Opendoor home.
>Cash Now, More Later passing $1B of volume in a year, mortgage originations up 5x in a quarter, and marketing cost per acquired home down 57%, and the pattern is clear: the future of this company is owning the transaction, not the house.
> What they got wrong was timeline and sequencing. They were far too aggressive. Acquisitions ramped +316% before the resale system was ready.
>by management's own scorecard, acquisitions are "solid green" and resale velocity is "yellow." homes bought before the discipline was in are being cleared at a loss, with the pain guided into Q1.
>The result is bloated, aging inventory 7,596 homes, $2.57B on the books, stale listings doubled to 18%
>carrying costs eating the P&L with two-thirds of the Q4 loss guide is holding costs. The CFO has now conceded both profit targets are behind schedule.
> The balance sheet isn't broken with $910M in cash. But $1.8B of operating cash burn in nine months means the clock is ticking louder than the plan assumed.
The new business is becoming more real. The old one's mistakes are what they have to outrun because they got to antsy to wait another Quarter or two before ramping acquisitions.
Time will tell. For now I’m still long my small piece and looking to add!
It’s too late for me to do a full review of $OPEN and the numbers / commentary. But I’ll say a few words:
> Under the hood, the NEW business at Opendoor is genuinely working and it's bigger than the headline numbers suggest. Kaz admitted on the call that he "underestimated how big a business title and escrow could become.” it's already running 3x last year's volume, and they're now extending it to transactions that have nothing to do with Opendoor.
>Same with this week's launch of Buy with Opendoor: the full product suite including mortgage, title, escrow now open to buyers whether or not they buy an Opendoor home.
>Cash Now, More Later passing $1B of volume in a year, mortgage originations up 5x in a quarter, and marketing cost per acquired home down 57%, and the pattern is clear: the future of this company is owning the transaction, not the house.
> What they got wrong was timeline and sequencing. They were far too aggressive. Acquisitions ramped +316% before the resale system was ready.
>by management's own scorecard, acquisitions are "solid green" and resale velocity is "yellow." homes bought before the discipline was in are being cleared at a loss, with the pain guided into Q1.
>The result is bloated, aging inventory 7,596 homes, $2.57B on the books, stale listings doubled to 18%
>carrying costs eating the P&L with two-thirds of the Q4 loss guide is holding costs. The CFO has now conceded both profit targets are behind schedule.
> The balance sheet isn't broken with $910M in cash. But $1.8B of operating cash burn in nine months means the clock is ticking louder than the plan assumed.
The new business is becoming more real. The old one's mistakes are what they have to outrun because they got to antsy to wait another Quarter or two before ramping acquisitions.
Time will tell. For now I’m still long my small piece and looking to add!
“we believe that it's not just price. It's the quality of the product, quality of customer service. We tend to have higher retention than our competitors do. As a result, we have higher NPS scores. As we look at all of that, it's a mix of capability and our relationship with our customers and our distribution channel that matter. It's not just the price point.”
When asked about pricing and being lowest this was Marks response. I think most people can do some anecdotal research in their own lives and find they’re willing to pay a bit more for a product or service if it’s quality is far superior to the other and the price doesn’t jump significantly. Eventually marketing by way of word of mouth, brokers, and reviews does the legwork.
@mtbert $OSCR
“We are being prudent in making sure that we are thoughtful about the continued morbidity risk that is inherent in this marketplace. We feel like we have more than adequately covered for that in the guidance, and we are walking into good news. So, feel like we have got a very balanced target for full year operating earnings.”
This is a great blip that came from Mr Baxters first “question”
-Scott Blackley $OSCR
Just after this in the call Scott really reiterates this:
“We expect improved medical cost performance and administrative efficiency to drive further margin expansion next year.”
$OSCR
“The third quarter SG&A expense ratio was 14%, the lowest in the company's history. The approximately 350 basis point year-over-year improvement was driven by lower risk adjustment as a percentage of premium, higher fixed cost leverage, and disciplined expense management, including an increasing impact from technology and AI initiatives.”
Scott, I believe, telling us that their AI / tech stack is creating excellent operating leverage as the business grows.
As the wheel spins less and less of a % of revenue is required for SG&A which leads to better margins!
-Scott Blackley $OSCR
“The third quarter SG&A expense ratio was 14%, the lowest in the company's history. The approximately 350 basis point year-over-year improvement was driven by lower risk adjustment as a percentage of premium, higher fixed cost leverage, and disciplined expense management, including an increasing impact from technology and AI initiatives.”
Scott, I believe, telling us that their AI / tech stack is creating excellent operating leverage as the business grows.
As the wheel spins less and less of a % of revenue is required for SG&A which leads to better margins!
-Scott Blackley $OSCR
“Risk adjustment as a percentage of premiums was 11.8% in the third quarter and 17.2% through the first nine months. While the additional data gives us greater visibility and more confidence in our risk adjustment accruals, we continue to take a cautious approach to our risk adjustment reserves.”
-Scott Blackley $OSCR
I reiterate my $OSCR base case for 2027 being $25b in revenue at 5% margins for fully diluted EPS after taxes absolutely no less than $2.80.
Kids are to bed and I will be starting my second listen of the call and will be posting my field notes!
If anyone wants to chat about the company please reach out!
The time to begin using leverage is when those who used leverage are blowing up into a volume and range capitulation.
Buying some $NBIS