

full-time satire/comedy. part-time capital allocator & tech nerd 🤓 formerly 20+ years in sell-side IB & equities. not investment/financial advice. DYOR
salomon's house
Joined July 2025
- Tweets1.3K
- Following95
- Followers2.9K
- Likes1.2K





Pinned Tweet
In the picture is a baby orangutan (ape), nicknamed Novita, estimated to be of 3-4 years old
Novita was found clinging to a tree near an oil palm plantation located in Borneo in late Sep
Her palms and soles were burnt, because she had to walk through fire in her habitat to the tree to take refuge
She was rescued by a team after a local resident called it in, and is now undergoing rehabilitation
Land and forest fires have serious consequences for wildlife
The cheap slash-and-burn land clearing practices by the palm oil companies and those who control the concessions need to stop
Time to short those mofo palm oil companies listed in Singapore, Malaysia and Indonesia. Make a call to your banks to question them about their loans to these companies, and their sustainability pledges
APES TOGETHER STRONG

Looks like flight to safety
The twist - we may see hyperscalers/AI names lining up to tap credit soon with falling yields. Not sure whether there'll be appetite for corp credit (vs treasuries) tho 🤷♂️


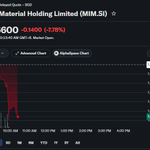
The stabilization bank for Mi Material has just announced that it had used up all the overallotment shares to hold up the stock within 2.5 trading sessions - a record timing

well, that oversized tee + shorts getup did mark the top 🤣


* BLOOMBERG: Fund Managers Quit to Trade Their Own Money in Taiwan Stock Boom *
Highlights -
For Ken Tsai, one winning bet still stings.
In 2024, while at one of Taiwan’s biggest asset managers, the 40-year-old fund manager made a Taiwanese supplier of components that transfer data between AI servers his fund’s biggest holding. The stock surged more than fivefold the following year - then another sixfold in 2026.
Bound by rules, Tsai didn’t own a single share in his personal accounts. Tired of seeing his calls enrich the fund - but not himself - he departed in July for a Taipei-based private investment firm that provides a more attractive revenue sharing model and grants bigger room for personal investments.
“It left me with a strong sense of relative deprivation.” he said, “People who were free to buy the stock ended up making more money than I did.”
Relatable feeling
Make a guess - what stock is he referring to?
Also relatable, rocking up to meetings in oversized tees and shorts ✌️


hope folks who got shares at IPO sold some at the IPO price to the stabilization bank for exit liquidity over the preceding two trading sessions
let's not forget that 8,980,524 shares were also distributed to eligible shareholders of the parentco (Mi Technovation) - which may add to the selling pressure
$MIM.SI

For the AI trade to sustain its run, these things need to happen, in my view:
1. Memory costs (especially ASPs) need to come down. The game memory makers are playing is obvious - they are having their sweet revenge moment after the last downturn about 3-4 years ago. Forward growth should be on volumes, not pricing
2. AI models need to be more efficient - e.g. shorter CoT, better routing, token output generation should commensurate with work complexity and not output maxxing even for the simplest workloads
3. Token pricing should go UP, to reflect intelligence & value-add. Pricing tokens based on actual demand-supply dynamics better allocates finite resources. The Jevons argument is bullshit. There's a reason why Ferraris are priced higher than Toyotas - intrinsic value. Under-pricing tokens vis-a-vis actual value distort markets
4. The Iran war needs to end, so that energy-led inflation cools = path to lower rates = lower cost of capital = easier for hyperscalers/AI names to raise money
How mass-market cars would look like in Singapore if vehicle dimensions are used to determine the COE amount a car buyer needs to pay

Nippon Kodoshi $3891.T revised up FY27/3 forecasts (revenue, OP, NP and dividends) in an update post-close today, on the back of strong GenAI demand for aluminum electrolytic capacitor separators
They are also expanding current capacity at Tottori by 30% with construction start in May 27 and target ops end-28


Remember UltraGreen? They just provided their Q3 update, and it's a disaster (not like it's unexpected)
Takeaways:
■ The US ICG market has become more competitive with the entry/approval of generic offerings by Zydus and Provepharm. The latter’s Zyogreen product is a strong product alternative given that it is in a ready-to-use solution form rather than requiring reconstitution (like ULG’s)
■ The generics are priced lower, with no chemical or clinical differences from ULG’s branded products
■ ULG acknowledged the implications these generics have on their product mix and ASPs. There’re observed changes in purchasing patterns, particularly among the price-sensitive customers. For the US market, purchasing channels often favor generic alternatives
■ ULG had to “relaunch” their generic offering (around late Sep to early Oct) to compete and defend market share, while keeping their branded IC-GREEN product
I still recall the marketing spin for their IPO – that they were almost a monopoly in the US (with ICG market share at around 83%), and how they were able to capitalize on this by raising prices
It took less than a year from ULG’s IPO listing (in early-Dec 2025) for the investment thesis to unravel
Let’s see how Mi Material (MIM) performs financially/operationally over time. I see some parallels in both companies

Professor Damodaran's write-up on Anthropic is such a fun read. It's not over-complicated that one needs AI to summarize/explain (lol) and encourages critical thinking
Link: aswathdamodaran.blogspot.com…
Reading this piece brought me back to these -
> revisiting the first principles of corporate valuation
> appreciating accounting as an art, not science
He noted - "don't be surprised to see people make cases for and against Anthropic using their spin of the data in the prospectus. Neither side will be convinced, or convincing, and will emerge with their priors about Anthropic intact and reinforced. I think that too much time and effort is being spent on going through this prospectus, as if it contains the answers to every question you may have on AI, when, in truth, it is a snapshot of a young company that is evolving. "
He then commented, "accountants sometimes use the discretion in accounting rules to make the numbers look more favorable for companies than they really are, but those are common problems across all companies, not just AI and Anthropic."
I saw folks argue about how his base assumption for cost of capital at 9.74% is too low but he did make these caveats:
■ he noted Anthropic's BB+ (non-IG) credit rating which reflects some degree of default risk, mitigated by a large cash buffer which will be augmented after the IPO
■ 9.74% as his base case is constrained by what the market is offering - the median cost of capital for US firms in Sep 2026 was 9.16% and that the third quartile for US firms is 9.88%
■ being a publicly traded large market-cap company opens access to new capital
More importantly, he said these:
"My advice, and feel free to ignore it, is that you should not spend too much time finessing the cost of capital, since of the many assumptions that drive this valuation, it is among the least critical"
Finally, he commented:
"Almost everyone who trades the stock right after the offering will be pricing, not valuing the stock. That is not meant as a slight, but as a reality check for investors, and especially those investors who seem to believe that the market owes them a payoff, just because they care about fundamentals."
Conclusion: Markets do not always behave the way you expect them to. CEOs/CFOs, driven by self interest, will always find ways to work the accounting rules in their favor. Investing is a personal decision. DYOR.
the true master of corporate finance has spoken
On a side note, gotta respect how he still uses blogspot
someone should get him on substack. I'm sure folks will gladly pay up

Anthropic's IPO was filed on October 26, 2026, and I value it's equity at about $1.475 trillion, which will inform my decision on whether to buy or sell its shares. To make your Anthropic choice, though, you should value it yourself, and I will provide a story and input structure to help you. bit.ly/3UTo3Gj
I'll be surprised if $AVGO Broadcom doesn't put up a fight for $LITE Lumentum (part if not whole) if $MRVL Marvell proceeds with an acquisition bid, notwithstanding potential antitrust risks
But the important question we should be asking: why would the Lumentum Board agree to sell itself now, given their exponential growth and capacity sell-out narrative?
Woah, this is $CBRS spicier than Jalapeño
tl;dr -
> inherent flaw with the connector material that Cerebras uses which results in their wafers aging 3 to 3.5x faster than NVIDIA's GPUs (i.e. 1.4 to 2.3 years vs 5 to 7 years)
> this explains why Cerebras adopts an architectural design with overprovisioning (dummy workloads) and routing, which results in constant near-peak power draws (70% - 80% even at idle state)
> by "arbitrarily" extending useful life of their WSE in their financial reporting, margins improved
> their shift to cloud infra ops masks this issue, which they can book system redundancy installs and replacements as capex
They think Cerebras' long-term target 60% core gross margin as a pipe dream
Reminds me of @insane_analyst who had been asking about parametric yields/etc


Most folks following Singapore news should have read/heard about today's meeting between the Singapore government and representatives of the 10 firms being investigated for their links to haze-causing fires in Indonesia
The largest alleged offender - Sinar Mas Group, which controls Asia Pulp & Paper, and Golden Agri Resouces, sent in a "Senior Advisor" (Bernard Tan), who reportedly declined to sit at the front row for the meeting lol
Who is Bernard Tan?
He served in the Singapore Armed Forces for 22 years before retiring as a Brigadier-General. He then went on to do other gigs before joining APP in 2017, right after the record-breaking haze in 2015, as their MD of Corporate Affairs & Sustainability, and Country President (Singapore) for Sinar Mas
I wonder what's the obsession or rationale behind these palm oil plantations hiring former military generals
Here's another one - Royal Golden Eagle (RGE), also named in the Greenpeace haze report but not summoned by the Singapore government
RGE has TWO former top-level military generals:
Bey Soo Khiang, who now serves as Vice Chairman of RGE and Chairman of APRIL. He was former Chief of Defense Force (1995-2000)
Perry Lim, who served as Chief of Defense Force between 2015-2018, then joined RGE as MD in 2019

Stabilization agent bank hard at work
$MIM.SI Mi Material


Hong Kong stock markets must be so distorted and manipulated that even the local diners (cha chaan teng) have table notices warning folks not to believe in "sugar-coated", "guaranteed winning" stock pitches by self-styled "experts"

Hope those who shorted or bought puts on $SKHY / $EWY closed their pos last week - esp given Hynix's 3Q and fwd guidance today
See what I mean when I said do nothing, or scale down risk if needed? There's just too much noise/rumors in between earnings
With all respect, this is the worst advice I'm hearing especially to FinX folks who are mostly retail/small indie funds/family offices (the large funds/pods are mostly here for the memes and momos)
Institutional funds short for two main reasons - to hedge (mkt/sector beta, idiosyncratic risks), or if they see frauds. Some long-only do index put overlays but most of them don't or can't short
Most hedgies keep a net long, if not neutral book because shorting is a hard game. There's borrow cost and potential losses are unlimited
What we are seeing in markets lately is de-grossing - i.e. unwinding of both long AND short positions, and overall reduction of book leverage
For folks (especially retail) who don't have access to the suite of instutitonal tools to hedge/short/manage risks, they may only have (and think) buying put options is their best option (pun)
But let's be real - up to 90% of retail options traders lose money. Reasons:
> they don't know how, or have the models to properly price volatility
> wide bid/ask spreads - friction cost is high unlike traded stocks
> time decay (theta)
Option trading is like gambling. With embedded leverage
The best thing to do given current markets?
Nothing
Scale down risks, if you need
Take a break. Log off. Go for a nice long walk or holiday. Spend time with your loved ones