

Building the next-generation financial data platform. We tweet updates about public stocks. Not Investment Advice.
San Francisco, CA
Joined May 2020
- Tweets711
- Following96
- Followers9.1K
- Likes1.2K




Pinned Tweet
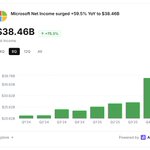
Microsoft is an absolute beast of a business.
$38B of net income +60% YoY
Meanwhile stock is down 19%.
Of the hyperscalers, $MSFT is the most hated despite owning 27% of OpenAI.

Hyperliquid.

Thesis: $HYPE will do $4B of revenue in 2030 (up 8x from ~$500m run rate today) and be valued at $230/token (up 3.5x from today) NOT as a better crypto exchange but as the #1 winner of RWA perps.
Take: Market is missing that Hyperliquid is NOT JUST a crypto exchange but is becoming THE default venue for investors trading global markets 24/7 from equities and commodities to FX, indices and pre-IPO companies -- taking share from ICE / CME (combined ~$17B of annual revenue) not Binance.
Price Target: We believe Hyperliquid will be a $230/token in 2030 (up 251% from today) with $4B revenue in 2030 revenue.
$4B of revenue at 25x P/S implies $104B in outstanding market cap & $230B of FV in 2030.
Core Assumptions:
> Hyperliquid becomes a generational business from the growth of RWAs perps not crypto.
> Assume $HYPE captures 0.50% of entire 2030 Notational Trading Volume, taking share from CME and ICE.
> Hyperliquid processes ~$21T of annual RWA volume by 2030, at roughly 1.6bps blended take rate (perps is 2 bps, HIP-3 is 1 bps), that generates approximately $3.2B of transaction revenue
> HIP-3 is the #1 growth driver of $HYPE revenue moving forward (50%+ of transaction revenue, up from 15% today)
> Market is missing stablecoin revenue which will contribute another ~$1B annual revenue with $25B of supply and 4% reserve yield.
Full memo to drop tomorrow at 10am ET
Happy Hyperliquid Summit Day in NYC.
Hyperliquid.

Who wins and loses from Open Standard?
Find out below:
The first Thesis by @artemis is out!
Thesis is an investing show where analysts, investors, and founders come on to defend one clear market view.
Our first episode is with the stablecoin / fintech goats @HadickM @ElBarto_Crypto.
We talk about who wins and loses from $OUSD and what Open Standard means for $CRCL.
Bonus: Rob nailed the prediction on the USMNT win over Bosnia :)
Enjoy 💜
Free Cash flow for Hyperscalers inflect in 2029E
Street has Hyperscaler FCF going down in 2026 and then growing exponentially in the years after spending on CapEX.


.@wallstreetbets is doing it again.
For a decade, Wendy’s on r/wallstreetbets meant one thing:
You blew up your account.
The joke was simple: lose everything trading options, and your next stop is living behind the Wendy’s dumpster.
It was never really about $WEN.
Until now.
Year-to-date, our Reddit data shows ~16,800 comments mentioning “Wendy’s” across r/wallstreetbets, r/stocks, and r/investing.
Most of that was culture.
Roughly 1 in 6 comments literally mentioned a “dumpster.” Thousands more referenced working there, the drive-thru, or Frostys.
The actual cashtag, $WEN, barely showed up.
In other words, 95%+ of the Wendy’s conversation was the meme.
Then the stock broke.
$WEN came into this setup near a 52-week low, down more than 45% over the past year. The business was under pressure from slowing traffic, higher beef costs, weaker consumers, and ugly same-store sales.
The Q1 print told the story: U.S. same-restaurant sales fell 7.8%, net income dropped, and adjusted EBITDA declined 10.6%.
The stock got cheap. The dividend yield pushed toward distressed-value territory.
Then the activist angle entered the chat.
Nelson Peltz and Trian own roughly 16% of Wendy’s and have reportedly explored funding for a potential take-private bid.
No formal offer has been made, but the ingredients are there:
A broken stock.
An activist with a large stake.
A new CEO.
A new CFO.
A turnaround narrative.
A possible take-private.
A heavily shorted float.
Reddit noticed.
And this week, the meme finally crossed over into the ticker. Reddit $WEN mentions exploded to 602, by far the biggest spike of the year. At the same time, the stock ripped to $7.40 after-hours on June 23, up 18%.
Is this the next Gamestop?

The most under followed goated investor: @ElBarto_Crypto
Must follow for alpha.


Did someone say SaaS isn't dead? 😵

I just wrote an article about the SaaSpocalypse and why I think the market is wrong on $CRM $NOW and $WDAY on @artemis. Please see below
artemis.ai/stevenfiorillo/ar…

Coinbase is the winner of stablecoisn and agentic commerce
Check out the research our friends did at @artemis
Coinbase is the winner of AI-native finance.
We believe $COIN can be a ~$300B+ company (6x from today)
Artemis open sources the BEST Coinbase financial model using onchain data.
You can now build models like the BEST analysts.
We believe Coinbase is WINNING in stablecoins, agentic commerce – not just as a crypto exchange.
Here’s the core assumptions
> Stablecoin supply reaches ~$3T in 2031 (~US Treasury official estimates)
> USDC is 30% of stablecoin supply
> Agentic Commerce ~$7.5T in yearly spend in 2031
> Coinbase Agentic Commerce is able to monetize and captures 1bp of the entire TAM
> Net transaction revenue grows 11% CAGR
> Subscription & Services goes from 40% of total revenue to 65% of revenue in 2031
In our bull case, Coinbase does ~$23B revenue in 2031 with ~$10B of net income.
At 30x PE that assumes ~$300B of marketcap (6x+ from today)
Full 12 page thesis drops at 5pm ET 👀

. $BIRD — Contrarian LONG.
Thesis: Cash-Return Setup with Free AI Stub
Trades at $5.68. Strip out the Q3 2026 special dividend ($4.00/sh in cash) and you're paying ~$1.68 for the NewBird AI stub.
Assumptions:
• $39M sold to American Exchange Group sale → $35–$36.2M net proceeds
• $35M / 8.71M shares out → $4.00–$4.15/sh special dividend
What's left in the stub (~$1.68/sh)
• $50M convertible
• $2.75M signed GPU lease
• = a real, funded AI shell — not vapor
Why $BIRD is mispriced
~70% of the current price is a near-deterministic cash return; the AI shell is effectively a free option on top.
The market is still pricing this as a meme/risky name when the fundamental setup is closer to a cash-stub arb with optionality.

The Neobank Landscape for 2026 just launched.
Check it out fintech investors!

Neobanks spent 15 years handing rent to sponsor banks, but now they don't have to.
In the past 4 months:
- @coinbase applied for a national trust charter
- @nubank received approval to create a US bank
- @krakenfx got a Fed Master Account
They can now access legacy payment rails.
At the same time, traditional fintechs are plugging into global crypto rails:
- @SoFi launched SoFiUSD
- @stripe acquired @Stablecoin , @privy_io and launched @tempo
- @RobinhoodApp is launching Robinhood Chain
The stack is getting crushed from both ends and the winners will own both sides of it.
Let's dive into what's happening 👇


Monday.com now trades for 1.4x ARR 🥶
- $1.3b ARR
- 25% YoY
- 25% FCF
Down 50% YTD. ALL in on AI Sidekick, Vibe, AI workflow, etc.
Do we not think Monday could be a Claude Cowork competitor?


Crowdstrike is down 14% YTD due to Claude Security fears.
Meanwhile:
✅ Founder led
✅ $5.2b ARR +24% YoY
✅ $376m FCF or 29% FCF
✅ Rule of 53
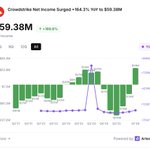
✅ Super profitable --$59m net income +169%
Claude Code isn't going to replace security -- AI + war + geopolitics will drive more demand for $CRWD


OpenAI is $13B ARR +137% YoY with -50% FCF.
At $1T, OpenAI trades at 76.9x EV/ARR which would be the highest multiple just behind Palantir at 110x.

Fintech Investors,
Payments are happening on chain. Check out the most recent proprietary data from @artemis stablecoin report on stablecoins onchain 👇
INTRODUCING: Part 2 of our Stablecoin Payments Report!
Co-written with @CastleIslandVC and @dragonflyvc, with data now through August 2025.
Stablecoin payments hit $10.2B monthly, up 70% since February and 137% since Aug '24, now at a $122B annual rate.
Here’s how the market evolved in just 6 months 🧵

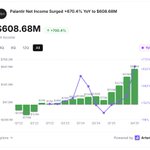
Palantir is a beast of a business $PLTR
- $4B ARR
- 48% YoY growth
- 105x EV/ARR
- 128% Net Dollar Retention
