




said it all
Good SUMMARY

If I was building a neobank today:
> B2B over B2C
> $50M+ revenue businesses as the ICP
> Distribution is the only moat
> Credit products for defensibility
> Target boring niches (they're usually cash rich)
> Understand B2B banking is a pure relationship game
> Founder-led marketing
> Position yourself for the UHNWIs
> Lend your own capital (higher margins)
> Dominate one industry before expanding (when you build for everyone, you attract no one)
> Verticalized financial-adjacent software
> Choose your sponsor bank WISELY
> Stablecoin support from day 1
> Underwriting is a MOAT
> Obsess over onboarding speed
> Build a marketing team that's chronically online
> Avoid competing on cashback alone
> Make switching from a legacy bank ridiculously easy
> Religiously track your unit economics (LTV, CAC, Profit Margins)
> Compliance is KEY
> Build strong referral partnerships
> Speed to response must be under 30 seconds
> Negotiate your BaaS contracts aggressively
> Obsess over activation and retention, not just signups
> Strong affiliate partnership program
> Onboarding should be painless
> Product is commoditized, distribution is the only moat
> Invest heavily in fraud prevention & security (AI will only make cyberattacks worse)
> Understand your biggest competitor isn't another neobank, it's JPMorgan
> Ship every financial product under the sun (AI makes this easy)
> Don't call yourself a neobank.
TLDR:
Fintech is competitive, but over 6M LLC's were formed in the US last year (record high)
The next generation of entrepreneurs DO NOT want to bank with legacy institutions.
There's still a massive opportunity to build a better experience and steal market share from incumbents.
1
2
80
This is the first of many but incredible efforts by Devon.
This revolution by edge city is making lives better and peaceful.
We all need good communities to live

Huge news: the Esmeralda project has secured its final approval!
Massive props to the team for pushing this forward, and we are excited to continue to be part of the Esmeralda journey ☀️
24


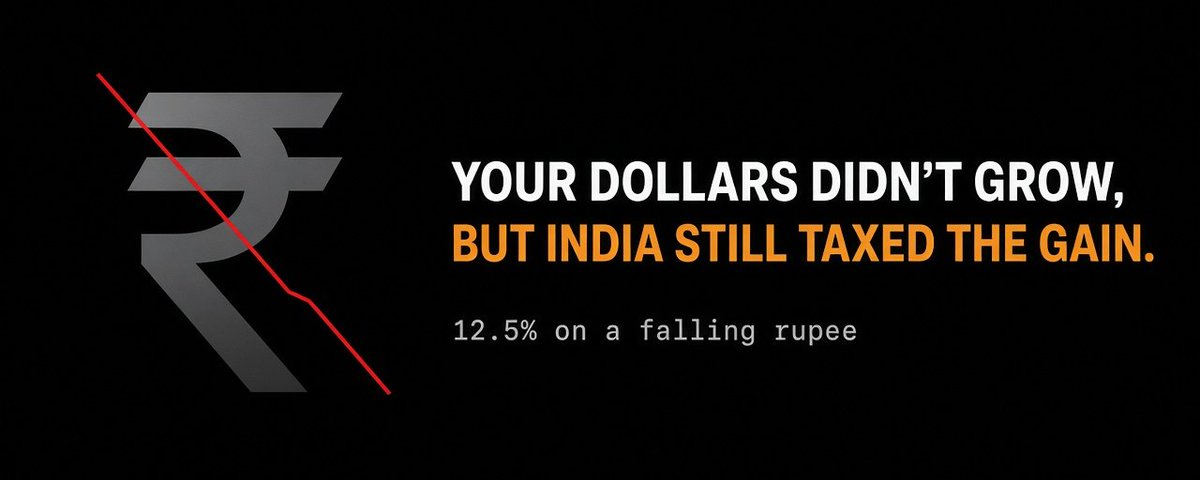
Brazil's top court is deciding right now whether foreign investors should pay tax on a currency's fall. India settled that question for itself years ago, and it chose to tax them.
If your dollars made nothing over eleven years, India can still charge you 12.5% on a "gain" that only exists because the rupee fell. It's a quiet tax on inflation.
15
$14bn just left stablecoins, and crypto Twitter is writing the obituary, but Visa is settling its own network in USPDT this same week.
Quantity theory of money explains why the supply chart shows an incomplete picture

1
22
Funds dumped ₩20tn of Samsung and SK Hynix after the US midterms and rotated straight into India, even though nothing about India changed that week.
I wrote up why India is suddenly the market's favourite way to hide from AI, and why that hedge could break really fast👇

30


ok so the midterms happened and everyone's calling it bullish. democrats took the house and the senate.
stocks ripped, dow +2%, nasdaq +2.5%. 10y down to ~4.9%. the dollar index slid to a 1-month low. gold back above $4k. everyone seem to be happy
but there’s something bugging me
CME FedWatch still shows ~80% odds the fed HIKES in december - hikes. not cuts. the election didn't change inflation. the fed doesn't care who won the senate. friday's payrolls matters more than any of these races, honestly
and look at where yields actually fell. the long end dropped more than the 2y. that's the market saying less fiscal chaos ahead, so the extra yield it wants on long bonds comes down. the 2y is the fed, and the fed barely moved. so if you're reading this as rates are going lower... it's not that. it's a long-bond trade, not a fed one
also tariffs don't sit with congress. trump keeps his veto too. congress can investigate and block budgets, but it can't really undo trade policy. so "gridlock fixes everything" feels a bit early
and the rupee barely moved, 94.74 to 94.64. the dollar fell and the rupee shrugged. oil and foreign outflows are still what's driving it, and if the fed hikes, the rate gap gets worse for INR. the reuters poll median still says 96 by end-jan
so here are my calls, screenshot this and roast me later:
- fed hikes 25bp in dec
- shutdown or budget scare before end-jan
-rupee weaker than 95 at end-jan
- gold stays above $4k through dec
unless payrolls blows out
idk, maybe gridlock is bullish. or maybe markets just priced the easy part and the fed shows up with the bill in december
what am i missing?
(not investment advice)

68
rbi just deleted a form for indian freelancers 👇
- if you’re paid in dollars, you don’t need separate EDF anymore
- your bank's payment details count as filing it
- backdated to apply from 1 oct 2026
- same for businesses, same deal it up to ₹10 lakh per payment
So finally less paperwork, same dollars. we take those as a step in accepting the move towards internet natives economy

60
Rishabh retweeted

Good intel on the US estate taxes for non resident US entities
Didn't know this prior to now


Rishabh retweeted
passport & visas tracker UI in a cryptographic secure data vault
shipped in 36 hours over at @JoinEdgeCity